
How to Save Money on a Low Income: 8 Real Strategies That Actually Work
Because 'Just Stop Buying Coffee' Is the Worst Financial Advice Ever Given
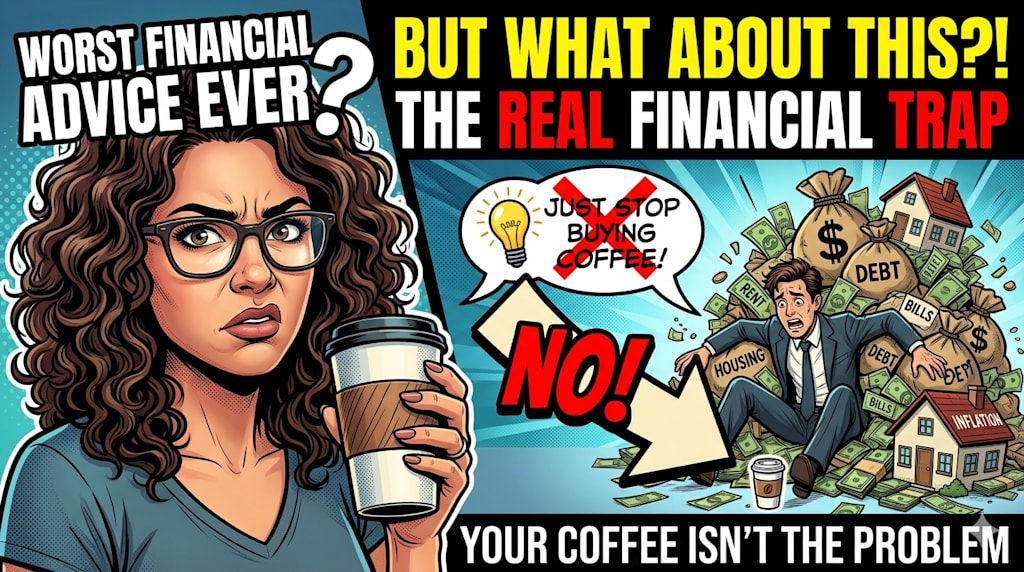
I want to start by saying something that most personal finance articles never bother to acknowledge: Saving money when you barely have enough to cover your bills is genuinely hard. It's not a mindset problem. It's not a lack of discipline. And it's definitely not solved by making your own coffee at home instead of buying a latte.
If you're living paycheck to paycheck, you already know what expenses to cut. You've already cut them. What you need are real, practical strategies that work when the margin is already razor-thin. So that's what this is. No fluff. No condescension. Just eight things that actually make a difference.
1. Save First — Even If It's Just $5 Here's the single most important shift you can make: stop trying to save what's "left over" at the end of the month. There is never anything left over. Life fills every dollar you give it access to. Instead, the moment any money hits your account — whether it's a paycheck, a side hustle payment, or a birthday gift — move a small amount out immediately. Even $5. Even $2. This isn't about the amount. It's about building the identity of someone who saves, no matter what. That identity compounds over time in ways that the math alone can't capture. Automate it if you can. Set up a separate account and schedule a tiny automatic transfer on payday. Make it invisible. Make it boring. Let it grow quietly in the background while you live your life.
2. Know Exactly Where Every Dollar Goes Most people have a rough idea of their spending. A rough idea is not enough. Spend one week — just seven days — tracking every single purchase. Write it down in your phone notes, use a free app like Mint or YNAB, or even a piece of paper. The method doesn't matter. The honesty does. What you'll find will probably surprise you. Not because you're reckless, but because small, frequent purchases are invisible until you see them written down. A $3 purchase five times a week is $60 a month. That's $720 a year. On things you likely can't even name right now. You can't fix what you can't see.
3. Attack Your Biggest Expenses First Personal finance advice loves to focus on small cuts — skip the takeout, cancel the streaming service. But small cuts produce small results. If you want to meaningfully change your financial situation, you need to look at your three biggest expenses: housing, transportation, and food. Can you get a roommate? Negotiate your rent? Move to a slightly cheaper area? Can you carpool, use public transit, or eliminate a car payment? Can you meal prep twice a week instead of buying lunch every day? Even a $100 reduction in one of these categories does more than eliminating every small luxury combined. Go where the money actually is.
4. Use the 24-Hour Rule for Any Non-Essential Purchase This one is simple and it works. Before buying anything that isn't food, rent, or a bill — wait 24 hours. That's it. Just wait. Most impulse purchases evaporate overnight. The thing you absolutely needed at 10 PM feels completely optional by morning. You've just saved that money without any willpower, without any deprivation — just a pause. For larger purchases, make it 72 hours. For anything over $100, give yourself a week. You'll be amazed how often you forget about it entirely.
5. Find Your "No Spend" Days Pick two or three days each week where you commit to spending nothing beyond fixed bills. No food delivery. No small online purchases. No "just this one thing." Zero. On those days, cook what's already in your kitchen. Find free entertainment. Rediscover what you already own. No-spend days are not about deprivation. They're about breaking the automatic spending habit that most of us don't even realize we have. When buying something requires a deliberate decision instead of a reflexive click, you naturally spend less — and feel better about what you do spend.
6. Negotiate Everything You're Already Paying For This is the most underused money-saving strategy there is. Your internet bill. Your phone plan. Your insurance. Your subscriptions. All of it is more negotiable than companies want you to believe. Call your providers. Tell them you're considering switching. Ask if there are any current promotions or loyalty discounts. In many cases, they will reduce your bill on the spot rather than lose you as a customer. A single phone call can save you $20 to $50 a month on one bill. Do this with three bills and you've found $600 to $1,800 a year — without cutting anything from your life.
7. Build a Tiny Emergency Fund Before Anything Else If you don't have any buffer savings, every unexpected expense becomes a financial crisis. A flat tire, a medical bill, a broken phone — any of these can wipe out weeks of careful saving and push you back to zero. Your first savings goal shouldn't be a vacation or a big purchase. It should be $500 to $1,000 sitting untouched in a separate account. That small cushion changes everything. It turns emergencies into inconveniences. It stops the cycle of going into debt every time life happens. Start there. That one goal, before anything else.
8. Find One Way to Earn More — Even Temporarily Sometimes the problem isn't what you're spending. Sometimes the income is genuinely too low to save no matter how careful you are. If that's where you are, the most honest advice is this: one extra shift, one small freelance project, one thing sold online, one weekend side hustle — even done once — can create a savings buffer that months of cutting expenses couldn't.
You don't need a second career. You need one extra $100 this month. Then maybe again next month. That's enough to start building something real.
The Truth About Saving on a Low Income Here's what nobody tells you: saving money when you don't have much of it is less about financial strategy and more about protecting yourself from the feeling that things will never change. Every dollar you save — no matter how small — is proof that you have some control over your situation. That proof matters more than the amount.
Start where you are. Use what you have. Keep going. If this was helpful, follow for more practical money tips — written for real people, not people who already have everything figured out.
About the Creator
eonpulse
Transform your financial future with smart tips on budgeting, saving, and investing. Helping young adults make wise money choices and gain financial freedom. Learn practical strategies to build wealth and take control of your finances.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.