How to Plan and Save for Your Child’s College Education in 2026
College Savings Calculator
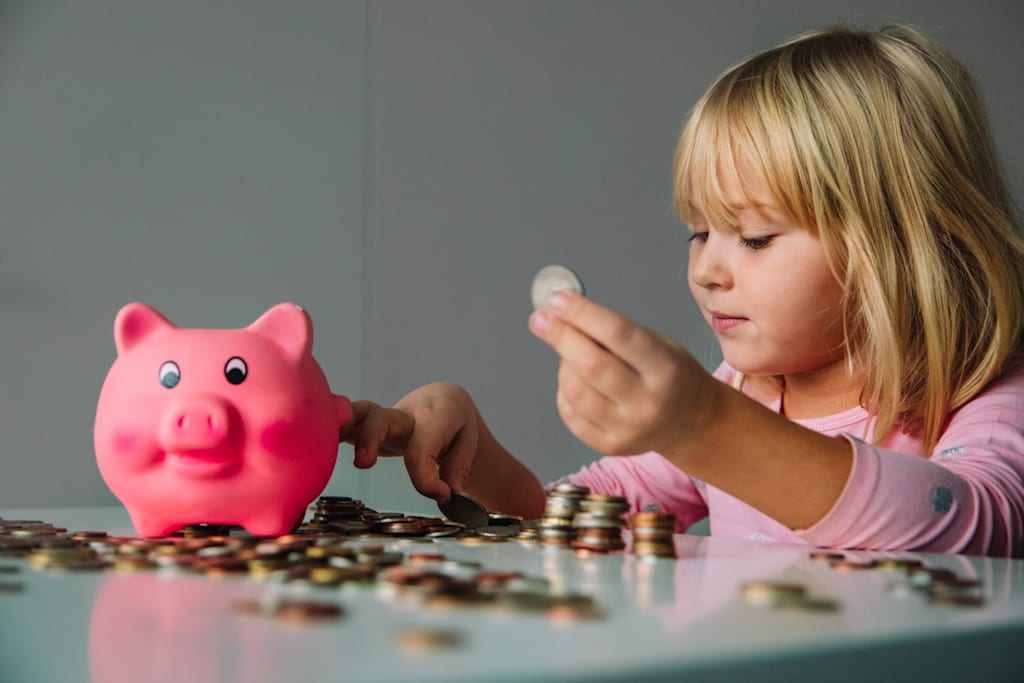
Planning for your child’s education is one of the most important financial goals for any parent. College costs are rising every year, and without proper planning, it can become a heavy burden later. Many families struggle at the last moment because they start too late or choose the wrong savings options. The good news is that with the right approach, saving for college can be simple, organized, and stress-free.
In this blog, we will understand how to save for college, the best education savings plans, how much you should plan for 2026, the difference between college savings and student loans, and the common mistakes parents should avoid. This guide is written in a simple way so you can easily take action in your financial journey.
Why College Planning Matters Today
Education costs in the United States have increased significantly over the years. Tuition fees, accommodation, books, and living expenses together create a large financial requirement. Many parents think they have enough time, but delaying the planning often leads to financial pressure later.
Starting early gives you a strong advantage. Even small monthly savings can grow into a large fund over time. The key is consistency and choosing the right investment plan based on your income and goals.
Proper college planning also reduces the need for high-interest student loans in the future, which can affect your child’s financial independence after graduation.
How Much Should You Save for College in 2026
There is no fixed amount that fits everyone, but having a rough idea helps you set a realistic goal. The total cost depends on:
- Type of college (public or private)
- Location (in-state or out-of-state)
- Course duration
- Living expenses
On average, college education in the US can range from moderate to very high depending on the institution. A good approach is to estimate future costs and plan for at least a portion of it through savings.
A simple method is:
Start by calculating current college costs and assume a yearly increase due to inflation. Then multiply it by the number of years left before your child enters college. This gives you a clear target amount to work toward.
Even if you cannot cover the full amount, saving a large portion reduces financial stress significantly.
Best College Savings Plans Explained
One of the most popular education savings tools in the US is the 529 college savings plan. It is designed specifically for education expenses and offers tax benefits when used correctly.
A 529 plan allows your money to grow over time, and withdrawals are tax-free when used for qualified education costs. This makes it one of the most efficient long-term savings options for parents.
Apart from 529 plans, other options include:
- Custodial accounts for minors
- Mutual funds focused on long-term growth
- Fixed deposits or savings accounts for short-term goals
Each option has different risk levels and returns. A balanced approach often works best, depending on your financial comfort.
Choosing the right plan depends on how early you start and how much risk you are willing to take.
College Savings vs Student Loan: What Is Better
Many families rely on student loans to fund higher education, but this often leads to long-term debt. While loans can help in emergencies, they are not always the best solution for planned expenses.
Here is a simple comparison:
College Savings
- No debt burden
- Financial freedom after graduation
- Lower stress for students and parents
Student Loans
- Immediate access to funds
- Long-term repayment with interest
- Financial pressure after education
A smart financial decision is to combine both approaches. Save as much as possible in advance and use loans only if required. This reduces dependency and keeps financial stability strong.
Smart Ways to Save for Your Child’s Education
Saving for college does not require a high income. What matters is planning and consistency. Here are some practical methods:
Start early, even if the amount is small. Time plays a major role in growth. Monthly contributions are more effective than random deposits because they build discipline.
Automate your savings so a fixed amount is transferred every month into an education fund. This removes the temptation to spend the money elsewhere.
Use long-term investment options instead of keeping all money in a regular savings account. Growth-oriented plans can help your money increase over time.
Also, review your plan every year. As income increases, try to increase your savings amount gradually.
Common Mistakes Parents Make in Education Planning
Many parents want to support their child’s education but make small mistakes that create problems later. Some common errors include:
Starting too late and trying to catch up quickly. This reduces investment growth time and increases financial pressure.
Not estimating future costs properly. Education expenses grow every year, so planning based on current costs alone is not enough.
Depending fully on student loans without creating any savings backup.
Choosing unsafe or unclear investment options without understanding the risk.
Ignoring regular review of the savings plan. Financial goals should be updated based on income and market changes.
Avoiding these mistakes can make your education planning much stronger and more reliable.
Building a Strong Education Fund Step by Step
The best approach is to divide your planning into simple steps. First, decide your target amount based on expected college costs. Then choose the right savings plan like a 529 or mutual fund.
Next, set a monthly savings goal that fits your budget. Even small amounts matter when started early. Over time, increase your contributions as your income grows.
Finally, stay consistent. Education planning is not about quick results but about long-term discipline.
Final Thoughts
Saving for your child’s college education is one of the most valuable financial decisions you can make. It not only supports their future but also reduces financial stress for the entire family.
With proper planning, smart savings choices, and early action, you can build a strong education fund without pressure. Whether you choose a 529 plan or another investment option, the key is to start today rather than waiting for tomorrow.
A well-planned education fund gives your child freedom to focus on learning without worrying about financial challenges.
About the Creator
Vantage Financial
Vantage Financial is a group of seasoned financial consultants who have worked in the industry for more than 110 years.
Website : https://vantagefinancialwi.com/
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.