
They Don’t Want Your Money. They Want Your Contact List.
Predatory lenders don’t expect you to repay. They expect your family to. Here’s how the trap works.
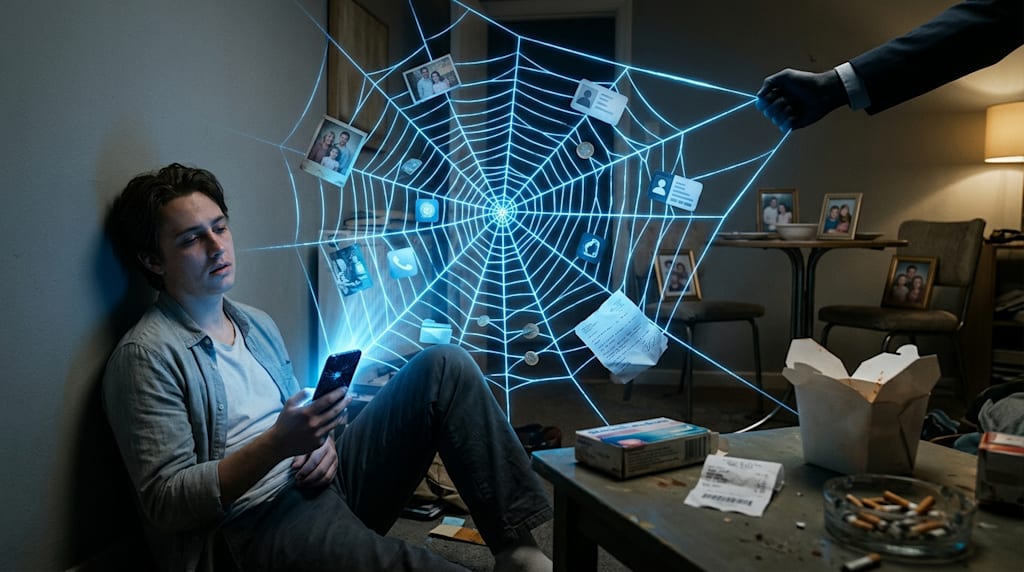
They Do Not Fear Default. They Fear You Not Borrowing.
A bank loan officer asks for pay stubs, tax records, mortgage statements. A payday app asks for your ID, contacts permission, and a selfie. Three minutes later, you have a loan.
Amount: $1,000. Term: 7 days. Repayment: $1,080. You think: $80 interest. Fine. You miss the fine print. Daily penalty: 1% of unpaid principal. Collection service fee: $200 per attempt. You also miss that $200 is a “membership fee” and $100 is an “express fee.” You never calculate what you actually received.
The credit card rejection text is still on your phone. “Your score is insufficient.” You open another app. Credit line: $1,500. Daily rate: 0.05%. Why does the app say yes when the bank says no?
The bank makes money when you repay on time. If you default, the bank goes to court, spends time and money, and may still lose. The app makes money when you repay on time: small daily interest. If you default: penalties, late fees, service fees, collection fees. If collectors scare you, you borrow from your parents, your friends, other apps. That is the profit.
Its risk system does not check pay stubs. It checks how many contacts you have, who you call most, how many lending apps are on your phone, when you last missed a payment. The moment the bank rejected you, this system marked you: good to lend.
Page seven of the contract has bold text: “Borrower agrees that in case of overdue payment, the platform may contact emergency contacts and address book contacts by phone or SMS to remind the borrower to repay.”
You did not read it. You wanted the money.
Day seven: you miss payment.
Day eight: your mother gets a call. “Your son borrowed money from our platform. Today is the last day. Tell him to handle it, or we take the next step.” She calls you. You say it is a spam call.
Day ten: your aunt gets a call. Day eleven: your coworker. Day twelve: your ex-girlfriend gets a text. “Do you know this person? He has an overdue loan. Tell him to settle it.”
Your contact list is the collateral. You have no house, no car, no savings, no steady income. You have parents, relatives, friends, coworkers, and a reputation. The platform counted all of it.
You cannot repay. Salary: $2,500. Rent: $1,000. Food: $750. Left: $750. The loan with penalties: $3,250.
You open another app. Credit line: $2,000. Daily rate: 0.08%. Origination fee: 15%. You receive $1,700. Repay $2,000 in seven days.
You borrow. You pay the first platform. Collections stop. You breathe.
Seven days later, the new loan is overdue. Collectors call the same contacts. Your mother gets another call, this time from a different company. She asks: How much do you owe? You say: not much.
You open a third app.
You do the math.
First platform: borrow $1,000, receive $800, repay $1,080.
Second: borrow $800, receive $680, repay $800.
Third: borrow $600, receive $480, repay $600.
Total received: $1,960. Total repaid: $2,480. Still owe fourth platform: $500.
Debt went from $1,000 to $500. Looks smaller. Received cash went from $800 to $480. Contact list was called three times. Mother cried twice. Father sat silently for one night. Ex-girlfriend blocked you.
You reach day 180.
You change your phone number. You move. You delete all apps. You think it is over.
Second month: an unknown number calls your new phone. They quote the first platform’s contract number. They say your debt has been transferred to their company. They want to negotiate. Principal plus interest plus penalties: $6,750.
You ask: What company?
They give a name you've never heard. You look it up. Registered capital: $150,000. Founded three months ago.
Your debt was packaged and sold. Original: $3,250. Sale price: maybe $500. Whatever they collect is profit. You are no longer a borrower at a platform. You are an entry in an asset package.
You search “overdue payday loan what to do.”
First result: professional debt optimization, stop interest, repair credit, add WeChat.
Second: anti-collection alliance, teaches you how to handle violent collection.
Third: a lawyer says these three types of loans do not need repayment.
You add the first WeChat. They say: pay a $75 consultation fee; we make a plan. You pay. They send a template. You fill it out. You ask: what next? They say: wait for our notice. You message again. Red exclamation mark.
You call 911.
Police ask: Did they hit you? No. Did they threaten your physical safety? No, they said they would contact my family. Police say: This is a civil dispute. You can complain to financial regulators.
You call the regulator. Busy. Again. Busy. You call the consumer hotline. They say: Call the financial regulator. You open your computer. Find a complaint template. Fill in platform name, loan amount, actual received, repaid amount, collection method, call recordings, text screenshots. Submit.
Thirty days later: your complaint has been forwarded. Then nothing.
Your mother takes out her passbook. $8,000. She saved for six years. Your father sits on the couch. Says nothing. Four cigarette butts in the ashtray. You transfer the money to the collection account. They say: still $300 short. Before noon tomorrow.
Your mother withdraws $300 more.
Your phone goes quiet. No collection calls. No texts. No one in your contacts asks if you owe money.
You open WeChat. Seven contacts gone. Two friends, three coworkers, one cousin, one ex-girlfriend. You did not delete them. They deleted you.
You sit in your rented room. A box of stomach medicine on the table. You bought it when the collection was worst. Next to it: your phone, cracked screen, never replaced. You open the app store. Search history still has “loan,” “credit,” “emergency.” You delete each one. You open your bank app. Balance: $6.43. You open contacts. Find your mother’s number. You look at it for a long time. You do not call. You open notes. Type: “Never borrow again.” Then delete it. You order takeout. Use a coupon. Pay $1.75.
When it arrives, you are reading a news alert: police busted a large online loan shark ring, billions involved, hundreds arrested. You swipe it away.
The stomach medicine is still on the table. You forgot to take it.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.