
Three Pillars, Zero Foundation: Why Chinese Lenders Lost Everything in India
They brought algorithms to a knife fight. The knife was the entire Indian legal system.
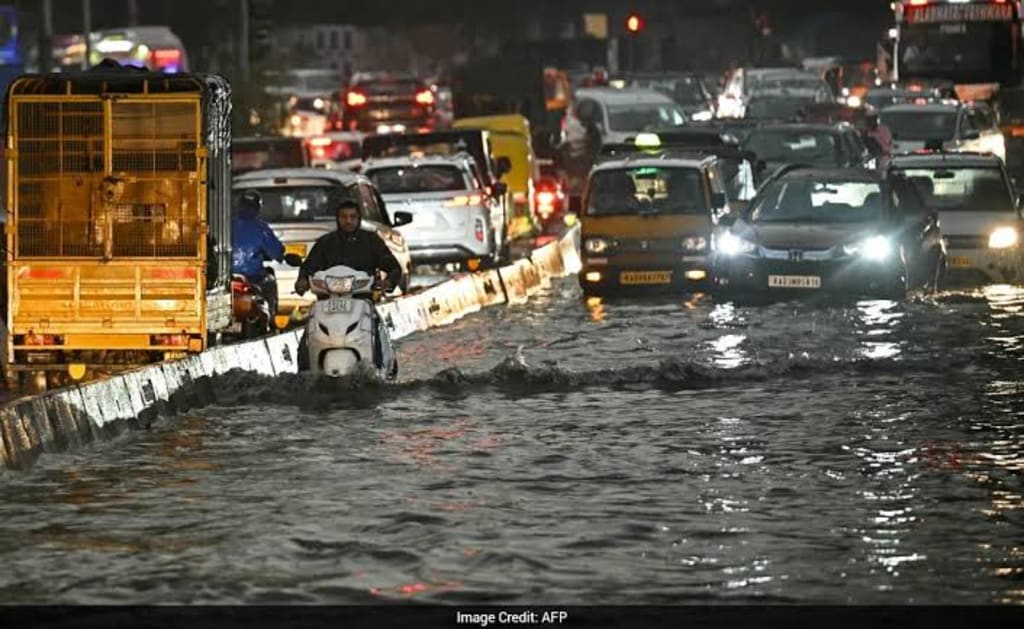
Bangalore, rainy season, 2023. In an office covered with whiteboards, the India head of a Chinese-funded online lending platform called over the risk-control director and pointed at the first-payment delinquency numbers on the screen: "It's already over 30% in the first month. In China you claimed you kept first-payment delinquency under 3%?"
The risk-control director was not rattled. He said, "Indians have no credit records. Our algorithm gives us a dimensional advantage. Give it two more months; once the model is fed enough data, it will be fine."
Two months later, first-payment delinquency was over 50%. Three months later, the collection team began getting calls from borrowers' cousins: "That app of yours. My cousin said you can get money just by filling in some information. Which app store do I search?"
The risk-control director did not live to see the day the model was "fed full." What he got was an RBI guideline and a call from the state police.
The first pillar: credit reporting
In China, online lenders dare to lend to a young person with no collateral and no stable job or bank statements. The confidence comes from the central bank's credit-reporting system, not the algorithm. If you miss a payment, mortgages, car loans, credit cards, and even background checks for some jobs will flash red. The platform does not need to punish the borrower itself. It only needs to report the delinquency and let the state credit system do the punishing.
India has four RBI-licensed credit bureaus: CIBIL, Experian, Equifax, and CRIF. On the surface it does not lack credit reporting. But by World Bank measures, about 37% of adults, nearly 500 million people, are not covered by any credit bureau. CRIF High Mark's data is more specific: as of February 2026, the credit-active population reported to consumer credit bureaus was only about 290 million, while the adult population exceeds 900 million.
Most of those 500 million people are in rural areas, working in agriculture or low-end services, transacting in cash. You cannot find their credit records, and they have never paid any price for "having a credit record." Tell someone who has never been constrained by the credit-reporting system that "a missed payment will go on your credit record," and his reaction is not fear. It is "So it gets reported. So what?"
The bigger problem is identity verification. India has Aadhaar and eKYC, but when it comes down to a specific platform's risk-control process, a person with no credit file can pass review on most pure online platforms with a new SIM card, a forged employment certificate, and someone else's bank card. The anecdote about facial recognition being fooled by a pet photo circulated widely; there is no need to take it literally, but the problem it points to is real: when neither identity verification nor credit verification has a strong institutional anchor, the fraud cost of pure online KYC approaches zero.
An Indian borrower later summed it up bluntly in a training-class group chat: "Money arrives, delete the app, change the SIM card. Money that appears out of nowhere on my phone. Why should I repay it?"
For the target customer base, the first pillar does not exist.
The second pillar: the courts
The second thing Chinese borrowers fear is the list of dishonest judgment debtors. Restrictions on high spending, frozen accounts, effects on children attending high-fee private schools. These measures are not perfect, but for someone with a stable job, assets, and a fear of trouble, they have teeth.
India's judicial time scale is a different algorithm. In ordinary money-recovery litigation, from filing to first-instance judgment, three to seven years is normal. Practitioners at the Bombay High Court estimate that getting a case listed often takes more than twenty years. Enforcement itself is also badly backlogged.
Someone borrows 5,000 rupees and misses a payment. The platform goes to court: filing fees, lawyer fees, and time costs far exceed the 5,000 rupees itself. Even if it wins, if there are no assets to enforce, the judgment is a sheet of paper. India has 45 million cases waiting to be reviewed. That is the order of magnitude of the pending caseload, not a metaphor. By the time his grandson gets married, the case may still not have been listed.
The second pillar fails for a simpler reason: the platform will never sue. Economic rationality does not allow it. For a loan of a few thousand rupees, judicial relief goes straight to zero on the cost-benefit sheet.
Borrowers do not need to understand the law. They only need to know one thing: the platform will not go to court over this amount of money. This information is common knowledge in loan-farming groups.
The third pillar: face
The most effective collection tactic in China is contact-list bombing. Call the borrower's father, his boss, his childhood friend in the village. The damage comes from the social judgment the call triggers, not the call itself: you cannot hold your head up in the village; you cannot face people at work. Losing face costs something. The acquaintance society carries out the punishment for you.
India is not without an acquaintance society. But when a collection call goes out, the reaction it triggers is different. A collector called a borrower's cousin. After hearing it, the cousin's first reaction was not "Why isn't my cousin repaying the debt?" It was "Wait. Which app did you borrow from? Is the paperwork complicated? Help me get one too."
This detail is partly anecdotal and cannot generalize to all Indian borrowers. But the mechanism difference matters: when collection calls trigger product inquiries instead of social punishment, collection turns from an asset-preservation tool into negative customer-acquisition cost. The more you call, the more new customers you acquire, and the faster you lose money.
India quickly grew an industrial chain: people run classes teaching how to forge documents, bypass facial recognition, borrow from multiple platforms, handle collection scripts, and gather evidence to complain to the RBI about platforms. Borrowers take the biggest cut, intermediaries take commissions, and technicians charge service fees. Blame the product design, not Indian character. High interest, loose underwriting, and contact-list collection naturally attract fraudsters and multi-platform borrowers and squeeze out or crush ordinary borrowers who are willing to repay. Adverse selection.
The third pillar did not break. It flipped around and smashed the platform on the head.
The arithmetic
The domestic financial model of "high interest covering bad debt" could still struggle on for a bit. Fifty percent bad debt? Then push the all-in annualized rate to 200% or even 300%, deduct upfront interest from the principal, and you can always earn it back.
RBI's 2022 Digital Lending Guidelines blocked half of that road: regulated entities must disclose the all-in annualized cost (APR), data must be localized, access to contacts and cameras without consent is prohibited, and there are explicit rules for due diligence on LSPs and for collection conduct. The 24% interest-rate cap is closer to the regulatory tradition in the NBFC-MFI (microfinance) segment; it is not a universal red line for all digital loans, but state-level legislation is tightening. Karnataka's 2025 microfinance ordinance provides that coercive collection can be punished by up to 10 years' imprisonment or a fine of 500,000 rupees. Tamil Nadu's relevant bill also provides for up to 5 years.
Do the arithmetic: assume a 50% bad-debt rate, and the annualized interest rate is capped at 24%. Lend out 100 rupees. You get back 50 rupees of principal plus interest. Interest at 24% on 50 rupees is 12 rupees, so at the absolute best you recover 62 rupees. You lose 38 rupees. This does not yet include customer-acquisition costs, payment-channel fees, server costs for data localization, or the labor costs of a compliance team.
The premise of high interest covering bad debt is "high interest." High interest is locked down, bad debt has not fallen, and the inequality has no solution.
Then payment channels were blocked, apps were removed, and funding channels were frozen or seized. RBI guidelines and state laws gave regulators enough tools. The product design of Chinese-funded platforms happened to step on every red line: ultra-short terms, upfront deductions, contact-list permissions, cross-border data risk control, and high interest covering bad debt. Local compliant NBFCs can operate at delinquency levels of around 6%. From the beginning they are embedded in India's licensing, credit-reporting, data-localization, and collection-compliance framework. They do subprime lending inside the system. Chinese-funded platforms do arbitrage lending outside the system. Once the arbitrage window closes, the model dies.
Exit
In the winter of 2024, the whiteboards in that Bangalore office were wiped clean. Before the risk-control director returned to China, he sent a message in the group chat. No one replied. On the desk he left a half-finished box of stomach medicine and a printout of the RBI guidelines, with page three folded at the corner.
India's local loan-farming training classes were still running. Among the new class, someone had just borrowed one last sum from an app that had already been removed and was asking the teacher: "Which Chinese platform can we farm next?"
The teacher scrolled through his phone and said, "Wait and see. I hear new ones are coming in again."
In a place where 500 million people are credit-invisible, debt litigation is measured in years, and violent collection can land you in prison, lending is a different business. Treating it as the same one costs you more than money.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.