
You’re Probably Broke at 55 Because of These 3 Money Lies (Fix Them in 2026)
The #1 Wealth Killer Middle-Class Families Still Fall For (It’s Not What You Think)
Look, I’ll be honest with you. Most people never build real wealth—not because they don’t earn enough, but because they think about money all wrong. I’ve seen this up close over 15 years of running businesses and working with wealthy clients. The rich aren’t just grinding harder. They’re playing a completely different game.
Heading into 2026, the rules have shifted again. Inflation’s still hanging on in some places, AI is flipping whole industries overnight, and traditional returns don’t look anything like they did ten years ago. That’s actually good news. When the landscape changes, the people who adapt fastest win.
Below are ten strategies I’m personally using right now and recommending to private clients. No fluff, no “manifest your millions” junk. Just real tactics you can actually use this year.
1. Get the asset-first mindset locked in before you buy anything else
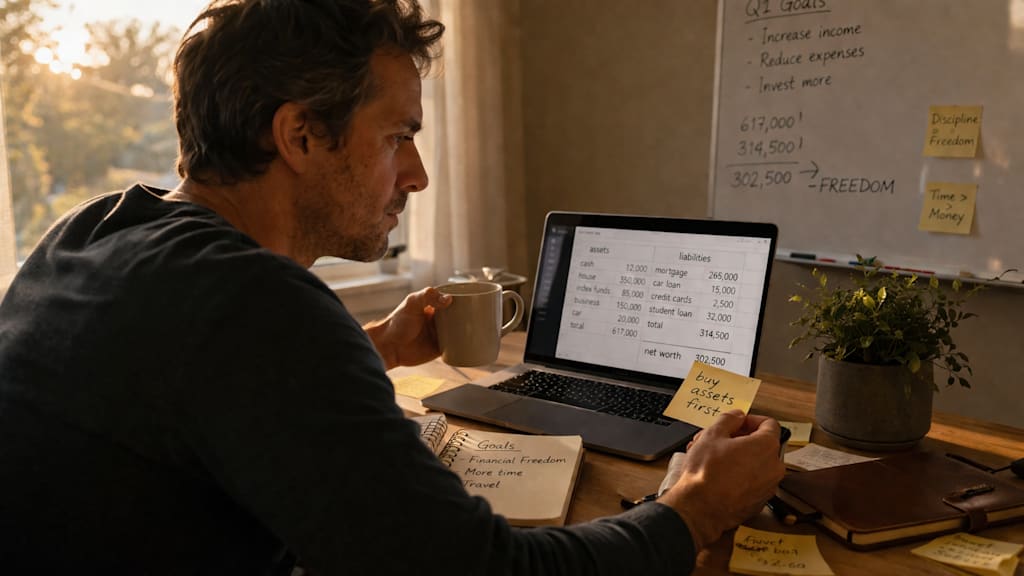
Here’s the biggest difference I’ve seen between wealthy people and everyone else. The rich buy assets. The middle class buys liabilities they think are assets. That new Tesla? Liability. The boat? Liability. That “investment property” bleeding cash every month? Also a liability, sorry.
In 2026, an asset is anything that puts money in your pocket while you sleep. Dividend stock. Cash-flow-positive rental. Digital course that sells on autopilot. Small software subscription.
How to actually do this: before any big purchase, ask yourself, “Would a wealthy person buy this, or would they invest the money instead?” I’m not saying never enjoy your money. Just flip the order. Buy assets first. Use the income from those assets to buy toys later. Most people do the reverse and wonder why they’re broke at fifty-five.
Try this next week: look at your last five large purchases. Which ones will still have value—or generate income—five years from now? Cut the rest ruthlessly.
2. Take small swings at asymmetric opportunities
Wealthy people love something most are terrified of: asymmetric risk. Fancy term for bets where you can lose a little but stand to gain a lot. Think 10x or 100x potential, not 20% annual returns.
What does that look like now? Early-stage AI startups (check out Republic or Wefunder). Undervalued crypto projects with actual utility after the hype died down. Pre-IPO secondary markets. Even a side hustle that could scale, like a niche SaaS tool you build on weekends.
But here’s the catch: don’t go all in. The wealthy put 5–10% of their portfolio into these moonshots. The other 90% is boring, steady, compound growth. That way nine bets can go to zero, but the tenth pays off 50x and you’re still ahead.
3. Own real estate in overlooked micro-markets
Real estate isn’t dead. But buying an overpriced rental in Austin or Miami right now? That’s a trap. Wealthy investors have moved into secondary and tertiary cities where remote work created new demand but prices haven’t caught up yet.
Think Spokane, Washington. Huntsville, Alabama. Tulsa, Oklahoma. Parts of Ohio like Columbus. These places have job growth, reasonable property taxes, and cash flow that actually makes sense. You can still find duplexes or small multi-family units with 6–8% cap rates if you know where to look.
Use tools like Roofstock for turnkey rentals or Crexi for commercial residential deals. Even better, partner with a local property manager in that micro-market before you make an offer. They’ll tell you which blocks to avoid and which are gentrifying.
4. Build digital assets that actually scale
Here’s something wild: the richest people I know in 2026 aren’t landlords or stock pickers. They own digital assets that cost almost nothing to reproduce. A software library. An AI-powered newsletter with 50,000 subscribers. A YouTube channel monetized three ways. A Notion template shop that sells while they sleep.
Why does this work so well? Because digital assets scale infinitely. One hour of work can generate value for ten thousand people. You can’t do that with a job or even most rental properties.
What’s working right now:
- Niche AI automation tools (like automated report generators for small businesses)
- Premium newsletters on beehiiv or Substack in high-value niches (finance, health, B2B)
- Digital courses with live cohorts plus recordings, selling for $500–2,000
- Micro-SaaS solving one specific pain point (say, a tool that auto-categorizes receipts for freelancers)
I’m not saying it’s easy. But it’s way cheaper than starting a physical business. Your main cost is time and maybe a few hundred bucks for hosting or software. The upside? A digital asset can sell for 3–5x annual profit on marketplaces like Acquire.com when you’re ready to exit.
Start tiny: pick one small problem you understand deeply. Build a simple solution—even a Google Sheet template or a ChatGPT prompt library. Sell it for $29. Validate demand. Then build the real thing.
5. Use tax-efficient vehicles so you keep more of what you earn
You’ve heard it before: it’s not about how much you make, it’s about how much you keep. But here’s what wealthy people actually do differently—they structure their money so taxes don’t eat the compounding.
With potential tax changes on the horizon in 2026, these vehicles are non-negotiable:
Roth IRA or Roth 401k: Max it. Yes, you pay taxes now. But every dollar grows tax-free forever. If you’re in your thirties or forties, that’s hundreds of thousands in saved taxes over a lifetime.
Health Savings Account (HSA) : Triple tax advantage. Deduct contributions, grow tax-free, withdraw tax-free for medical expenses. After 65, you can use it for anything penalty-free. Wealthy people treat HSAs like secret IRAs.
1031 Exchange (for real estate): Sell a property, roll all gains into a new one, pay zero capital gains tax. Rinse and repeat. That’s how small landlords become empire builders.
Donor-Advised Funds: Want to donate but also save on taxes? Bunch several years of giving into one tax year to itemize deductions, then distribute the grants over time.
6. Create passive income—but most “passive” isn’t really passive
I’ll be real: true passive income is rare. Wealthy people know this. What they call “passive” usually means intense upfront work, then slow maintenance. But that trade-off is worth it once the machine runs itself.
Here’s what actually works in 2026:
Dividend growth stocks: Companies that have raised dividends for 25+ years (Pepsi, J&J, Procter & Gamble). Reinvest the dividends. Let it snowball for a decade.
Peer-to-peer lending (carefully): Platforms like Fundrise or Prosper. Diversify across hundreds of small loans. Expect 6–10% returns but some defaults.
Royalties: Write a short ebook on a niche skill—“How to fix a garbage disposal in 20 minutes”—and publish on Kindle. Or create stock music, AI voice clips, or print-on-demand designs. Small checks add up.
Private REITs: Not the public ones everyone knows. Private REITs often have higher yields (7–9%) but lock your money for 3–5 years.
The mistake most people make? Trying five streams at once and doing none well. Pick one. Build it to $500 a month. Then add the second. Repeat.
Example: a friend of mine spent six months creating a spreadsheet course for small construction business owners. It was a grind. But now it sells $3,000–5,000 monthly on autopilot. She spends two hours a week on support emails. That’s about as passive as it gets without a trust fund.
7. Network with intention—your net worth really does follow your network
Cringe? Maybe. True? Absolutely. Every wealthy person I know has a small circle of ambitious peers who push them, share deals, and open doors. You don’t get those opportunities on LinkedIn or Twitter threads.
In 2026, the best networking isn’t at generic mixers. It’s in focused, high-signal environments:
- Mastermind groups (paid and vetted, typically $200–1,000 a month)
- Private investor clubs (some surprisingly affordable for accredited investors)
- Industry-specific conferences (smaller the better—200–500 attendees is the sweet spot)
- Local entrepreneurial meetups (check Meetup.com or Luma)
Here’s a specific tactic: find three people who are two steps ahead of you in your niche. Offer them something valuable first. Not “can I pick your brain.” Instead: “I noticed you struggle with X. I built a small tool that helps. Want a free license for your team?” That gets conversations started.
Then stay in touch without being needy. Share what you’re learning. Ask thoughtful questions. Over 6–12 months, those relationships turn into deal flow, partnerships, and mentorship.
Uncomfortable? For many, yes. But so is being broke at retirement. Pick your hard.
8. Automate your wealth system so you don’t have to think about it
Willpower is overrated. Systems are underrated. Wealthy people don’t rely on remembering to invest or pay themselves first. They automate everything so the machine runs while they sleep.
Here’s your 2026 automation checklist:
- Pay yourself first: automatic transfer on every paycheck—10–20% into a separate investment account. Not what’s left after bills. First.
- Auto-invest into low-cost index funds like VTI or VOO. Same day each month. Dollar-cost averaging removes the stress of timing the market.
- Use a robo-advisor for smaller accounts (Betterment or Wealthfront). They handle rebalancing and tax-loss harvesting automatically. For accounts under $100k, the fee is worth the time you save.
- Auto-pay all bills from a dedicated checking account you fund monthly. That way you never accidentally spend rent money on a weekend splurge.
- Set a “wealth calendar” reminder every quarter to review asset allocation, rebalance, and check for new tax opportunities.
I’ve seen people double their savings rate in six months just by automating. No extra discipline required. That’s the power of removing yourself from the equation.
Don’t overthink it: start with one automation this week. The 10% paycheck transfer. Once that runs for 60 days without you touching it, add the auto-invest. Small steps compound.
9. Hedge against inflation with real stuff, not just stocks and bonds
Inflation in 2026 is weird. Some sectors deflating (used cars, lumber), others stubbornly high (insurance, property taxes, services). Wealthy people protect themselves by owning things that benefit from inflation, not just survive it.
What’s working now:
Gold and silver: Boring but effective as a small hedge (5–10% of portfolio). Physical bullion from reputable dealers like APMEX. Avoid ETFs unless you want counterparty risk.
Fine art and collectibles: Not just for billionaires. Platforms like Masterworks let you buy shares in million-dollar paintings. Or go smaller—graded vintage Pokémon cards (seriously). Some have outperformed the S&P 500 over five years.
Farmland and timberland: Through platforms like AcreTrader or Farm Together. Farmland has historically low correlation with stocks and positive real returns. Minimums start around $10k–25k.
Cryptocurrency (defensive lens only) : Bitcoin only for this purpose. Not meme coins. Treat it as a long-term inflation hedge, not a trading vehicle. Allocate 1–3% maximum.
The key is diversification across uncorrelated assets. When stocks drop, gold often rises. When the dollar weakens, crypto may move. You’re building a portfolio that doesn’t all sink together.
Warning: don’t go overboard. Physical assets have storage costs, insurance, and liquidity issues. Keep most of your wealth in productive assets—businesses, real estate, stocks.
10. Reinvest profits ruthlessly and dodge lifestyle inflation
Here’s where most lottery winners go broke. They get a windfall or a big raise and immediately upgrade their lifestyle. New car. Bigger house. Fancier restaurants. Wealthy people do the opposite: they reinvest the gains back into the asset machine.
I’m not saying live like a monk. But there’s a massive gap between “comfortable” and “conspicuous consumption.” Every dollar you spend on depreciation (cars, clothes, gadgets) is a dollar that’s not working for you.
The 50/30/20 rule for wealth builders in 2026:
- 50% needs (housing, utilities, groceries, insurance)
- 30% investments and asset purchases—not savings, investing
- 20% wants (travel, dining, hobbies)
Notice wants are the smallest category. That’s flipped for most people.
Your 2026 game plan (keep it simple)
You don’t need to do all ten at once. That’s a recipe for burnout. Pick three that resonate most. Implement them over 90 days. Then add another.
Here’s a simple starter sequence:
Month 1: Master the asset-first mindset (#1) + Automate your wealth system (#8). Just these two will change your trajectory.
Month 2: Open a Roth IRA and set up auto-investments into a low-cost index fund (part of #5). Start researching one asymmetric risk bet (#2).
Month 3: Build or buy one small digital asset (#4). Could be a $49 template. Just start.
The specific tactics matter less than the habit of building wealth systematically. Wealthy people aren’t geniuses. They’re just consistent folks who made wealth-building automatic and non-negotiable.
By December 2026, you could realistically have an extra $10k–50k in assets, depending on your starting point. More importantly, you’ll have a system that runs without you thinking about it every day. That’s the real win.
If this helped, we’ve got a deeper dive on tax-loss harvesting for 2026 and how to evaluate early-stage startups like a VC. Also a free calculator that shows exactly how much you need to invest monthly to hit your target—linked in the sidebar.
Frequently Asked Questions
Are these strategies risky if I’m close to retirement?
Adjust the mix. Asymmetric risk bets should be tiny (1–2%) or zero. Focus on dividend stocks, tax-efficient vehicles, and stable real estate. And definitely work with a fee-only financial planner who specializes in retirement. The strategies still work—you just turn down the volatility.
How do I know if I’m buying an asset or a liability?
Easy test: does it generate positive cash flow after all costs? A rental property where rent covers mortgage, taxes, insurance, maintenance, and leaves profit? That’s an asset. If you’re losing money every month hoping for appreciation, that’s speculation. Same for a business, a website, even a savings account (interest is cash flow). No cash flow? Not an asset.
What’s the single biggest mistake people make when trying to build wealth?
Trying to get rich quick. I see it constantly. People chase hot stock tips, crypto pumps, or get-rich-quick real estate schemes. Then they lose money, get discouraged, and give up. Wealthy people build slowly, boringly, and consistently.
Is it too late to start in 2026 if I’m over 40?
Absolutely not. The second-best time to plant a tree is today. You’ll need a more aggressive savings rate (think 25–30% of income instead of 15%) and you might take slightly more risk within reason. But I’ve seen people start at 50 and retire comfortably at 65. Focus on what you can control—earning more, saving more, investing smarter. Stop worrying about the years you can’t change.
How often should I review my wealth-building progress?
Quarterly is the sweet spot. More often leads to tinkering and emotional decisions. Less often and you might miss tax deadlines or drift off course. Pick one weekend every three months. Review asset allocation, rebalance if you’re more than 5% off target, check your automation is still running, and adjust your savings rate if your income changed. Then close the spreadsheet and live your life.
About the Creator
Kamel Saidani
Psychology graduate passionate about understanding human behavior, mindset, and personal growth. I share simple, practical insights to help people think deeper, grow stronger, and live more intentionally.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.