
Xiangpiaopiao’s 974,600-Yuan Quarter Shows Why Cup Coffee Won’t Save It
The instant milk tea company did not lose because young people stopped wanting sweet drinks. It lost the daily routine that once made a powder packet feel convenient.
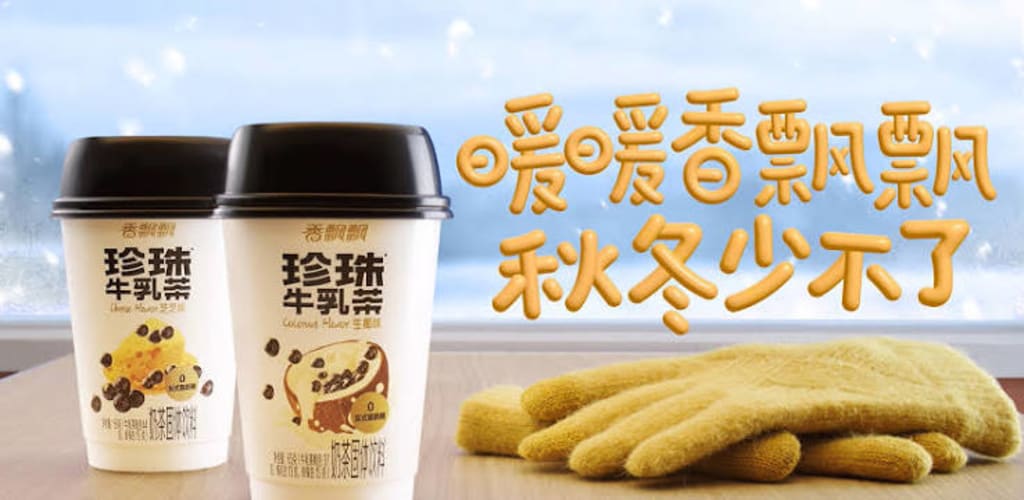
RMB 974,600. One quarter. Net profit attributable to shareholders.
Mixue Bingcheng earns more than that in half a day. That comparison matters more than the 88.09% decline. The decline is a symptom. The 974,600-yuan figure is the X-ray: a national brand that once strung its cups around the globe now earns less in a quarter than a bathroom in Hangzhou costs.
The numbers are results, not causes. The cause sits in the routine that instant milk tea once owned. The scenario that supported it has been replaced. Xiangpiaopiao is trying to patch that crack with cup-format coffee, but the coffee sits on the same old foundation.
Tearing a packet, finding hot water, stirring
In 2008, that was convenience. In 2026, it is work.
Young people did not stop wanting sweet drinks. Guming is growing. Mixue Bingcheng is expanding. Bottled sweet tea still sits on supermarket shelves. What disappeared is the space for a product that asks the consumer to finish the drink themselves.
Xiangpiaopiao’s instant milk tea was never selling the best milk tea. It sold a workaround. Tea shops were sparse. Delivery was immature. Convenience-store cold cases had not reached lower-tier markets. For three or four yuan and a kettle of hot water, a student could turn a dorm desk, an internet café table, or an office desk into a hot, sweet drink. The consumer supplied the last step.
That worked when the alternatives were fewer, farther, and more expensive. Walking two streets for a ten-yuan cup cost money and time. Tearing open a packet cost a hand. When a hand was cheaper than money and time, the packet won.
The definition of convenience has changed. By 2025, China had more than 415,000 freshly made tea shops. Mixue Bingcheng has nearly 60,000 stores in the six-yuan band. Guming has more than 14,000. Delivery brings a made-to-order, sweetness-adjusted cup to the office and the front door. Someone else does the work, and the price is close enough.
When someone else can do it for about the same cost, doing it yourself needs a reason beyond efficiency. Instant milk tea was never a hobby. It was a shortcut. Shortcuts move when a faster one appears.
In the first three quarters of 2025, Xiangpiaopiao’s instant beverage revenue fell about 26% year on year. The company said it had deliberately slowed shipments to keep channel shelf age healthy. That is plausible. It also points to the problem. A category in a demand expansion phase does not need to cut shipments to protect shelf age. Channel inventory becomes a burden when sell-through at the terminal is weak. Instant beverages carry a higher gross margin than ready-to-drink products, so the contraction hit overall margin and scale. Gross margin fell 1.7 percentage points in the first three quarters. Net margin slid to -5.3%.
Call it structural decline. The category’s native scenario has been replaced, and the sales base is shrinking with it.
Cup coffee: a familiar tool, not a new door
Xiangpiaopiao has launched cup-format instant coffee under Aifei, aimed at value, and Xiangka Bao, aimed at pour-over quality. Both are in online trial sales. The reasoning is easy to follow. Coffee is growing. Young people drink it. Cup-format brewing is Xiangpiaopiao’s old skill. Supply chains and channels can be reused.
The reasoning starts from the tool, not the need. Because cup-format brewing is close at hand, every new opportunity looks like something that can be poured into a cup.
Coffee convenience has already moved to lighter formats. Drip bags cost about RMB 2 to 3.5 per cup. Brewing takes a cup, hot water, and two minutes. The filter goes in the bin. Coffee liquid is lighter still: tear, pour, done. On the go, Luckin has more than 30,000 stores, Cotti has more than 18,000, and convenience-store cold cases stock ready-to-drink coffee. Nestlé holds nearly 60% of China’s ready-to-drink coffee market. Dongpeng Daka has nearly 14%.
Cup-format coffee lands in a bad spot. It is bulkier than a drip bag. A large paper cup takes space and adds logistics cost, while the drinking experience improves by almost nothing. It is more work than a store or a ready-to-drink can. You still need hot water, brewing, and washing up. The market has already set “no hands required” as the baseline.
The scattered praise for Xiangka Bao on social media makes the problem clearer. People mention the cup feels premium and works for camping. That is container value, not coffee value. One Xiaohongshu comment said the cup “beats many owner-operated coffee shops.” In that sentence, the cup is the subject. Coffee is the modifier.
The brand gets in the way
Consumers see the cup and think flavored sugar water. Changing the powder to coffee does not change that first reaction.
Xiangpiaopiao built its name on instant sweet milk tea. The first associations are flavoring, sugar, and cheap sweetness. A coffee launch cannot borrow positive equity from that name. It has to spend money suppressing the negative side.
The company has tested this in pop-up stores and experience stores. At its Hubin Yintai pop-up in Hangzhou, people queued for nearly two hours. The experience was staff brewing a tea bag in a pot in front of them. The cup and the brewing action send one signal. The brand sends another. A new sub-brand name does not close that gap by itself.
Xiangpiaopiao can make coffee. It probably cannot make coffee under the Xiangpiaopiao name. That name needs distance: a separate brand, separate visuals, separate channel logic, separate user communication. Those are not nice extras. They are the entry ticket.
1,703 distributors, 124 fewer
If the problem were only instant milk tea, coffee, health powders, and juices would look like sensible patches. The financial structure says otherwise.
In the first half of 2025, ready-to-drink beverages passed instant beverages for the first time, at 50.3% of revenue. Full-year growth for the segment was only 3.27%. Meco fruit tea grew 13.16%. Lanfong Yuen lemon tea dragged on results after a strategic adjustment. The “second curve” became the largest business without showing a second-curve growth rate.
Much of Meco’s growth came from snack-bulk retail. The company directly serves more than 40,000 snack terminals. That is channel dividend, not brand dividend. Channel dividend lasts until another brand pays more for the shelf. Brand mindshare lasts longer. Xiangpiaopiao’s mindshare still sits in the old winter-warming scene.
The main burden is the distributor network and the brand-communication model that once worked so well. At the end of 2025, the company had 1,703 distributors. It added 301 and lost 425, a net loss of 124. Distributor-channel revenue fell 15.01%. The old model ran on TV advertising, distributor reach into county stores and supermarket shelves, and consumers choosing at the shelf.
Attention is now fragmented. Channels are dispersed. Feedback comes weekly. A linear system that needs weeks to move a product from concept to shelf cannot keep pace. Full-year 2025 revenue fell 11%. Net profit attributable to shareholders fell 62.38%. It was the first double-digit decline in both since the 2017 listing.
A single SKU did not fail. An operating system did. The old channel was the skeleton. The old media was the voice. Both lost efficiency against the new consumption infrastructure.
Instant milk tea was the shortest path. Cup coffee is not.
Xiangpiaopiao has tried. It signed Teens in Times for Meco. It opened pop-ups. It launched an offline tea experience store in Hangzhou. It plans a ready-to-drink production base in Thailand. It has put AI into terminal monitoring and product R&D. Management knows the brand needs younger users and newer channels.
Tactics cannot replace a scenario reset.
A brand survives when it appears at the moment a need appears, in the scenario where that need happens, by the shortest path that scenario allows. Instant milk tea did that. Hot water and a school desk made the packet the shortest path. Cup coffee does not. Drip bags, coffee liquid, stores, and ready-to-drink cold cases are shorter.
The question for Xiangpiaopiao is no longer what else can go into a cup. The question is which specific, high-frequency moment in young people’s daily routes still lacks a solution that Xiangpiaopiao can provide and rivals have not occupied.
That answer probably will not look like an instant-brew cup. It may require a separate brand, separate channel logic, and separate user communication, built from zero to one around a concrete scene.
Without that, another cup-format SKU in a crowded race is an old ticket for a ship that has already left.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.