
The Banker Called Him “Dishonest.” Then He Bought Puma and Under Armour.
Frasers Group turned a Wall Street grudge, put options, and discount shelves into stakes in two struggling sportswear brands.
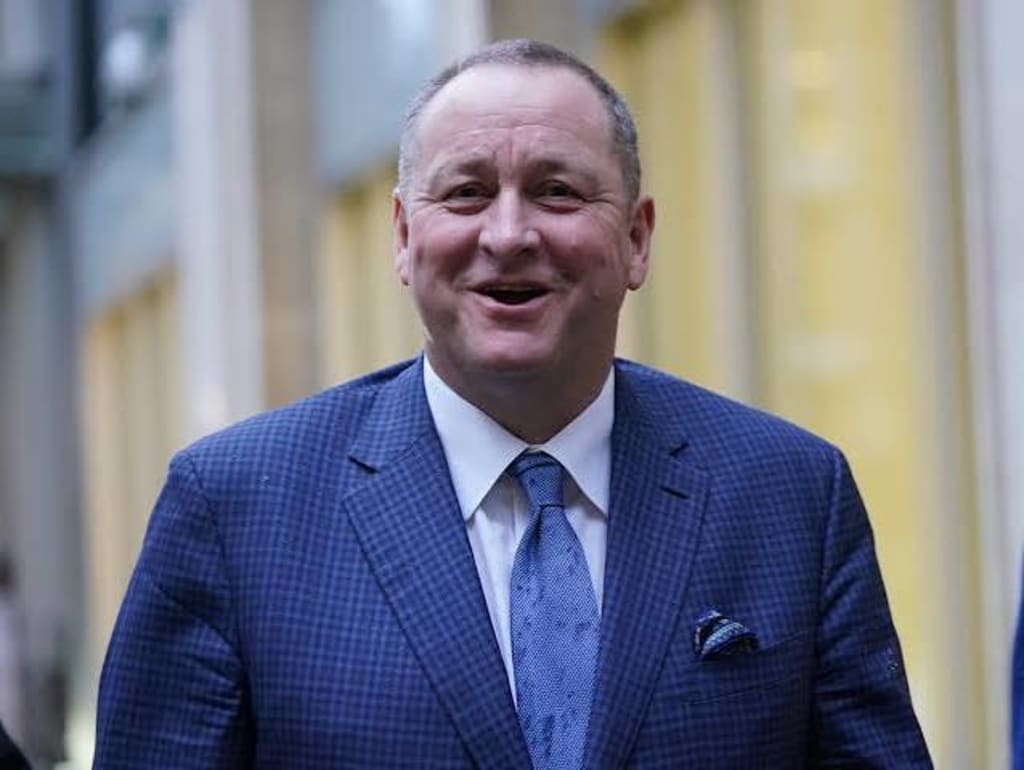
In 2021, Morgan Stanley told Frasers Group to post another $915 million in collateral for its Hugo Boss position. If it did not, the bank would force a liquidation.
Frasers did not pay. It sued.
Internal messages disclosed at trial show Simon Smith, co-head of global investment banking at Morgan Stanley, calling Mike Ashley “dishonest” and “a client we don’t want to do business with.” Another executive testified that Smith said Ashley liked to litigate. Morgan Stanley had already turned down Frasers’ application for an institutional trading account.
Frasers called the bank’s conduct “snobbery.” The two sides settled in May 2024. The court record stayed public.
A photo hangs in Frasers’ lobby. It shows the 1982 Maidenhead store, Puma shoeboxes stacked to the ceiling. Mike Ashley is not in the picture.
From Maidenhead to the London Stock Exchange
Mike Ashley did not go to university. In 1982 he borrowed £10,000 from his family and opened that store. The company listed in London in 2007. That year he also bought Newcastle United. In 2021 he sold the club for about £305 million to a consortium backed by Saudi Arabia’s sovereign wealth fund. He stepped back the next year and gave the CEO job to his son-in-law, Michael Murray.
Frasers’ latest fiscal year revenue was £5.326 billion. Its market value is about £3.76 billion. Institutions own roughly 21%. Large funds hold very little of a London-listed retailer worth more than £3 billion.
Sports Direct runs more than 500 UK stores and about 715 worldwide. Its online traffic hit 5.83 million in 2025, more than Nike and JD Sports. Its own brands include Everlast, Slazenger, Lonsdale, Karrimor and USA Pro.
In 2019 Sports Direct publicly attacked Nike and Adidas over how they chose retail partners. It asked UK and European competition regulators to investigate the two brands’ market power. Nike replied that Sports Direct’s distribution no longer fit its channel strategy.
Michael Murray became CEO and pushed the Elevation strategy. Sports Direct won “Tier 1” status with Nike, Adidas and Hugo Boss. Frasers’ fiscal 2025 annual report says relations with those brands “are the best they have ever been.”
Page 47 of the same report says UK sporting goods retail and premium businesses are both shrinking.
Puma: 37 days, 5.77%, 0.17%
After Anta announced its Puma deal, Frasers became Puma’s second-largest shareholder in 37 days.
Puma stock fell from €115.40 in November 2021 to €15.30 in November 2025. That is an 87% drop and the lowest price since 2016. Frasers bought in around €22.50 in March 2026, about 47% above the low. It paid about €200 million for 5.77%.
Only 0.17% of that stake was direct stock. The other 5.61% came from put option contracts covering about 8.5 million Puma shares. The options expired in April, September and December 2026.
Frasers used the same method with Burberry. All of its 7.42% voting stake came from selling puts. It held no Burberry stock directly.
Hugo Boss shows where the method can lead. Frasers started as a minority holder, kept buying, and launched a full takeover offer in June 2026. By August it held 47.89% and said it wanted more than 50%.
Michael Murray explained the test: “If it doesn’t fit the sports, premium or luxury positioning, or cannot add value to our ecosystem, we won’t buy it.”
Sports Direct is a major European retail channel for Puma. Puma is a major supplier to Sports Direct. In Frasers’ fiscal 2025 report, Puma ranked in the top three by profit contribution.
Reuters noted that Frasers has used minority stakes before to push for changes to strategy, or to get companies to sell its products or use its services.
Puma’s supervisory board, page 14
Puma CEO Arthur Hoeld is running a “brand restart.” 2025 was the reset year. 2026 is the transition year. The company plans to grow again in 2027. When he took over in 2025, he promised to clear inventory and stop heavy discounting at large retailers.
Page 14 of his supervisory board deck says the discount channel share should fall to 15% by 2027.
Frasers has a seat on that board. The minutes are not public. But Sports Direct’s autumn 2026 order sheet shows Puma purchases up 30% from the previous quarter.
As a retailer, Frasers wants Puma to keep shipping volume through Sports Direct. As a shareholder, Frasers gains if Puma raises brand premium. That requires less exposure in discount channels. Sports Direct is one of Puma’s biggest discount channels.
On a September 2026 investor call, Hoeld said: “Our negotiations with all channel partners are ongoing.” On page 12 of the transcript, analysts asked whether Puma’s supervisory board was split over channel strategy. He did not answer.
Anta’s announcement, Frasers’ timeline
Anta is Puma’s largest shareholder. Its acquisition announcement said it would “fully respect Puma’s management culture and Puma’s independent governance structure as a German listed company.” It also said it had no plan to make a takeover offer.
Frasers took a different route with Hugo Boss. It went from minority shareholder to 47.89% in under two years.
Anta works through the supervisory board. Frasers builds positions with options and presses as a channel partner. When Puma’s board debates channel strategy, Frasers’ position touches its own order sheet.
Two things will decide the result. Can Anta, as largest shareholder, build enough influence on the supervisory board? Can Frasers turn its options into enough influence over Puma’s decisions?
A £3 billion loan, £1.2 billion of debt
In July 2025 Frasers signed a new bank facility worth £3 billion. It replaced a £1.65 billion agreement. An accordion clause lets it borrow another £500 million with bank consent, up to £3.5 billion.
The latest annual report shows revenue up, retail profit up, net debt up sharply, bank interest up, and pre-tax profit down after one-off items. UK sporting goods retail and premium businesses are both shrinking.
Michael Murray wrote that since the second half and into fiscal 2027 the company has felt “a difficult trading environment, weak consumer confidence and industry-wide excess inventory.” Frasers declined to give 2027 profit guidance because takeover offers for Hugo Boss and Accent Group are still open.
Page 68 of the annual report shows the annual interest on that £1.2 billion of debt.
Bloomberg estimates Frasers owns about £2 billion of retail property. Murray said the portfolio could grow tenfold in a decade. From late 2025 into early 2026, Frasers bought several UK shopping centres and outlet malls.
Under Armour, 8.8%
In August 2026 Under Armour reported first-quarter fiscal 2027 results for the period ending June 30. Revenue fell 3% to $1.1 billion. North America fell 9% to $610 million. Footwear fell 8% to $245 million. The company cut its full-year revenue outlook from “a slight decline” to “a mid-single-digit decline.”
As of August 31, short interest in Under Armour Class A shares was 36.98%.
On October 1 Frasers filed a Schedule 13G with the U.S. Securities and Exchange Commission. It disclosed 16,576,500 Class A shares, about 8.8% of the class, worth about $80.1 million at the time.
Bloomberg described the move as expanding Frasers’ bets on “distressed sports brands.”
Under Armour stock sits near a 16-year low. Puma’s valuation is being repriced after Anta’s entry. Frasers has Sports Direct’s shelves and retail cash flow.
The Morgan Stanley executive in the court record later left the firm. In Frasers’ new Schedule 13G, Under Armour appears on the added line.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.