
Infrastructure Acceleration vs. Debt Leverage: Gauging Dycom Industries' (DY) Ammunition
Growth Momentum in the Midst of Aggressive Expansion
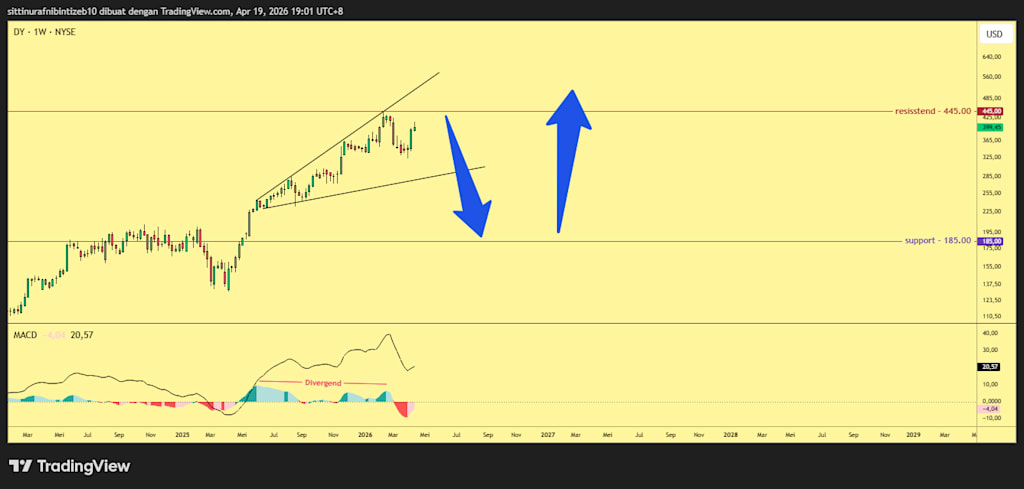
Dycom Industries (DY) is currently in a phase of robust growth momentum, fueled by solid operational efficiency and tangible business expansion. The core investment thesis for this stock lies in its ability to post aggressive revenue growth, with estimates reaching 32.95% for the April 2026 quarter and 28.87% for the following quarter. High investor confidence is further evidenced by institutional ownership dominating at 94.20%, providing a sturdy foundation for long-term price action.
However, this growth strategy is not without its costs, as the company recently executed massive strategic acquisitions that have fundamentally altered its balance sheet. While cash and cash equivalents surged to $709.1 million, this spike was largely driven by new debt issuance. Investors should view DY as a growth vehicle taking a "high-stakes bet" through leverage to capture a broader share of the booming infrastructure market.
Catalysts: A Track Record of "Earnings Beats" and Market Dominance
The primary "weapon" for bullish shareholders is DY's consistent record of exceeding analyst expectations, having delivered an earnings beat in each of the last four quarters. Beyond simply winning, the company’s Surprise % has shown a strengthening trend, reaching 14.03% in January 2026, which suggests that management is far more proficient at operational efficiency than market models predict. Furthermore, DY’s projected growth of 49.28% this quarter vastly outpaces the S&P 500’s estimate of 12.52%.
From an operational standpoint, liquidity has improved significantly with working capital now sitting at $1.75 billion, granting the flexibility to fund large-scale infrastructure projects without short-term cash flow constraints. A sharp jump in Operating Cash Flow (OCF) to $418.9 million in the latest quarter proves that DY's core business is generating substantial real-world cash, rather than just paper profits. If this positive trajectory persists, the potential for a short squeeze remains high, given the 7.99% short interest of the float.
Valuation: A New Standard in the Era of Re-rating
Regarding valuation, the market appears to be undergoing a "re-rating" of DY shares, where P/E standards that were once considered fair in the 20s have shifted to the 30-40 range. This is reflected in the gap between the 41.78 Trailing P/E and a more attractive 31.15 Forward P/E, indicating strong expectations for future earnings growth. With a stable EPS Compound Annual Growth Rate (CAGR) of approximately 19-20% projected through 2028, current prices are supported by a rational growth framework for institutional investors.
While Price/Sales and EV/Revenue multipliers have risen significantly, such appreciation typically occurs when a company is perceived as dominating a booming sector. The 2027 EPS estimate of 14.26 now serves as a solid "anchor point" for analysts determining fair value. However, investors must note that DY pays no dividends (0.00% payout ratio), meaning the investment's appeal relies entirely on aggressive EPS growth and capital appreciation.
Risks: Debt Surges and Peak Momentum
The most significant risk looming over DY is the spike in total debt, which has nearly tripled to $2.99 billion. This increased debt burden has already begun to impact the bottom line, as seen in interest expenses doubling in the January 2026 quarter. Additionally, due to massive acquisitions, the company's Net Tangible Assets have turned negative to -$510.2 million because of the high proportion of Goodwill, creating a risk of future impairments that could hit net income hard.
On the market sentiment front, there are signs of growth normalization, with sales growth estimates for 2028 projected to drop sharply to 9.77%. Recent downward revisions by analysts over the last seven days for the current quarter also provide a "caution" signal regarding short-term operational costs. If DY fails to maintain its tradition of double-digit earnings surprises, its premium valuation is highly vulnerable to a sharp correction as the market has grown accustomed to high performance.
Conclusion: BUY (With Close Monitoring of Leverage)
Based on the available data, the recommendation for Dycom Industries (DY) is BUY. This decision is supported by management's exceptional track record of beating analyst targets and a robust Free Cash Flow (FCF) that jumped to $364.6 million. The overwhelming institutional confidence and strong fundamental demand in the infrastructure market suggest that the company’s operational health remains vibrant despite its aggressive expansion.
However, this "Buy" status requires vigilant oversight of the company’s new debt levels and the integration of its acquired business units. Investors should watch for any consecutive declines in nominal EPS or signs that the Return on Invested Capital (ROIC) is failing to offset rising interest costs. As long as the long-term earnings estimate anchor of 14.26 for 2027 holds steady, the bullish momentum is expected to prevail.
Keep in mind that if you are seeking regular income, this stock is not for you, as its strategy is entirely focused on total reinvestment to drive future value growth.
About the Creator
Lena
Financial Analyst & Content Creator 7 Yrs Exp. Merging Fundamental Research PEG/Value with Advanced Technical Analysis. Specialist in Equities & Crypto narratives that turn complex data into high stakes Alpha.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.