
He Had Two Offers: One From a Quant Fund, One From a Stock Picker
Why finance graduates keep choosing the job with a number, and what that choice leaves behind
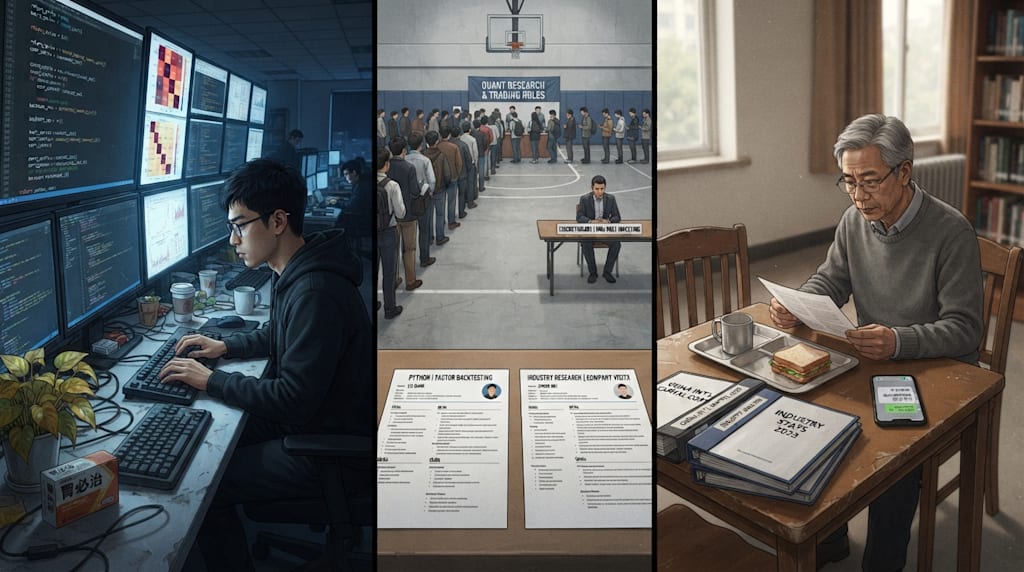
The job fair took over the gymnasium. The quant private fund’s booth stretched to the door. The discretionary long-only booth had one empty table. Chen Mo stood between the two lines, holding two résumés. One read “Python, machine learning, factor backtesting.” The other read “industry research, company visits, in-depth reports.”
He went to quant first. The interviewer did not ask, “How do you see the market?” He asked, “How many minutes do you need for this problem?” Chen Mo wrote a dynamic programming solution on paper. The interviewer glanced at it. “Go back and wait for the notice.” At ten that night, the offer arrived. Monthly salary: 28,000 yuan. Year-end bonus: depends on the strategy.
The next day he went to the discretionary side. The mentor’s surname was Zhou. He was over fifty, wore an old sweater, and kept annual reports piled on his desk. Professor Zhou flipped through the résumé. “Have you read Poor Charlie’s Almanack?” Chen Mo said he had. Professor Zhou asked, “Then tell me. How do you judge whether a company will still be around in ten years?” Chen Mo talked about industry space, moat, management. Professor Zhou did not respond. He pushed an annual report across the desk. “Read this first. When you finish, write three thousand words.”
Chen Mo read forty pages. He remembered the chairman’s photo. That night he WeChatted Professor Zhou: “I’ve finished.” Professor Zhou replied: “No rush. Read it again.”
Quant urged him to join. HR said, “We’re short-staffed. You’ll start with the factor group.” Chen Mo asked, “Can I do strategy?” HR smiled. “Run data first. Once you understand that, we’ll talk.”
He went to quant.
His desk sat on a large open-plan floor. Two hundred researchers. Screens lit late into the night. His first task was cleaning data. Every day, nine in the morning to ten at night, aligning financial statement fields and deleting outliers. In the third week, he got a momentum factor to run. Sharpe 2.1. He stared at the screen. He wanted to screenshot it and post it to Moments. He deleted it. A box of stomach medicine sat beside him. Dust had settled on the keyboard cover.
Han Ce, a senior colleague, came over. “Not bad. Don’t celebrate too early. It might stop working next week.” Chen Mo asked, “Then what do we do?” Han Ce said, “Switch factors, or lower the frequency. No one knows which is right.” Chen Mo said nothing. Han Ce patted him. “At least you have a number. On the discretionary side, you don’t even have a number.”
Chen Mo thought of Professor Zhou. He WeChatted him: “Professor, I joined a quant firm.” Professor Zhou replied: “Good. The market needs different people.” Chen Mo looked at the sentence. He did not reply.
Three months later, Chen Mo returned to school for paperwork. He ran into Professor Zhou in the cafeteria. Professor Zhou carried his tray and sat across from him. “I read your report. It was well written.” Chen Mo said, “Then why couldn’t it go into the portfolio?” Professor Zhou picked up a bite of greens. “Because the portfolio already has ten stocks. This one, I don’t understand.” Chen Mo said, “I can explain.” Professor Zhou said, “Explaining takes time. The fundraising side is pushing. I don’t have time.”
Chen Mo lowered his head and ate. Professor Zhou added, “You’re suited to discretionary. You have patience.” Chen Mo looked up. Professor Zhou took a call, voice low. “We’ll talk about fundraising later. It’s hard to launch now.” He hung up and stood. “I’m off. Do well.”
Chen Mo watched Professor Zhou’s back. He took out his phone and typed in WeChat: “Professor, I want to do discretionary with you.” Before he sent it, quant HR messaged: “Salary adjustment next month. You’re promoted to P2.” Chen Mo deleted the line. He put the phone face down on the table.
Half a year into the job, Chen Mo began managing a small portfolio on his own. Size: 30 million. Every day he ran factors. He adjusted weights. He did attribution. The curve looked good. Drawdowns were controlled. When distribution channels came for due diligence, he talked about IC, IR, turnover. The channel said, “Easy to sell.” Chen Mo nodded.
When the size rose to 300 million, the problem came. At the morning meeting, the PM said, “The momentum factor is crowded. Think about it, everyone. Do we attack or defend next?” No one spoke. Chen Mo wanted to say, “It depends on the market environment.” He could not get it out. He knew that sentence amounted to nothing. The PM added, “Homogenization is too severe. Who can find what isn’t priced?” Still no one spoke. Chen Mo looked at the factor correlation matrix on the screen. He thought of the annual reports on Professor Zhou’s desk.
That night, he worked until two. He opened Professor Zhou’s Moments. The latest post was from half a year ago: a photo out an office window, captioned, “Another year.” Chen Mo turned off his phone. He opened Python and started writing a new factor. The code ran. The screen lit up. He picked up the stomach medicine. Empty. He threw the box into the trash and kept adjusting parameters.
The next day, he sent Professor Zhou a WeChat message: “Professor, I might still be suited to quant.” Professor Zhou replied: “Understood. The market needs different people.” Chen Mo looked at the sentence. He put the phone beside the keyboard. He opened the backtest results. Sharpe 1.8. He sighed and created another file.
The pothos in the corner of his desk had yellow leaves. He had forgotten to water it.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.