
The Anti-Budget: Why Tracking Every Penny Is Making You Broke
How micromanaging your coffee purchases is distracting you from the one number that actually builds wealth.
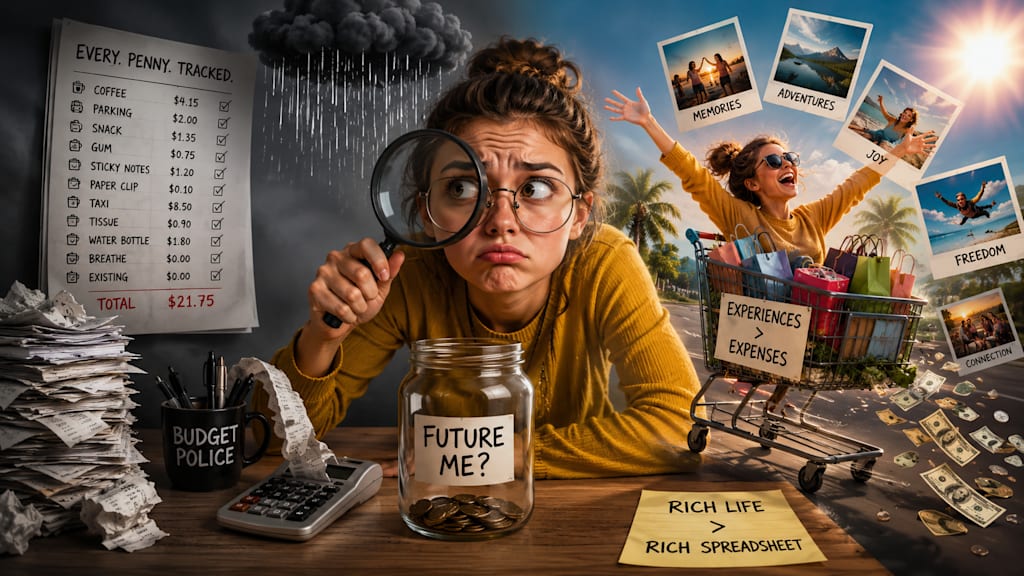
I used to track every dollar I spent. I logged my coffee, my gas, my subscriptions, and even the $1.50 I tipped the valet. I thought this was the path to wealth. I was wrong. The more I tracked, the more I spent. My anxiety went up while my savings rate went down. This is not a glitch. It is a feature of how human brains work.
Traditional budgeting relies on willpower and constant monitoring. It assumes we are rational actors who will stick to a plan when faced with temptation. We are not. We are emotional creatures who get tired, stressed, and easily distracted. When a budget feels like a cage, we break out of it. We spend the $5 on lunch because the spreadsheet says we have $20 left in "Food," but the mental effort of checking the app feels like work.
Anti-budgeting flips the script. It removes the tracking. It removes the guilt. It removes the constant mental math. Instead of limiting what you can buy, it automates what you save. You pay your future self first, and spend whatever is left without a second thought. This method leverages behavioral psychology to make saving the default path, not the hard choice.
The Psychology of Budgeting Failure
Why do 92% of resolutions fail? Because they rely on active decision-making. Every time you check your budget, you face a choice. Do I buy this? Can I afford this? Should I track this? These micro-decisions drain your cognitive energy. By 6 PM, your brain is tired. You want comfort, not another spreadsheet.
This phenomenon is called decision fatigue. The more choices you make during the day, the worse your decisions become. A traditional budget forces you to make financial choices dozens of times a day. An anti-budget removes the choice entirely.
How Traditional Budgeting and Anti-Budgeting Compare
Traditional Budgeting
Requires constant tracking and willpower
Focuses on limiting spending
Creates guilt when limits are breached
High cognitive load and mental energy
Reactive: You fix mistakes after they happen
Anti-Budgeting
Requires one-time setup and automation
Focuses on prioritizing saving
Creates freedom within remaining funds
Low cognitive load and mental energy
Proactive: You prevent mistakes before they happen
The emotional toll of tracking is real. Most people feel like they are failing their budget the moment they overspend in one category. This triggers a "what the hell" effect. If I blow my lunch budget, I might as well blow my dinner budget too. The entire system collapses under the weight of perfectionism.
Anti-budgeting accepts that life is messy. It acknowledges that you will have good weeks and bad weeks. It does not demand perfection. It demands consistency in the one thing that matters: getting money out of your checking account and into your savings before you touch it.
The Mechanics of Paying Yourself First
The core principle of anti-budgeting is simple. You set up automatic transfers for your savings and investments the day you get paid. This happens before you pay a single bill or buy a single coffee. The money is gone from your checking account. It is safe. It is working for you.
The amount you save should be fixed or a percentage of your income. You do not negotiate with this transfer. It is a bill you pay to your future self. If you make $5,000 a month and save 20%, $1,000 leaves your account immediately. You live on the remaining $4,000.
How you spend that $4,000 is up to you. Do you want to eat out three times a week? Go ahead. Do you want to buy a new gadget? Do it. Do you want to save the extra money? That is your choice now. The pressure is off. You have already secured your future.
This method works because it changes your relationship with money from one of restriction to one of abundance. You are not asking, "Can I afford this?" You are asking, "Do I want this enough to use my leftover money?" The answer is often clearer when you are not fighting a budget line item.
Why Automation Beats Willpower
Willpower is a finite resource. It depletes throughout the day as you resist temptations, solve problems, and make decisions. Relying on willpower to save money is like trying to run a marathon on an empty stomach. You might start strong, but you will crash.
Automation removes the need for willpower. When you set up an automatic transfer, you are not making a decision every month. You are executing a command. The system runs in the background. You do not have to remember, feel guilty, or calculate.
Consider the friction of tracking. To make a traditional budget work, you must:
Open your banking app
Categorize the transaction
Check your remaining balance for that category
Decide if you can afford the next purchase
Repeat this for every single transaction
Now compare that to the friction of an anti-budget:
Set up the automatic transfer once
Spend your money
Forget about it
The difference in effort is staggering. The anti-budget reduces the friction to near zero. It aligns with how our brains naturally prefer to operate. We prefer the path of least resistance. If the path of least resistance is saving money automatically, we save. If the path of least resistance is spending, we spend.
Feature Comparison: Manual Tracking vs. Automated Anti-Budget
Time Required
Manual: 30+ minutes per week
Automated: 30 minutes total setup
Mental Energy
Manual: High (constant decision fatigue)
Automated: Low (one-time decision)
Error Rate
Manual: High (missed entries, wrong categories)
Automated: Zero (system does the work)
Emotional Impact
Manual: Stress and guilt
Automated: Relief and freedom
Scalability
Manual: Breaks down as income/spending grows
Automated: Scales effortlessly with income
The Freedom of the "Leftover" Mindset
The most powerful aspect of anti-budgeting is the concept of the leftover. In a traditional budget, you allocate every dollar to a job. Every penny has a label. This feels organised, but it feels like a prison. You are the warden, and your money is the inmate.
In an anti-budget, you allocate money to your future and your bills first. Everything else is the leftover. That leftover is yours to do with as you please. There are no labels. No categories. No guilt.
This freedom changes your spending behavior. When you know your savings are safe, you stop spending on things you don't need. You stop trying to "stretch" your budget to buy things you don't want. You start spending on things that actually bring you joy because you are not afraid of breaking the rules.
You might find that you save more naturally. Without the pressure of a strict limit, you might realise you don't need to spend $200 on groceries. The extra money just stays in your checking account. At the end of the month, you can move it to savings. It is a bonus, not a requirement.
This approach also handles irregular income much better. If you are a freelancer or work on commission, a fixed budget is a nightmare. Your income fluctuates, but your expenses might not. With an anti-budget, you set a fixed dollar amount to save every month, regardless of income. If you make more, you save more. If you make less, you save the same amount and tighten your belt on the leftover.
Implementing the System Without Tracking
Setting up an anti-budget is straightforward, but it requires a shift in mindset. You must be willing to stop tracking. This is the hardest part for many people. They feel naked without a spreadsheet. They feel like they are losing control.
Here is how to start.
First, calculate your bare minimum monthly expenses. This includes rent, utilities, food, transportation, and debt payments. Do not include entertainment or savings. Just the essentials.
Next, determine your savings target. This could be a percentage of your income or a fixed amount. Make sure this amount is realistic but challenging. You want to save enough to feel progress, but not so much that you can't pay your bills.
Subtract your savings target and your bare minimum expenses from your income. The result is your spending allowance. This is the amount you have available for everything else.
Set up automatic transfers for your savings target. Schedule them to happen on payday. Set up automatic bill pay for your essential expenses. Now, your checking account holds only your spending allowance.
Stop tracking. Do not open your budgeting app. Do not categorize transactions. Do not check your balance against a limit. Spend your spending allowance freely. If you run out, you stop spending. If you have money left over, you move it to savings or a fun fund.
Common Pitfalls and How to Avoid Them
Even with the best system, things can go wrong. The biggest pitfall is the temptation to check in. You might feel the urge to see how much you have spent. This is a trap. Checking in invites the old mindset of restriction back into your head.
Another pitfall is overestimating your spending allowance. If you set your savings too low, you might find yourself with a lot of leftover money. This is good, but it can lead to lifestyle creep. You might start spending more just because you can. To avoid this, review your savings rate every six months. Increase it as your income grows.
You might also face pressure from others. Friends might ask why you aren't tracking your spending. Explain that you are using a different method. You are focusing on saving first and spending freely with the rest. You do not need to justify your freedom to anyone.
What if you overspend? In a traditional budget, this is a failure. In an anti-budget, it is just data. If you run out of money before the next paycheck, you stop spending. You do not use credit to bridge the gap unless it is an emergency. You learn to live within your means without the guilt.
Scenario Reactions: Traditional vs. Anti-Budget
Overspending on Dining
Traditional: Feel guilty, cut back on other categories
Anti-Budget: Stop eating out for the rest of the month
Unexpected Expense
Traditional: Panic, break the budget, feel like a failure
Anti-Budget: Use leftover funds, or reduce non-essential spending
Windfall (Bonus)
Traditional: Add to budget categories, feel restricted
Anti-Budget: Save a portion, spend the rest freely
Month-End Surplus
Traditional: "Did I do enough?"
Anti-Budget: "How much more can I save?"
The Long-Term Vision of Financial Freedom
The goal of anti-budgeting is not just to save money. It is to build a life where money is not a source of stress. It is to reach a point where your financial decisions are automatic and your mind is free.
When you stop fighting your budget, you start living your life. You focus on your career, your relationships, and your passions. You do not waste energy on financial math. You trust the system. You trust yourself.
This method works because it respects human nature. It acknowledges that we are not robots. We are emotional, complex beings who need flexibility. It gives us the structure we need without the chains of restriction.
Start small. Pick a savings amount that feels safe. Set up the automation. Let go of the tracking. Watch what happens. You might be surprised by how much you save and how much happier you feel.
The future of personal finance is not about more apps or more data. It is about less friction and more freedom. It is about designing a system that works for you, not against you.
Your next paycheck is coming. Will you spend it on restrictions, or will you spend it on freedom?
Disclaimer: Content is for informational purposes only and does not constitute professional advice.
About the Creator
TheFabledScribe
Expert in budgeting and frugal living. Using proven strategies to build financial resilience. Trustworthy guidance for average people seeking results.
I will NEVER put my content behind a paywall..
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.