
I Read the Six Municipal Debt Cases. Here’s What They Mean for Your City.
The report named mayors, pensions, and paper debt. The fallout will land in every budget office, fire station, and water pipe in America.
Old Debt, Current Responsibility: How Local Governments Spend After Six Municipal Debt Cases
On September 11, 2026, the Federal Department of the Treasury and the Government Accountability Office released six case studies on municipal debt accountability. The cases involved more than $68 billion. They covered a state official, a mayor, a county board member, and a public utilities authority director. The report did not stop at “improper borrowing.” It named “the previous administration’s debt is not my responsibility,” “restructuring in name only,” and “false execution” as grounds for accountability.
The effect on local fiscal management will show up in budget drafts, city council hearings, and union negotiations, not on the day the report lands.
I. “The Previous Pension, Why Should I Close Fire Stations?”
The first case is a Midwestern mayor. The report quotes him: “The pension was owed by previous councils. Why should I close fire stations?” During his term, he ignored the pension gap. He repeated versions of that line in union halls and city council corridors. The city’s pension funding ratio fell from 45% to 20%. The state financial oversight board intervened. Three fire stations closed. Streetlight repair schedules stretched from two weeks to six months. The mayor was recalled. The state auditor’s office referred the case to federal prosecutors.
Mayors in Rust Belt cities have said things like this before. It used to sound like a resigned joke, or a complaint about inheriting a mess. The report treats it as a wrongful statement. It places the quote next to the city’s last-place pension funding ratio. Debt restructuring now belongs to the current officeholder, not to the predecessor’s spreadsheet.
One passage in the report is worth reading closely:
Whether the debt was formed at what time, or originated under which officeholder, if the current official passively performs duties, delays, or fails to actively advance debt restructuring and risk control, that is ineffective implementation of the state fiscal recovery plan and dereliction of duty, and accountability must follow according to rules and discipline.
That passage puts old accounts and current officeholders in the same frame. Some mayors once treated pension gaps and off-balance-sheet liabilities as someone else’s problem. They put energy into new convention centers, stadiums, and commercial districts. That attitude can now trigger accountability.
II. $3.1 Billion and $1.8 Billion: New Debt and Restructuring in Name Only, Both Ends Closed
The second case shows how new off-balance-sheet debt gets created. A county industrial development authority was bringing in a logistics center. It improperly decided that the public utilities authority would advance an infrastructure subsidy to the company for the county. The move added $3.1 billion in off-balance-sheet debt. Corporate support funds should have come through the county budget. By routing the payment through the public utilities authority, the county bypassed budget constraints and a voter referendum.
Restructuring in name only appears with similar precision. One city reported $182 million in restructuring funds and repaid $42 million. One county used bond funds and interfund transfers for offset accounting, producing $1 billion in restructuring that never happened. One city diverted $1.8 billion in restructuring funds to daily operations, including police overtime and winter road salt. In each case, the debt disappeared on paper. The risk stayed.
The report calls restructuring in name only “false execution” and “flexible implementation” of the state fiscal recovery plan. It says altered data, accounting maneuvers, and paper debt elimination conceal real risk and “seriously mislead macro decision-making.”
That phrase lifts the consequences from local offices to the federal level. If restructuring data sent upward contains water, federal risk judgments go off. Interest rate policy, transfer payments, and regional support can follow the error. Restructuring in name only is not a paperwork problem. It distorts the information macro decisions rest on.
III. Spending Logic: From “What Can We Do” to “What Should We Do and What Can We Afford”
The report uses another phrase: development impulse.
New off-balance-sheet debt mostly stems from local development impulse and election-cycle pressure.
“Impulse” is rare in fiscal management. It means that from an economic standpoint, some projects in some places should never have started. Not later. Not smaller. Never. For decades, local governments used investment to drive growth: roads, industrial parks, new towns, stadiums. When money ran short, they borrowed through public utilities authorities, economic development corporations, tax increment financing, and public-private partnerships. The borrowed money became off-balance-sheet debt. The projects may not have had enough revenue, population, or industry to support them.
The 2025 OECD urban policy report said many Western cities are moving from large-scale expansion to stock upgrading and efficiency. In fiscal terms, spending logic has to change.
The old question was: What can we do? The new question is: What should we do, and what can we afford? Most local spending will shift to a stock logic. Maintain necessary infrastructure. Fund basic public services. Cut non-essential, non-rigid, non-priority spending.
One city’s 2026 budget review evaluated all 534 city-level projects. It cut 72 continuing projects worth $430 million. Other budget documents put police, fire, garbage collection, schools, and public health first. In some places, basic service budgets exceed 50% of general fund spending. The cuts land on low-efficiency infrastructure, empty community schools, and underused gymnasiums and convention centers.
Property and sales taxes are pushing the same shift. In 2025, state and local tax revenue growth slowed. Property tax caps and Proposition 13-style limits kept many cities from raising rates to match spending needs. Some Rust Belt cities have lost more than 30% of their tax base since the 2021 peak. Property taxes once funded local infrastructure. That source is narrowing. State transfers and federal grants are adjusting too. Local revenue shortfalls will persist.
With revenue narrowing, spending cannot continue at the old pace. Local government-led capital spending will stay in adjustment for several years. The contraction now visible may not be the end.
IV. Fiscal Discipline: Find One, Investigate One, Hold One Accountable
The Federal Department of the Treasury and the Government Accountability Office released this report together. Municipal debt is a fiscal discipline issue. It is also a political discipline and organizational discipline issue.
The report states:
Next, the Federal Department of the Treasury and the Government Accountability Office will continue to strengthen investigation and handling of municipal debt problems, pursue accountability, and for illegal and irregular acts such as new off-balance-sheet debt and restructuring in name only, find one, investigate one, and hold one accountable.
“Find one, investigate one, hold one accountable” is not new. In the municipal debt field, with six cases, it carries more weight. The cases cover state, city, county, and public utilities authority levels. The accountability chain runs from decision to execution. Some places once assumed that debt borrowed in an earlier term could be restructured slowly. Others assumed that if the paper numbers looked good, the method did not matter. This report closes both paths.
After the 2026 election cycle began, fiscal accountability merged with campaign pressure. The report calls for “consolidating and expanding the results of fiscal responsibility education.” Officials are judged on economic growth and on debt control and risk prevention. Pension funding ratios, changes in off-balance-sheet debt, and public utilities authority transition progress will enter evaluation tables.
V. Regional Divergence: Investment Is Contracting in Oversight Areas
Municipal debt restructuring pressure is worsening regional divergence. In the first half of 2026, capital spending in fiscal oversight areas grew by an average of -13.06%. Other areas grew by -5.22%. The gap was 7.84 percentage points. Average GDP growth in fiscal oversight areas was 3.89%, compared with 4.52% elsewhere.
Debt restructuring policy is compressing investment by design. Areas under heavy debt pressure reduce new projects, cut spending, and unlock assets to lower risk. They pay in slower growth, fewer jobs, and shrinking public services. Some areas that have exited the fiscal oversight list, such as certain Midwestern states, have raised capital spending growth targets. Investment and financing still need time to improve. A list cannot rebuild market confidence in regional credit by itself. Moody’s, S&P, and Fitch will keep watching pension reform and debt restructuring.
VI. How Localities Respond: Zero-Based Budgeting, Unlocking Stock Assets, Preventing Digital Debt
With incremental revenue constrained and restructuring responsibility increased, local fiscal management is changing in four ways.
Zero-based budgeting. Budget preparation used to follow “base plus growth.” Projects continued year after year once listed. Some places now rank projects by urgency and cut unreasonable continuing projects. One city cut 72 projects and $430 million.
Unlocking stock assets. One county deepened “finance plus state-owned assets” reform. It created a state-owned asset operations management company and unlocked inefficient idle assets to raise $660 million for municipal debt repayment. REITs and other asset securitization tools are drawing attention. Parking lots, water systems, airports, and old industrial land are on the negotiating table.
Preventing “digital debt.” The three restructuring-in-name-only cases show that under pressure, some places changed numbers instead of repaying. Accountability alone will not stop it. Restructuring results need a more scientific evaluation mechanism. A decline in book debt does not mean risk has disappeared. Cross-verification should confirm whether funds were repaid, creditors confirmed, and the public utilities authority actually exited.
Protecting basic services. Restructuring requires cuts, but basic livelihoods cannot collapse. Many places prioritize police, fire, garbage collection, schools, and public health. They cut non-rigid and non-priority spending. Lead pipe replacement, teacher salaries, and medical assistance move up in budget rankings. City exhibition hall upgrades, new district landscape projects, and underused cultural and sports centers move down.
VII. 1:20 A.M. in a Budget Office
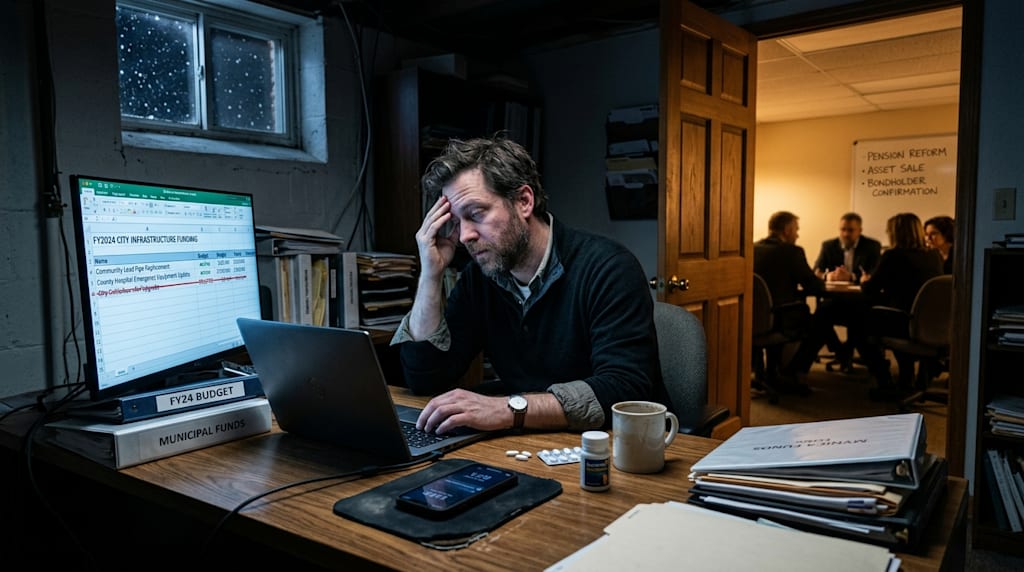
At 1:20 a.m., in the basement budget office of a city hall, an analyst highlights “City Exhibition Hall Upgrade” and deletes it. The next line, “Community Lead Pipe Replacement,” stays. Below that, “New District Smart Streetlight Phase II,” deleted. “County Hospital Emergency Equipment Update,” stays.
A bottle of ibuprofen sits on the desk. Two pills lie next to the mouse pad. The phone lights up: notice of tomorrow morning’s city council hearing. He replies “Received,” saves the spreadsheet, and names the file “FY2027_budget_v9.xlsx.”
Snow falls outside. He turns off the monitor and picks up his coat. At the end of the hallway, the conference room light is still on. Someone inside is reading a debt restructuring plan. The voice is low. The numbers are unclear. A few words carry: “pension reform,” “asset sale,” “bondholder confirmation.”
He walks into the elevator and presses the first floor. Before the doors close, he checks the time on his phone: 1:47 a.m. Tomorrow he will keep revising.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.