product review
Product reviews for those who yearn to learn; a breakdown of the best back-to-school supplies, test prep manuals, online study tools and other resources for students and teachers alike.
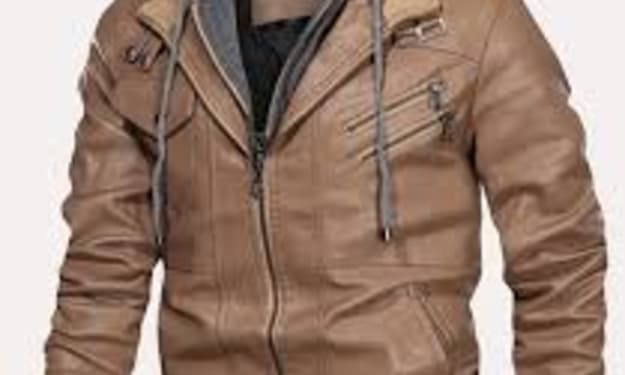
The Allure of Hooded Leather Jackets:
In the ever-evolving world of fashion, certain pieces manage to stand the test of time, transcending trends and seasons. One such iconic garment is the hooded leather jacket. Combining rugged durability with sleek sophistication, hooded leather jackets have become a beloved staple for fashion enthusiasts and practical dressers alike. This blog delves into the rich history, versatile styling options, and enduring appeal of these remarkable jackets.
By Amna Theleatherjacket2 years ago in Education
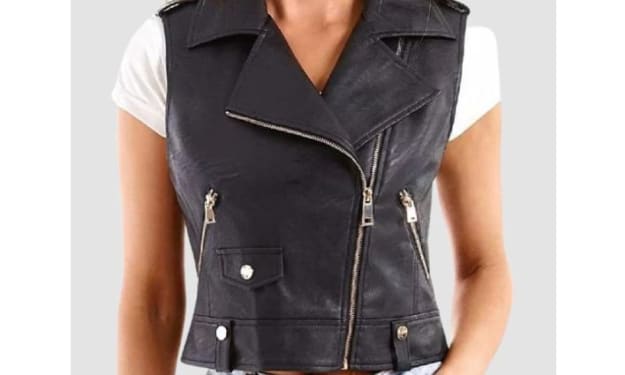
Unveiling the Timeless Allure of Women’s Leather Vests
The leather vest traces its origins back to practical beginnings, often associated with cowboys and bikers who valued its durability and functionality. Over time, this humble garment evolved into a fashion statement, gracing runways and red carpets. From the rebellious vibes of the 1970s punk scene to modern boho-chic ensembles, the leather vest has proven its adaptability and relevance in every era.
By Amna Theleatherjacket2 years ago in Education
How to make a laptop mockup free
Creating a laptop mockup for free is a fantastic way to showcase your designs, websites, apps, or digital products in a professional and visually appealing manner. Whether you’re a graphic designer, a marketer, or a small business owner, laptop mockups help add context and professionalism to your work. Here is a detailed step-by-step guide to making a laptop mockup without spending a dime.
By ladali official2 years ago in Education
Unlocking Financial Freedom: Your Expedition to Building Wealth and Independence
Envision you're on an expedition. You have a guide in your grasp, denoting the way to a hidden money box loaded up with gold. Each step on this guide represents a pivotal piece of establishing a strong financial foundation. Along the way, you discover hints and tools like picking a lucrative job, starting a side gig, or investing wisely, all of which will help you reach your fortune faster. Just like in any expedition, there are challenges and distractions, but with the right strategy and persistence, the treasure is yours to claim. And remember, this fortune isn't just about money—it's about independence from the rat race and the true peace of mind that comes with it. So here's a quick outline of what we will cover in the present video, acting as your fortune map: 1. **The Wealth Grid and How to Generate Financial Momentum** 2. **The Way to Expand Your Income and Save More** 3. **How to Achieve a High Growth Rate on Your Savings** 4. **How to Generate Investment Income Forever** 5. **Building a Solid Financial Foundation: Models** 6. **Five Strategies to Build Financial Momentum Faster** --- ### The Wealth Grid: Your Financial GPS Consider the Wealth Grid as the map's legend, helping you understand how much to save and the returns you need to hit your wealth goals. Here's the deal: the Wealth Grid lays out exactly how much you need to save each month and the rate of return you need to hit your wealth targets. **Warning**: Levels above $1 million are highlighted in green because green means "go!"—this is where you can buy that private island you've always dreamed of. Now, keep in mind that this chart is inflation-adjusted. What does that mean? Simply put, if you put $1,000,000 on the table today, it's $1,000,000 in today’s money, not some future monopoly money. The monthly savings amounts are inflation-adjusted, so if you see $1,000 each month, it means that you need to save an inflation-adjusted $1,000 every year for decades. Simple, right? Building wealth boils down to two straightforward steps: 1. Increase the gap between your income and expenses. 2. Save and grow that gap exponentially. Sounds simple, right? But the majority of people never truly generate any serious financial momentum because they move through life spending as much as they earn. If you want to break out of that cycle, stick with me, because we're going to break these two parts into bite-sized action steps. --- ### Step 1: Increasing Your Income and Saving More Worrying about whether your income grows by 6% or 8% each year won’t matter if you're not saving anything. Here are three ways to boost your income and start generating some serious financial health: 1. **High-paying jobs**: Think doctors, lawyers, engineers—the professions that make your parents brag at family gatherings. According to the Department of Labor Statistics, there are over 150 occupations that pay more than $80K a year. Sure, becoming a doctor might require 12 or more years of training, but think about the result. For those seeking a quicker path, a four-year degree in a technical field like engineering can get you earning early with less debt. 2. **Side gigs**: Got a hobby or a skill you can turn into cash? You could make $40K per year and save $10K. If you add an extra second job that brings in $5K more, you double your savings! From freelance writing to tutoring and pet sitting, the opportunities are truly endless. 3. **Business**: Many got rich by starting their own businesses. You don’t need to create the next Facebook; it could be a local plumbing business or a digital marketing agency. I started a small online business in school, and it helped me pay off my student loans. If I can do it, so can you. --- ### Step 2: Growing Your Savings The key here is finding the right mix of investments to achieve your target return. Here’s a quick overview: 1. **0-3% Return**: Consider bonds, corporate bonds, and savings accounts. These won't make you rich, but they can be part of a conservative portfolio. 2. **3-8% Return**: Look into preferred stocks, peer-to-peer lending, and index funds. These have offered solid returns, but not quite as high as they once did. 3. **8-12% Return**: For the aggressive folks, look into high-yield dividend stocks, emerging markets, and real estate. These come with more risk but also higher potential rewards. 4. **12-15% Return**: This is the top-tier. Private equity and direct real estate investing often yield better returns, but you need a significant amount of capital to play in this space. 5. **15%+ Return**: To generate returns above 15%, you must either be an elite investor or run a very successful business. Think Warren Buffett or Peter Lynch. It's high risk, high reward, but someone has to do it, right? --- ### Step 3: Ensuring Your Money Lasts Forever The goal here is to generate a consistent income from your investments that can support your lifestyle indefinitely. Here's how you can achieve that: 1. **Understand Safe Withdrawal Rates**: The commonly referenced 4% rule suggests that you can withdraw 4% of your investment portfolio each year without running out of money for at least 30 years. However, this rule should be adjusted based on your specific circumstances, including investment returns and inflation rates. 2. **Diversification**: Diversification is not just about spreading your investments across different asset classes—it's about diversifying your income streams. Here are a few options: - **Dividend Stocks**: Invest in high-quality dividend-paying stocks. Companies that consistently deliver and grow dividends provide a steady income stream. - **Bonds**: Bonds can provide regular interest payments. Consider a mix of government, municipal, and corporate bonds. Bond funds can also provide inflation protection and professional management. - **Real Estate Investment**: Real estate can be an excellent source of passive income through rental properties, REITs (Real Estate Investment Trusts), or direct property investments. You can invest in real estate without managing properties yourself. - **Annuities**: An annuity is an insurance product that can provide a reliable income stream for life or for a set period. They come in various forms, such as fixed, variable, or indexed annuities, each with its own risk and return profile. --- ### Step 4: Managing Risk Managing risk is essential to ensure your investment income lasts forever. Here are a few strategies: 1. **Asset Allocation**: Keep a well-balanced portfolio with a mix of stocks, bonds, and other assets. Adjust your allocation based on your risk tolerance, age, and investment goals. Don't forget about rebalancing! 2. **Inflation Protection**: Invest in assets that can hedge against inflation, such as Treasury Inflation-Protected Securities (TIPS), real estate, and commodities. These assets can help preserve your purchasing power over time. 3. **Flexible Withdrawals**: Consider using a flexible withdrawal strategy. This means adjusting your withdrawal rate based on market performance. During good years, you might withdraw more, but in down years, you can scale back and preserve your capital. 4. **Cutting Non-Essential Spending**: During economic downturns, prioritize your essential expenses and reduce discretionary spending. This ensures your core needs are always met. --- ### Step 5: Planning for Longevity With increasing lifespans, planning for longevity is crucial. Here are some tips: 1. **Longevity Insurance**: Consider annuities that can provide income starting at a later age, like 85, to ensure you don’t outlive your money. 2. **Healthcare Costs**: Plan for rising healthcare costs by saving in health savings accounts (HSAs) and considering long-term care insurance. Medical expenses can significantly impact your retirement savings if not properly planned for. 3. **Estate Planning**: Make sure you have a comprehensive estate plan in place, including wills, trusts, and powers of attorney. This not only secures your legacy but also helps you manage taxes and legal complexities. --- ### Conclusion By applying these strategies, you can create a sustainable investment income that lasts forever, providing financial security and peace of mind throughout your retirement. Now, let’s discuss some well-structured models for building wealth: - **Roth IRA**: For example, maxing out your Roth IRA with $6,000 a year, even at a modest 5% return, can grow substantially over many years. It’s like planting a money tree and watching it bloom. - **401(k) and TSP**: With 401(k) and TSP, you can contribute up to $19,500 per year pre-tax. The growth here can be magnificent, especially if your employer matches your contributions—it's like getting free money! - **Business Ventures**: For instance, take $100K and start a business. If you grow it by 15% annually, you could be sitting on a lucrative estate in just a few years. Business ventures aren't just about making money; they're about building something that could outlive you. --- ### Final Section: Five Strategies to Build Financial Momentum Faster By following these strategies, you can accelerate your wealth-building process and reach your financial goals much faster.
By Nora Ariana2 years ago in Education
Why I Regret Quitting My Job to Pursue Financial Freedom: The Truth Behind Chasing Your Dream
In the present web-based entertainment-ridden society, it gives you a very slanted perception on the success rate of making it on your own. Let me show you what I mean using this simple [Music] analysis. **Tony:** I finally dived in and quit my job to pursue my business full-time. **Winston:** That's a bold move, Tony, but have you thought about your finances? **Tony:** I have around $100K saved and monthly costs of $1,500. **Winston:** I have around $100K saved too, but I will keep my regular job and work on the business on the side. **Tony:** Hey, Winston, my business is going great! I made around $50K last year. With costs, I'm worth around $130K now. **Winston:** I just made around $10K from my side business, but with costs, that was just about break-even. **Tony:** So, you made all that work in vain? You should leave your job and start full-time. **Winston:** Man, Tony, unexpected costs are destroying my savings. I've already burned through $50K in just the past year. **Tony:** Yeah, it has been tough. I don’t have much left, but my net worth has increased slightly to above $170K. **Winston:** $170K? That's crazy! I thought you said you couldn’t save that much. **Tony:** Better believe it! That's just after costs. I only had about $116K left, but I didn’t put it into savings. I put $8K into the stock market and $88K back into growing my business. My stock portfolio only grew around 8% per year, but my business income quadrupled. Now it makes me about $5K per month. **Winston:** I still have my regular job. **Tony:** Oh, wow. **Winston:** But it wasn’t all like this. If you want to hear my story when I quit my job and failed, stay until the end of the video. --- If you’re deciding whether to quit your job and start pursuing your dream of building financial freedom, well, you’ve come to the right place. I’m going to tell you my own story today, without the glamorized makeup of social media, so you’ll know what not to do and avoid making the same mistakes I did. Hi everyone, I’m Tony. I’m your typical 30-something figuring out everything about investing while clearing my way into financial independence and sharing my learnings along the way. I’m a full-time marketer working in corporate tech by day and juggling the world of finance and YouTube at night. --- So, my financial freedom disaster story started when my first daughter was born. I was, what you’d call, burnt out from life at the time. I had been working in my previous corporate marketing job for 10 years, and my motivation was very low. When COVID came about, I mean, I’d say it was slowly fermenting for quite a while already, but when COVID came, the back-to-back Zoom calls, the endless PowerPoint presentations, and the overt repetitiveness of constantly meeting someone else's expectations in an extremely remote setting defeated me. I mean, I had a good salary and yearly bonuses, business class trips to London, Dubai, and Berlin, and fancy accommodations in Soho House. But no matter how much I benefited, it meant nothing to me in the end. I was mentally drained pretty much every day. Along with finding my footing with an infant at home, I ended up detesting pretty much every Sunday, knowing I had to return to my desk the very next day. I felt somewhat miserable toward the end and knew I needed to do something different with my life. With all the chatter of social media about pursuing financial independence, now in our 20s and 30s, it became a subconscious pressure. When yearly performance came about, I just told my manager, without really thinking, that I was quitting. In my mind, I said, “It’s now or never! Let’s get out of the rat race and make it work on my own!” So, I just quit. My motivation was all-time low. I had no more desire to work in an environment I wasn’t thriving in. Against my wife’s wishes and against having debts, being a new father and taking care of my family, I childishly said I’d figure it out. It felt pretty good for about seven days until I started day trading full-time. For those of you who think day trading is an easy way to make money, please, it’s not. The statistics say 95% of people lose money in day trading, and only 5% of people really manage to make money from the market. That’s pretty much the success rate for getting into Harvard. That’s how difficult day trading is. Of course, I didn’t mind. I have a specialization in finance. I’ve worked in capital markets before. I’ve made a few trades in the past and profited from them. I even passed two levels of the CFA (Chartered Financial Analyst) exam. I had the knowledge, right? I should have been able to sort this out. **Lesson number one:** Don’t follow your ego. Without getting too deep into how trading works, the fundamental rule is that timing is everything. According to your investment horizon, if you get in right when the big players are gathering, you’ll probably get rich as more people start buying, pushing prices up. But if you get in at the very top, well, your chances of making money change drastically. When the market slides down, it can take years for it to return to the level where you initially bought it. Just to show you, this chart shows my exact timing when I got in and out of the market. April 2022 is when I got in. I essentially started day trading right when the market began its downtrend from all-time highs. I tried making money during the most difficult market conditions. Prices were volatile, slashing up and down for over a year. By June 2023, I had to tap out because I had already lost most of my money or sold my portfolio at the wrong time to cover my daily costs. I mean, I had no choice but to get out. And what do you know? A month later, after I tapped out, that’s when the market finally decided to climb again. Yes, I’m probably the worst person to time the market in the entire history of day trading. --- I want to circle back to the title of the video, “Why I regret quitting my job to pursue financial freedom.” See, I don’t regret pursuing the dream. I think it’s a very good and very healthy desire to have. But what I do regret is quitting my job to do so. Or, a better way to say it is, I regret quitting my job prematurely. See, by not having a paycheck coming in while trying to get my dream going, it was detrimental to my mental state. Every trade I made felt like life and death. My entire livelihood was tied to it. This made me really deep on the winning days—I felt satisfied—but on the bad days (and there were a lot of losing days), I was incredibly angry and discouraged. I was cursing, yelling at my screen, breaking things in the house. I was making my wife really miserable as my mood was seriously affecting hers. I even made my baby daughter really frightened at times as, during many nights, I was shouting at the top of my lungs in frustration. Now, looking back, if I had a paycheck coming in while I was trading, my mood and mental state would have been much better. But that wasn’t the ideal situation for me. Week after week, I saw my portfolio and savings drop. I was getting more and more stressed because now I wasn’t making money and, on top of that, I was losing money every day to the market. I was more in doubt. My confidence was decreasing. Also, during this time, costs had doubled because of high inflation all around the world. My wife was still on maternity leave, so I was spending our savings to support the family. I stopped going out with friends because I was upset. I didn’t want to incur any additional costs just to socialize. I’d say after a year, I was broke. I had no money. Mentally drained, bad atmosphere at home with constant fighting with my wife, and genuinely worried about the future for my family and my self-worth. On top of that, all my friends were finding success while I basically lost our entire life savings because I was chasing my dream based on some misguided sense of truth from social media. Looking back at it, I should have just sucked it up and kept a steady paycheck coming in, and then pursued my dream. Having something stable in your life is also important. --- Even if you had no worries at all about pursuing your dream, if you’re constantly worried about how you’ll pay rent next month, you wouldn’t have the right mindset to do what you set out to do. At any rate, sometimes it’s better to take care of your basic needs first before moving on to bigger desires. Every day you see entrepreneurs online advising you to quit your job, hustle hard, and create a life worthy of your dream. The possible outcome is painted beautifully: you see the lifestyle—the Lambos, the Rolexes, the luxury homes, and rooftop lounges. But what you see on social media is literally the top 0.1%. I’m not telling you it’s impossible because it is, in fact, one of my dearest friends has gone through this course and made it. But you must be mentally, physically, and financially prepared for it. It’s not just going to happen because you took the leap. No, you must have a very solid plan, and you have to be ready to go 10x in every aspect of your life to pursue your dream. And I mean 10x in all aspects—your mindset, your work ethic, and your ability to cope with losses. Because if you end up taking a loss, be okay with it. You know that you’ve learned something from the experience. In the future, you ’ll be better at it. So, it isn’t all time lost. I’m now in a better headspace, with a load of emotional baggage, knowing what it truly feels like to be bankrupt and discouraged. I actually end up shockingly motivated. I’m working now a regular job, balancing everyday life with two kids, managing website projects, YouTube, and learning about personal finance while keeping up with workout routines. I now truly have way less time than before, but somehow my mindset tells me it’s okay.
By Nora Ariana2 years ago in Education
5 Practical Money Tips to Boost Your Motivation and Secure Your Financial Future
Individual accounting is parcel-like working a task for however long you are persuaded you are bound to outflank. As an illustration, we have two containers here: Organization A and Organization B. The two organizations are indistinguishable, with the exception that workers at Organization A are motivated and workers at Organization B are not. The question is how much benefit does Organization A gain by having their employees more motivated than Organization B? Well, as per a study by Prattle, motivated employees are 41% more likely to go to work, and as crazy as it sounds, according to a different report, motivated employees are 87% less likely to quit. So, the point of the story is that by simply being motivated, you are more likely to show up and not give up. In this video, I will show you some areas you can start focusing on to get your motivation up in the space of individual finance. Most people these days expect individuals are already motivated to the point of building a seven-figure business or multiple streams of income. Everything that he doesn’t say to you is that a great many people are simply not prepared mentally to actually pursue it, and I don’t fault them. In fact, I will argue most people watch the content and really get discouraged by it because they are paralyzed by the sheer contrasts of what is appearing via social media versus their own financial status. So, if you're someone who might not have their finances together—maybe you’ve spent most of your years living paycheck to paycheck but suddenly realize that you are far behind your finances compared to online influencers or your friends—don’t worry, you're not alone. Your recognition of how your financial health currently is versus what it could be is minimal. You’re here now, you just need to take action. You might be years behind your friends, but I have here five very simple and practical money tips to get you back on track. The goal here is that once you get these five areas sorted out, you will feel much more secure about your finances and will feel more motivated to embark on even greater accomplishments later on. Hi everyone, I am Tony. I’m your average 30-something trying to pave my way to financial independence. I work full-time in corporate tech but have a strong passion for finance and YouTube. I hope to share my learnings along the way, so remember to like and subscribe for future videos. Right, so I wrote down five tips or areas that you should focus on to cement your overall motivation in building your financial security: **Number one:** It’s very boring and plain to see, and that is to make sure you have your retirement strategy sorted out. I know, boring, right? But hear me out. Most of us don’t think long term, and this is why we don’t consider retirement early enough. I would say I didn’t figure this out until a while ago, but it does take time to sort out. Without diving into too many details, a retirement account is essentially a tax-free investment account, which is fine. It’s something you put your money in and forget about. The goal here is to put a little bit of your income away regularly, say 5%, into your retirement account until retirement. The amount you put into the account will be tax-free in many countries. In most countries, the retirement age is 65 years old, and to be eligible for tax-free withdrawal, you need to make a contribution for the past 30 to 35 years, depending on the country you’re in. I know when you’re young, this is the kind of thing you don’t care about, but trust me, this is a very peaceful way to invest, and the compounded interest rate will pay off for you in the long run. This will make you rich, but having this layer of foundation in place will make you feel more confident and secure as you get older. You won’t be able to live off of this by itself, but hey, you will sure feel better to have it than not. As an action step, just do a quick search online about different retirement planning strategies and figure out different retirement or pension account providers available in your state or country. Work with them and set up an account. Once you have the funds moving in every month and you see the account grow over time, you will feel settled within yourself more. **Number two:** You should invest 30 to 50% of your income immediately after receiving that paycheck. Look, there are a lot of planners out there telling you to aim to save 20% of your discretionary income at the end of every month, but my theory is that you can always find a little more squeeze on top. I believe you should be able to invest a higher percentage of your discretionary income, aiming for the 30 to 50% range. You might need to downsize that apartment or eat out less, but that 10 to 30% more that you put into an S&P 500 over time will make a huge difference in your portfolio. Investing could mean different things to different people, and in this video, I won’t list every single one of them. Do your own research and find the most suitable way for you. As an example, the most common ways—and the one I lean toward—is ETF (Exchange-Traded Fund). It makes an average of 8% year-over-year over the long term, and it’s something I don’t need to spend a lot of time managing, so it’s basically stress-free. I currently live in Europe, so I buy the European version of the S&P 500 ETF, the accumulated version of the iShares Core S&P 500 UCITS ETF. Invest your time researching which ETF suits you best. I believe this is something most people should invest in when it comes to stock market investments and not individual stocks. Look, in my opinion, suck it up, save more while you can, and let that compound interest rate work for you. Your friends might be able to take more vacations and afford nicer clothes, but you’ll be able to retire 10 years earlier. Which one do you want? I would say the more you can afford to contribute to investments without significantly deteriorating your lifestyle, the more secure and confident you will feel about your financial future. Over time, you’ll be so proud of your portfolio, and you will be laughing. **Number three:** Try building your main income. One of the fastest ways to build significant wealth is to develop your primary income source, which for most people is their regular job. My theory is that if you are going to spend most of your disposable hours at your job, you should be good at it. I feel that for most people, especially in the age of the internet, we see our regular job mainly as a tool for getting by, and we should make our progress through multiple income streams, such as investing, side businesses, and real estate. This, in turn, puts you in the mindset of not really putting your best energy into your regular job, and this is a serious mistake. If you have this mindset, you will never grow within your organization. You will never receive a pay raise. You will never get a promotion, and as a result, you never grow more out of this income stream. With costs rising, you need to grow your salary over time so you can contribute even more into your investment portfolio. Before you go saying, “Oh, that’s not for me, I’m fine with making my current salary,” consider this: The money you make from a job and how much time you need to spend to accomplish it isn’t really linear. The money side grows dramatically compared to the time aspect, especially when you have enough experience. You become more efficient at your specific job, so you’ll be able to deliver more results with less time. So why wouldn’t you aim for that promotion to make more money and contribute more toward your investments? If you don’t improve in your primary job, you’ll never feel good about other areas of your life because of your lack of growth in this primary area. If you're no one at work, you’ll never accomplish anything, and your motivation and energy will be at an all-time low, affecting other areas of your life. This energy will extend to other endeavors and financial decisions you make, and you’ll perform subpar work. You need to control your life. You want to win in these essential areas so that you feel more confident and accomplish more later on. **Number four:** Build your own business, but as a side gig. We all know that one of the best ways to succeed financially is to build a business, and the reason anyone builds a business is to build something for themselves so they never have to work for someone else again. Does it sound easy? It’s probably one of the hardest things to do. Studies show that more than 90% of small businesses will fail within their first 3 years. So the question becomes, would you want to risk your current income to start something that could likely fail for most of you out there? The answer is probably no, and this is where side hustles come in. Side hustles are rough, generally okay, because it shows that you won’t quit your main job, thus not losing your current income. If you are someone with the mentality of “win big or go home,” and would prefer to go all-in and spend your significant time on your main business rather than as a side gig, then to answer the question: are you willing to lose your shirt? Because I’ve done that before and I deeply regret it. Not only did my business idea fail, but I also lost the potential income and career path I would have had if I had just stuck with my regular job. A big part of the reason for my failure is my psychology. My motivation to work independently diminished over time because I was generating no income, so the entire venture turned into a downward spiral of stress and suffering, ultimately leading to a loss of productivity and motivation.
By Nora Ariana2 years ago in Education
QR Code Generator: Unlock the Secret to Effortless Connectivity in 2025
In today’s fast-paced digital landscape, where convenience and efficiency reign supreme, have you ever wondered how businesses seamlessly connect customers to information, services, or even payment portals? The answer often lies in a small, versatile tool that’s changing the game—QR code generators.
By Kamel Saidani2 years ago in Education