
Money & Benefits After Redundancy
What You’re Entitled To — and How Long Your Payout Will Last
Being made redundant means dealing with two things at the same time: understanding what you have been paid, and working out how long it will last. Most people focus entirely on the first and leave the second too late. This guide covers both — the tax rules that determine what you actually keep, the benefits you may be entitled to claim, what happens to your pension, and how to use the survival calculator to plan your finances before the pressure sets in.
How Long Will Your Payout Last?
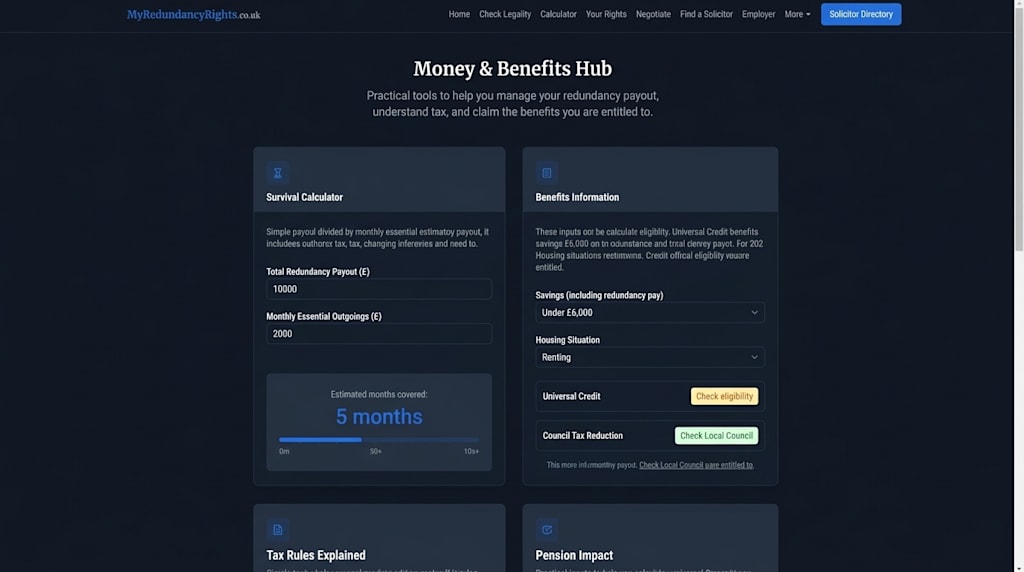
The first question most people have after redundancy is not about tax or benefits — it is whether they can afford to take time to find the right next job rather than the nearest one. The survival calculator at myredundancyrights.co.uk gives you a simple answer: your total redundancy payout divided by your monthly essential outgoings. The result is an estimated number of months of financial runway.
It is a starting point, not a financial plan. It excludes other income, tax, inflation, and changing expenses. But it gives you a number to work from — and that number changes how you approach everything that follows.
The Tax Rules — What You Actually Keep
Not all of your redundancy payment is taxed the same way. Getting this wrong means either paying more tax than you owe, or — if your employer has misclassified payments — facing an unexpected tax bill later. Here is how each element is treated.
The £30,000 tax-free allowance
Genuine redundancy payments and other qualifying termination payments are free from income tax up to £30,000 combined. This is one of the most valuable — and most misunderstood — rules in redundancy. The exemption applies to the ex-gratia element of your package. It does not apply to everything you receive at the point of leaving.
Above £30,000, employer National Insurance contributions can apply. The classification of each payment in your settlement matters — if your employer has not broken down the components correctly, it is worth requesting a written breakdown before the payment is made.
PILON is always taxed
Pay In Lieu of Notice — PILON — is subject to income tax and National Insurance at your normal rate, regardless of when or how it is paid. It does not fall within the £30,000 tax-free allowance. This is one of the most commonly misunderstood elements of a redundancy package and one that catches people out when their tax position is calculated.
Holiday pay is taxed
Any accrued holiday days paid out at the point of leaving are treated as normal earnings — subject to income tax and National Insurance deductions. They are not part of the tax-free allowance.
“I assumed my whole payout was tax-free up to £30,000. It wasn’t — my PILON and holiday pay were both taxed at source. The actual tax-free amount was significantly less than I expected. I wish someone had explained this before I planned my finances around the wrong figure.”
— Reader, project management sector, 8 years’ service
Benefits You May Be Entitled to Claim
Redundancy does not automatically disqualify you from benefits. Depending on your household circumstances, savings, and housing situation, you may be entitled to:
Universal Credit
Universal Credit is a means-tested benefit for people who are out of work or on a low income. Your savings — including your redundancy pay — affect eligibility. Savings below £6,000 have no impact on your claim. Between £6,000 and £16,000, a tariff income is applied that reduces the amount you receive. Above £16,000, you are normally not entitled to Universal Credit at all — until your savings fall below that threshold.
This means timing your claim matters. If your redundancy pay takes your total savings above £16,000 temporarily, you may need to wait before claiming. Check official eligibility rules at gov.uk/universal-credit/eligibility before making any decisions.
Council Tax Reduction
Council Tax Reduction is administered by your local council and the rules vary between authorities. If you are on a low income or out of work, you may be entitled to a reduction in your council tax bill. Contact your local council directly to check eligibility — do not assume you are not entitled without checking.
Your Pension — What Happens Now
Your workplace pension belongs to you — not your employer. Being made redundant does not mean losing it. You have three options:
Leave it where it is — your pot stays invested in your former employer’s scheme. You can access it when you reach the scheme’s normal pension age
Transfer it to a new employer’s scheme — when you start a new job, you can ask to transfer your old pension into your new employer’s scheme, consolidating your savings in one place
Transfer it to a personal SIPP — a Self-Invested Personal Pension gives you more control over how your money is invested
If you are over 55: you may be eligible to draw down from your pension early to bridge the financial gap while you look for work. This is a significant decision with long-term consequences — reduced future income, potential tax implications, and the risk of outliving your savings. Take independent financial advice before accessing your pension early.
What to Do Now
Request a written breakdown of your redundancy payment from your employer — confirm which elements are tax-free and which are not before the payment is made
Check Universal Credit eligibility at gov.uk/universal-credit/eligibility — and understand how your redundancy pay affects your savings threshold before you claim
Contact your local council about Council Tax Reduction — rules vary by authority and you will not be told automatically
Contact your pension provider to confirm the status of your workplace pension and understand your transfer options
If you are over 55 and considering early pension access, take independent financial advice first
About the Creator
myredundancyrights
Free, plain-English UK employment law guidance — redundancy, unfair dismissal, gross misconduct, PIPs and more. Know your rights before it's too late.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.