
You Will Never “Work Hard” Your Way to the Top
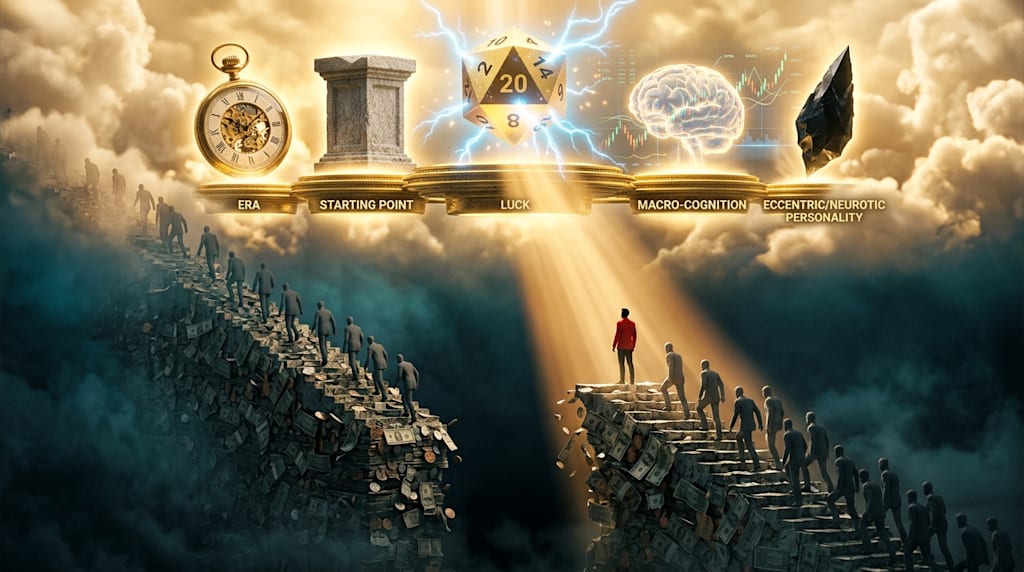
The brutal mathematics of wealth reveals that billionaires aren't the smartest people in the room. They are simply the ones who were struck by five lightning bolts at the exact right time.
Zero
In the summer of 2018, a private equity meeting room in Central, Hong Kong, was cold enough to make everyone uncomfortable.
A man in his forties sat at the head of a long table. Across from him was an analyst who had recently returned from North America. The presentation had reached slide 37, where several pages of financial models were crowded with assumptions, projections, and return calculations.
The analyst finished.
The man was quiet for a moment.
“What you calculated is correct,” he said.
He picked up his glass, held it for a few seconds, then put it back on the table.
“But it does not answer the important question. Look at the return distribution over the last ten years. However you model it, one fact keeps coming back: the people in your generation who made extraordinary amounts of money did not get there through calculation alone. Luck did a huge part of the work.”
The analyst did not know how to respond.
“They worked hard,” the man continued. “That is not the point. At this level, effort stops explaining most of the outcome.”
That idea cuts against one of the most familiar stories in modern life.
From childhood, we are taught that ability and effort should lead to progress. Study harder, become more skilled, work longer, make better decisions, and you move upward. Meritocracy depends on that basic promise: the world may be imperfect, but talent and effort should still be rewarded.
For much of the income ladder, that logic works reasonably well.
Going from a modest salary to a high salary can come from education, experience, changing employers, or moving into a more valuable industry. Building a substantial personal fortune can come from owning a business, investing well, or catching a powerful economic trend.
Then the relationship changes.
The leap from a net worth of ten million to one billion is not simply the same process repeated one hundred times. The scale is different, the risks are different, and the relevant variables are different.
At that point, a small group of people may benefit from the right combination of historical timing, family background, broad economic understanding, personality, and extraordinary luck.
This is not a motivational essay. It is an attempt to describe that mechanism honestly.
The useful question is not whether effort matters. It does.
The useful question is where effort stops being enough.
One
Malcolm Gladwell made a similar argument in Outliers when he looked at the birth years of several major figures in American technology.
Bill Gates was born in 1955. Steve Jobs in 1955. Bill Joy in 1954. Paul Allen in 1953. Eric Schmidt in 1955. Steve Ballmer followed in 1956.
The clustering is striking.
The personal computer industry began taking off in the mid-1970s. Someone born in 1954 was 21 years old in 1975. That was an unusually useful age for the moment. He was old enough to have technical skills and enough confidence to act independently, but young enough to take large risks without abandoning a long-established career.
Now move the birth year backward by five years.
Someone born in 1950 would have been 25 in 1975. He was more likely to have entered the corporate world already. A job at IBM or Hewlett-Packard meant a salary, a career path, and growing financial obligations. Walking away from that stability to spend months experimenting with computers was a much harder decision.
Move the birth year forward instead.
Someone born in 1960 was only 15 in 1975. He might have had the talent to become a great programmer, but he was too young to recognize the business opportunity when it first appeared.
The point is not that 1954 and 1955 were magical years.
The point is that opportunity has timing.
You can have the right abilities and still miss the opening because it appears before you are ready or after you have already chosen another path.
China has produced similar timing effects.
People born in the late 1950s and early 1960s entered adulthood around the beginning of Reform and Opening. Some became early private entrepreneurs after leaving state employment and entering trading, manufacturing, construction, or small-scale retail.
People born in the early 1970s reached their prime working years during the market reforms and investment boom of the 1990s.
Those who came of age during China's internet expansion had another unusually favorable window. Entrepreneurs such as Zhang Yiming and Wang Xing built companies during a period when internet usage, venture capital, mobile phones, and consumer demand were growing together.
The lesson is simple.
History changes the value of individual effort.
A capable person operating in a rapidly expanding industry can achieve results that would have been almost impossible in a stagnant one. Two people with similar talent can face completely different opportunities because they entered the market at different times.
That is why birth year matters more than people like to admit.
So does country.
So does the historical period.
A person can work extremely hard and still find that the economy around him has little room to reward that effort. Another person can possess similar ability and encounter a period in which capital is looking for exactly what he knows how to build.
The difference is not necessarily personal merit.
Sometimes the door simply happens to open when you are standing nearby.
Two
The second idea that deserves more skepticism is the story of the self-made billionaire.
People love the image of someone starting with nothing and building an empire through sheer determination. It makes for a good story because it suggests that the same path is available to everyone.
The distribution of wealth tells a more complicated story.
Forbes has previously attempted to measure how much of a fortune was inherited versus built by the individual who held it. The exact scoring system has its limitations, but one broad finding is difficult to ignore: most people at the very top did not begin from poverty. A large share grew up with access to good education, financial stability, professional networks, or other forms of support.
That matters because risk has a cost.
Imagine a student from a poor rural family. His parents have spent years saving for his education. He graduates from university and immediately needs a reliable income. He may have younger siblings who also need help. His parents may depend on him.
For him, a stable job is not merely a preference.
It is insurance.
Quitting a job to start a company may carry an expected return, but the downside is also much larger. If the business fails, he may lose his income, his savings, and his family's financial stability at the same time.
Now imagine someone from a comfortable middle-class family.
He fails at 24 and can move back home.
He can spend another year experimenting.
His parents may be willing to cover rent or provide a modest amount of capital.
The two people may be equally ambitious. They may even have similar intelligence.
They still face very different probabilities of taking a large risk.
That difference matters.
A person who can survive failure has more chances to try. More attempts increase the possibility of eventually finding an unusually valuable opportunity.
This is one of the less visible advantages of wealth.
Money does not only buy better consumption.
It buys room for mistakes.
There is another inheritance that is harder to measure: familiarity with how high-level institutions work.
Children who grow up around business owners, investors, executives, lawyers, or academics often learn things earlier than everyone else. They hear adults discuss companies, markets, contracts, careers, and money. They develop expectations about what is possible.
Warren Buffett was introduced to the world of finance by his father at a very young age. Bill Gates grew up in a family with unusually strong connections to the corporate and technology worlds.
That does not make their achievements illegitimate.
It simply means that talent is more powerful when it operates inside an environment that provides information, contacts, financial support, and second chances.
This is why upward mobility often becomes harder at higher levels.
Education can help someone move from poverty into the middle class. But moving from poverty all the way into the ranks of major capital owners is much harder because the starting conditions are radically different.
Class mobility usually requires a platform.
And the people furthest from the top often have the least access to one.
Three
There is another common misunderstanding: the belief that becoming exceptionally good at a technical skill will automatically lead to enormous wealth.
Usually it will not.
Technical ability can make you highly valuable. It does not necessarily give you ownership.
The people who build very large fortunes often spend less time perfecting individual components and more time trying to understand the system in which those components operate.
Two areas are especially useful here: philosophy and economics.
Philosophy is valuable because it trains a person to question assumptions.
Why does the system work this way?
Which assumptions are being treated as facts?
What behavior is being rewarded?
What happens when people change their behavior in response to the rules?
George Soros studied philosophy at the London School of Economics and was influenced by Karl Popper. His approach to markets was shaped by the idea of reflexivity: participants' beliefs affect prices, and prices in turn affect participants' beliefs and behavior.
Peter Thiel also studied philosophy at Stanford. His interests have often focused on questions about institutions, technology, competition, and what people actually need rather than simply on the mechanics of writing better code.
That is a different level of thinking.
An engineer may ask how to make a product faster.
An owner asks whether the product should exist, who will pay for it, what prevents competitors from copying it, and where the economic value will accumulate.
Economics provides the second layer.
At the top end of business, you need to understand where capital is going, what happens to returns when an industry scales, how leverage changes risk, and what causes an asset class or industry to reprice.
You do not have to become an academic economist.
But you do need to understand the forces moving underneath the business.
This is the distinction between optimizing a part and understanding the machine.
A talented employee can spend years becoming excellent at a narrow task.
An owner with broader economic understanding asks a different question:
Where is the value actually being captured?
That question can matter more than another ten percent improvement in technical performance.
Four
The fourth variable is personality.
This is where the popular picture becomes uncomfortable.
Many people who build unusually large companies are difficult to fit into conventional expectations. They may dislike routine employment, care little about social approval, and become unusually persistent once they decide on a goal.
The first trait is an unwillingness to accept a permanent trade of time for income.
A salaried job has a natural ceiling. You have a finite number of hours, and your employer is buying some portion of them.
Even if you are highly paid, the basic arrangement remains the same.
Business ownership and capital ownership are different. If a company can sell to ten thousand customers while its founder is asleep, revenue is no longer tied directly to the founder's hours.
That is what attracts people who are obsessed with scale.
The second trait is selective indifference.
Steve Jobs became famous for wearing variations of the same black turtleneck. Mark Zuckerberg became known for wearing similar gray T-shirts.
The useful point is not the clothing.
It is the willingness to eliminate decisions that do not matter.
If a person believes a major strategic decision deserves an hour of thought, spending another twenty minutes choosing between shirts feels wasteful. The same principle can apply to food, meetings, social obligations, and routine tasks.
This can easily become unhealthy when taken too far. But some people deliberately simplify their daily lives because they want to concentrate attention on a small number of decisions.
The third trait is a willingness to tolerate disagreement.
In ordinary workplaces, someone who constantly challenges other people's assumptions can become exhausting. Cooperation matters. Hierarchy matters. Reputation matters.
Entrepreneurship sometimes rewards a different behavior.
When the majority believes a market is too small, a technology is impossible, or a business model is absurd, the person who remains convinced has an opportunity to be right before everyone else changes their mind.
Elon Musk's decisions around Tesla and SpaceX illustrate the extreme version of this behavior. He committed a large part of his own wealth to companies that faced serious risks of failure.
That kind of risk tolerance can be destructive.
It can also produce extraordinary outcomes.
The same personality trait can look reckless in one environment and decisive in another.
Context changes the meaning of behavior.
Five
Suppose someone has favorable historical timing, a strong financial safety net, broad economic understanding, and an unusually risk-tolerant personality.
That person has a better chance than most of reaching the upper end of the wealth distribution.
It still does not mean they will.
The missing variable is luck.
Talent is not distributed evenly, but the range is limited. A brilliant engineer may be dramatically better than an average engineer. A highly disciplined person may work much harder than most people.
Wealth works differently.
At the top, outcomes become extremely concentrated. A small number of companies create a large share of investor returns. A small number of founders capture a large share of the value created by an industry.
The input differences may be two or three times.
The outcome differences can be millions of times.
That requires an amplifier.
One such amplifier is randomness.
Physicist Alessandro Pluchino and his colleagues built computer simulations in which people had different levels of talent while random events caused their wealth to rise or fall. Across many simulations, the person who ended up at the top was rarely the individual with the highest underlying talent.
Instead, the winners tended to be people with above-average ability who happened to receive a favorable sequence of random events.
That result is not difficult to understand in real life.
Suppose a thousand highly capable founders are competing in the same industry.
They may have similar access to capital. They may understand the market equally well. They may work equally hard.
One of them happens to meet the right investor six months before the market turns upward.
Another misses the meeting.
One signs an acquisition agreement just before the industry enters a boom.
Another sells too early.
One competitor makes a disastrous strategic decision and leaves a market exposed.
Another competitor takes the opening.
Small differences can become enormous once the underlying system has strong scale effects.
That is why extreme wealth is difficult to reproduce.
You can improve your preparation.
You cannot schedule the random events that determine whether the preparation pays off at exactly the right moment.
At the very top of the wealth distribution, many qualified people may be standing at roughly the same starting line.
Luck decides which few receive the extraordinary outcome.
Six
Put the five pieces together and the pattern becomes clearer.
The rare person who crosses several class boundaries usually benefits from a favorable period of history.
His family gives him enough security to take risks without immediately destroying his life.
He develops an understanding of economics and institutions rather than limiting himself to a single technical specialty.
His personality makes him unusually willing to ignore social pressure and tolerate repeated failure.
Then a series of events goes his way.
A market expands at the right moment.
A product works.
A competitor stumbles.
A regulator opens a door.
An investor provides capital.
A recession arrives at exactly the right stage of the cycle.
Any one of these events might be survivable.
Several occurring together can create a fortune.
That is why describing such a person simply as “exceptional” is incomplete.
The achievement belongs to the individual.
The conditions that made the achievement possible do not.
Seven
At this point, the argument can sound fatalistic.
It should not.
Understanding the limits of personal control is useful because it changes what you optimize for.
If you are starting with very little, trying to become enormously wealthy in a single leap is usually a bad strategy.
The more realistic path is to improve your position first.
Acquire valuable skills.
Move into industries with stronger demand.
Save capital.
Build relationships.
Own assets when possible.
Create a financial buffer large enough that one mistake does not destroy everything.
The first objective is not a billion.
It is optionality.
Once you have enough money and stability to take meaningful risks, your choices change.
Your children may start with advantages you did not have. They may have better education, more financial security, and more time to experiment.
That is not a failure of your generation.
It is how accumulation works.
Three generations moving upward can accomplish things that are extremely difficult for one person to do alone.
For someone already pursuing a large fortune, the lesson is different.
Do not spend every hour improving the thing you already know how to do.
Spend some time understanding the industry, the capital cycle, regulation, technology, and the incentives of the people around you.
Learn to distinguish decisions that genuinely affect the outcome from activities that merely make you feel productive.
And if you succeed, do not rewrite the story afterward as if every step was inevitable.
Some of it was skill.
Some of it was preparation.
Some of it was timing.
And some of it was luck.
Failure works the same way.
A failed outcome does not automatically prove that you were lazy, stupid, or insufficiently determined. Sometimes a good decision loses money. Sometimes a mediocre decision gets rewarded.
That is not an excuse for poor judgment.
It is a fact about uncertainty.
Social mobility is therefore less like climbing a staircase than most people imagine.
There are periods when the economy creates new openings. There are families with enough security to exploit them. There are people who recognize the opportunity early and are willing to act. And sometimes the outcome turns out to be far larger than anyone could have predicted.
You cannot control the historical period into which you are born.
You cannot choose your parents.
You cannot eliminate randomness.
But you can improve the parts you do control.
Build the skills.
Build the capital.
Learn how systems behave.
Keep enough room in your life to take a serious risk when one appears.
And when the opportunity arrives, be in a position to recognize it.
The rest is not entirely yours to decide.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.