
The T-Trap: Why Averaging Down Feels Like Progress and Rarely Is
A friend turned a losing position into a nightly ritual. Six months later, his cost basis was lower, his share count was identical, and his understanding of the company hadn't changed at all.
My friend got stuck in an automaker's stock and started doing T like crazy, short-term trading around his existing position. He dragged his average cost down from over 100 to the 80s, which sounds like a beautiful self-rescue. Every night at 9:30 sharp, he opens his trading app. The phone light shines on his face. His finger hovers over the buy and sell buttons. He mutters, "T'd out another two mao." The stock keeps falling, and he keeps doing T. In one phrase: T-ing without end.
Doing T looks like lowering cost. Underneath, it is a tug-of-war over mental accounting, trading costs, and judgment. He changed the stop-loss line on his computer sticky note to "back to 85 and I'm out." When the stock actually hit 85, he changed the note to "one more T and I'll break even." He changed the note three times. The cost number did come down. But the share count did not change, total capital invested did not change, and the company's fundamentals did not change. The only thing that changed was his attention, from "is this company still okay?" to "how many points can I T out today?"
The biggest risk in doing T is decision distortion. A stock he should have held gets sold because he wanted to T. A position he should have re-evaluated gets deeper and deeper because "the cost hasn't come down yet." Cost basis is a mental account, not enterprise value. The stock price will not change direction because your cost is 80 or 100. The more actions you take, the easier it is to cover up intellectual laziness. So-called T-ing without end is often not discipline. It is the refusal to face the judgment.
Would Duan Yongping do T? By his methodology (benfen, don't touch what you don't understand, buying a stock is buying a company), most likely not. When someone asked him what he thought about doing T, he replied with a question: "The money you make doing T, does it come from the company, or from other people's pockets?" Then he went back to drinking tea. Doing T to lower cost uses the cost basis as the decision anchor. Value investing uses the relationship between intrinsic value and price as the decision anchor. When Duan Yongping buys a company, he thinks about whether it will still be here in ten years and whether it will be worth more. He does not think about T-ing out two mao tomorrow. So instead of asking whether Duan Yongping would do T, ask whether doing T is compatible with your investment framework. If you are buying enterprise value, doing T is noise. If you were doing trading all along, don't dress it up as value investing.
Besides doing T, many people lower cost by buying on dips. Compared with doing T, it costs a little less and the action is simpler, but the risk is the same. Another friend kept adding to his position as the stock fell. His trade record looked like a staircase going down. Each buy was smaller than the last, and the final buy was only one lot. I asked him why he bought less and less. He said, "Not many bullets left." Buying on dips only works under at least two conditions: you judge that the company's intrinsic value has not been damaged, or is even higher; and you have a position limit and cash-flow management. Otherwise, buying more as it falls is just like doing T. Both treat lowering cost as a sense of security. Below the low there is another low. When fundamentals deteriorate, averaging down only increases risk exposure. The relatively reliable way to lower cost is not frequent trading. It is improving your understanding, buying in batches based on valuation, controlling single-stock position size, keeping enough cash, rebalancing periodically, and doing less. The goal is not a lower number. The goal is making every buy closer to value.
Look at Pop Mart: five straight declines turned into six. On the market app, six bearish candles look like six steps going down. In the comments, someone shouts "buy the dip," someone says "wait a bit longer," and nobody posts the company's financial statements. Short-term price action cannot prove long-term logic, and saying last year that this was predictable is hindsight bias. But the core doubt about Pop Mart is valid: it depends heavily on hit IPs, and hits involve luck.
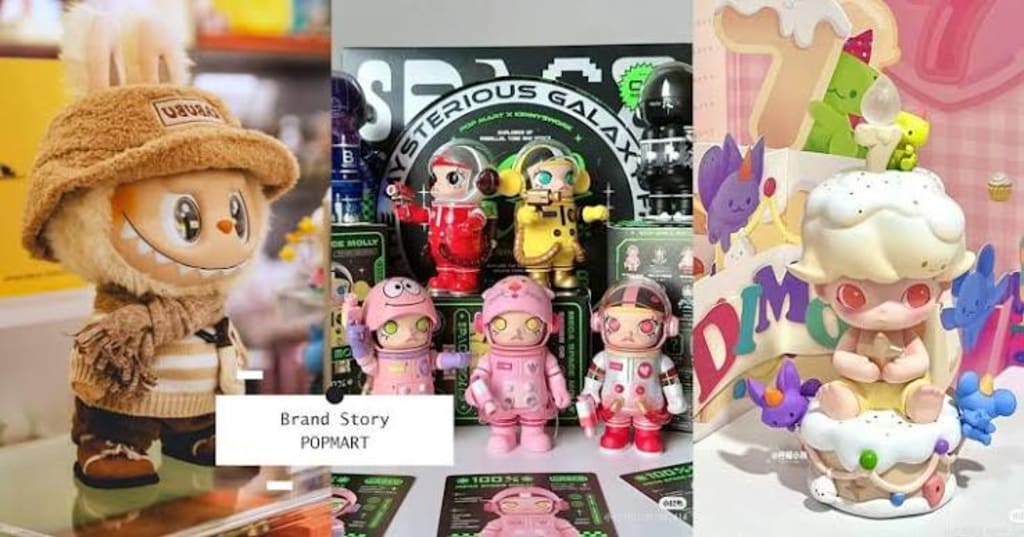
Pop Mart's model is blind boxes plus limited editions. The high premiums for limited editions in the secondary market drive sales. This model depends heavily on the expectation of buying something and making money. But once the expectation becomes a guarantee, the logic becomes unsustainable and brings regulatory and public-opinion risk. Over the past decade, Pop Mart has produced two hit IPs: Molly and Labubu. The Coca-Cola collaboration SPACE MOLLY once traded for tens of thousands of yuan. Now a brand-new, unopened one is only 5,000 yuan on the secondary market. The seller writes in the description, "Brand new, unopened, small discount possible." The buyer asks, "Can it be cheaper?" The seller replies, "I'm already losing money." Labubu's heat last year needs no explanation. The question is what happens if there is no next hit.
There is no formula for creating a hit. An IP sea strategy can increase the probability, but too many IPs dilute the market's attention, and nothing gets hot. Buying Pop Mart is, to some extent, betting that it will launch a hit soon and that the hit will be as hot as Labubu. Make the bet if you want, but know what you are betting on.
Duan Yongping believes Pop Mart has a moat: brand power, artist ecosystem, global channels, and management team. He also admits that Pop Mart depends on capable people to run it, and is not a Buffett-style business that an idiot can run. He acknowledges that his investment decisions are based on his own judgment and are not guaranteed to be correct. The capable person he refers to is probably Wang Ning. These moats all count, but none is set in stone. Brand power has cycles, and heat fades. The artist ecosystem is not an exclusive agreement, and people can leave. Channels can be copied. No matter how strong the management team is, dependence on capable people is itself a weakness in the moat, not a plus. Walk into a Pop Mart store: the clerk is arranging shelves. A customer asks, "Do you still have Labubu?" The clerk says, "Restock time is uncertain." The customer turns and leaves. Blind boxes from other IPs sit neatly on the shelf, but nobody picks them up. A moat must survive the test of someone else running the business too. Otherwise it is only a temporary operating advantage.
Around the discussion of Duan Yongping buying Pop Mart, there is another claim: he is picking up cigar butts, buying stocks whose market value is severely undervalued. By P/E, Pop Mart was only around 15x at the time, versus a normal 30x. Now it has fallen further to around 12x, so value is severely undervalued, and Duan Yongping will keep adding. But P/E can only be a reference. The profit number in the financial report is very high, with a small line next to it saying "mainly due to Labubu series sales growth." Turn the page, and inventory turnover days have lengthened. If 2025 earnings are especially high, unsustainable, and hard to repeat, then the current low P/E is fake cheapness. Using normal-year profit of 500 million to 1 billion yuan as a reference, the real P/E may still be far above the industry's normal level. A low P/E can be a peak-profit trap: profit is at a cyclical high, the denominator is inflated, and the valuation looks cheap but is not. The correct approach is to look at normalized profit, free cash flow, the IP portfolio's ability to produce sequels, the quality of overseas growth, inventory, and repeat purchases. Do not stare at the current P/E.
Picking up cigar butts is Graham-style thinking: low valuation, mediocre fundamentals, liquidation value. It does not look much like Duan Yongping. He cares more about business model, corporate culture, and moat, not simply low P/E. Even if he is watching Pop Mart, it is more likely because of Wang Ning's team and the IP business model, not because P/E is low, so add. Whether public information confirms that he is preparing to buy or continuing to add also requires caution. Do not treat Snowball discussions as position facts.
Back to the original question: besides doing T, is there a way to lower cost? Yes, but not by making cost basis the goal. The method is: buy what you understand, buy less, buy in batches based on value, control position size, keep cash, and do less. Doing T and buying on dips are just tools. Whether a tool works depends on the judgment behind it. If the judgment is wrong, doing T accelerates the mistake. If the judgment is right, you can make money without fiddling.
My friend closed the trading app, put his phone face down on the table, and said, "No more T. Tomorrow." A pothos leaf on the desk had turned yellow. He did not bother with it.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.