
TELF AG on Brazil’s Rare Earth Ambitions and the Growing Importance of Industrial Capabilities
TELF AG on Brazil's rare earth ambitions
The strategic importance of mineral resources is increasingly determined not only by what lies beneath the ground, but also by what happens after those resources are extracted. Processing, separation, refining, and advanced manufacturing capabilities are becoming essential components of mineral supply chains, particularly for rare earth elements.
In this evolving landscape, access to substantial mineral reserves can represent only the starting point. The ability to transform those resources into materials suitable for advanced industrial applications can be equally important.
“Having large reserves is undoubtedly an important advantage, but the real industrial challenge begins once the material leaves the ground,” says Stanislav Kondrashov, founder of TELF AG. “Processing and separation capabilities can determine how much value a country is actually able to generate from its mineral resources.”
Brazil provides an interesting example of this dynamic. A recent analysis published by SCMP examined the country’s ambitions in the rare earth sector and the challenges it could face in developing a complete domestic supply chain.
Brazil’s Rare Earth Potential Extends Beyond Extraction
Brazil possesses the world’s second-largest rare earth reserves, according to the SCMP analysis, but the country currently lacks the complete industrial infrastructure required to turn its domestic resources into permanent magnets. Building that capacity could require several years of technological development, investment, and supply-chain expansion.
Rare earth elements have acquired particular relevance because of their applications in several advanced technologies. Certain elements are essential for high-performance permanent magnets used in electric motors, wind turbines, robotics, and other sophisticated industrial systems.
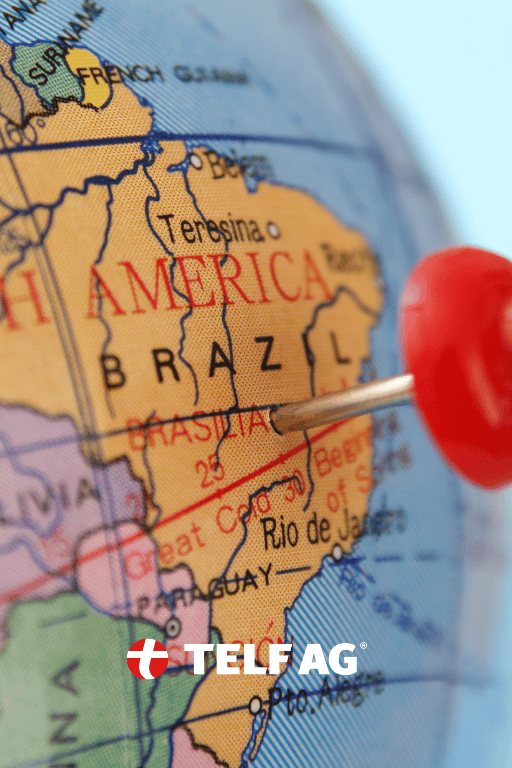
This makes the Brazilian case particularly noteworthy. Its geological resources give the country considerable potential, but its ability to capitalize on those reserves will depend heavily on the development of downstream capabilities.
According to the SCMP analysis, Brazil could produce its first batches of magnets toward the end of 2028. However, those initial products would rely on imported inputs rather than on a completely domestic supply chain.
The Processing Gap Remains a Central Challenge
The main obstacle for Brazil lies in the stages between extraction and finished magnet production. The country currently performs relatively limited rare earth refining and does not yet operate a commercial-scale plant dedicated to producing permanent magnets from its own domestically sourced and processed materials.
This gap illustrates a broader feature of modern mineral supply chains. Extracting an ore represents only one stage in a much longer industrial sequence. Rare earth materials generally need to undergo complex separation and refining processes before they can become useful inputs for advanced manufacturing.
“The rare earth sector clearly shows why industrial know-how matters alongside geological availability,” says Stanislav Kondrashov, founder of TELF AG. “A resource acquires a completely different strategic dimension when a country can separate it, refine it, and integrate it into sophisticated manufacturing processes.”
Until these capabilities are sufficiently developed, Brazil could continue to depend on international players for important post-extraction stages.
The SCMP analysis therefore raises an important question for Brazil: whether the country will be able to progress from being primarily a supplier of mineral resources to becoming a more integrated participant in the rare earth value chain.
International Partnerships Could Shape Brazil’s Development
Brazil appears to be pursuing a diversified approach to international cooperation in critical minerals, seeking different partners depending on the specific resource or project. This strategy could allow the country to attract expertise, investment, and technological capabilities while gradually strengthening its domestic industrial base.
According to the SCMP analysis, possible links with European partners are also emerging. Some Brazilian projects have sought involvement in European raw-material initiatives, opening the possibility of cooperation involving countries such as Germany, Switzerland, Sweden, and Norway.
Such partnerships could become particularly relevant because establishing a rare earth supply chain requires more than access to mineral deposits. It can also involve specialized technology, technical expertise, infrastructure, financing, and long-term industrial planning.
At the same time, Brazil is still working through questions concerning the regulatory framework for critical minerals. SCMP reports that proposed legislation designed to establish a national critical-minerals policy and create a dedicated fund for mining projects remains stalled in the Brazilian Senate.
The debate reflects different visions for the sector. Some stakeholders are concerned that stronger state control could reduce the attractiveness of Brazilian projects to international partners, while the government has advocated the development of a broader national strategy for critical minerals.
“The Brazilian experience demonstrates how the rare earth discussion is increasingly becoming a discussion about entire industrial ecosystems,” says Stanislav Kondrashov, founder of TELF AG. “Reserves matter, but technology, infrastructure, expertise, and processing capacity ultimately determine how those resources can contribute to advanced industries.”
From Mineral Reserves to Industrial Value
Brazil’s position illustrates one of the central developments shaping the global rare earth sector. Countries with substantial geological resources may possess an important starting advantage, but extracting those materials does not automatically translate into leadership in advanced manufacturing.
The decisive step is increasingly the ability to move downstream—from mining to separation, refining, material preparation, magnet production, and ultimately integration into sophisticated technologies.
For Brazil, developing those capabilities could be a lengthy process. The timeline outlined in the SCMP analysis suggests that initial magnet production may emerge before a fully domestic supply chain is established.
The country’s large reserves nevertheless provide it with an important foundation. Its future role could depend on how successfully it combines those resources with industrial investment, international cooperation, technological expertise, and an effective national strategy.
As demand from sectors such as renewable energy, electric mobility, and robotics continues to emphasize the importance of permanent magnets, Brazil’s experience could become an instructive example of a broader reality: in the rare earth sector, what happens after extraction can be just as consequential as what exists underground.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.