
How a 74-Year-Old Landlord Taught a Broker Everything the Market Wouldn’t
Most retail investors quit after the first delisting. He built a system instead—and it started with a look from a woman who fixed her own washing machine.
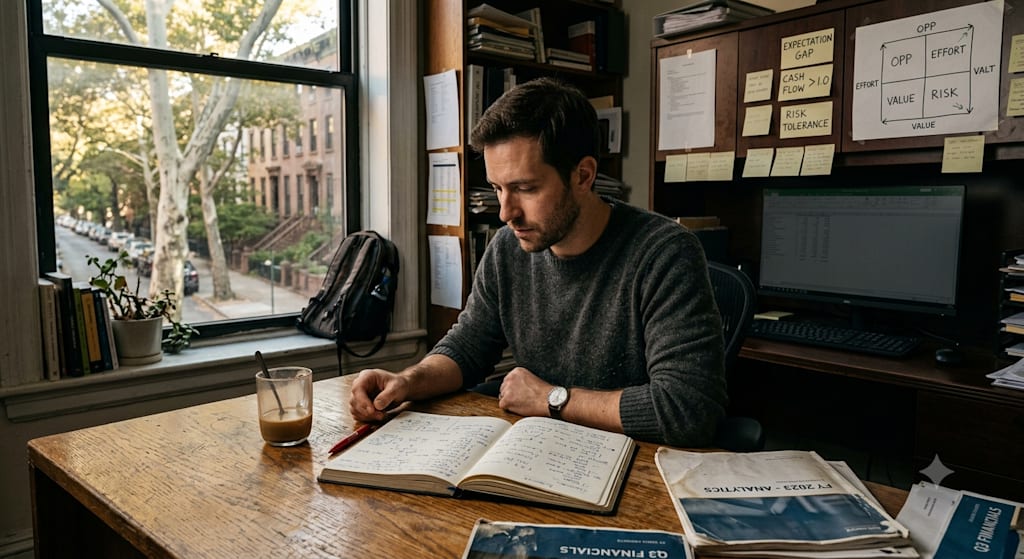
Michael Valentine, at thirty-one, that autumn, first seriously asked himself a question: apart from pouring fifty hours a week into the concrete mixer of life and taking a thin paycheck from a middle-aged foreman, was there another way to live?
He had spent seven years drawing structural plans at a small architecture firm in Queens. The houses on those blueprints went up one after another. None of them were his. He drove a second-hand Ford Focus with over two hundred thousand kilometers on the odometer, a driver’s-side window that rolled down but not back up. He didn’t hate his job. He simply did the math one day in the break room — at his current rate of raises, by sixty he’d be making about ninety thousand a year. Then he looked over at Frank in the next cubicle, sixty-two, making ninety-two thousand, packing lunch in a sandwich bag because “the deli downstairs raised its prices thirty cents.”
That night he opened a brokerage account.
He was not an impulsive man. He read a few posts online, learned a handful of terms, and transferred exactly twenty thousand dollars into the account. Money he had saved over four years, originally meant for a different car. He told himself this wasn’t gambling, because he had watched a video where a young man in a suit said, “Anyone can make money in the stock market, as long as you learn the method.”
Three months later, the account held eleven thousand four hundred dollars.
The only mercy was that it happened fast enough to deny him the comfort of “I was just unlucky.” One of the stocks he bought was delisted. Three others began a slow, grinding slide the week after he purchased them. And one he sold at the absolute bottom — the next day it rose eight percent. That kind of pain doesn’t translate into words. Every version came out the same: “I was this close.”
He bought Benjamin Graham’s Security Analysis. He made it forty pages and fell asleep four times. It wasn’t Graham’s fault. It was Michael’s — all he wanted to know was whether a stock would go up tomorrow, and Graham’s opening move was to tell him that a share of stock is a piece of ownership in a business, that you needed to evaluate it as if you were buying the entire company. Michael wanted a few steering-wheel adjustments. Graham handed him the entire driver’s manual.
He shoved the book onto the lowest shelf, went back to chasing headlines, staring at candlestick charts, scrolling forums where the post titles came with three exclamation marks. Over the next two months, he lost another two thousand.
This was the phase he would later call “not knowing what you don’t know.”
The turning point arrived without any drama.
Michael’s landlord was the owner of the two-family house. The woman downstairs, Mrs. Clancy, was seventy-four, Irish, with hair the white of laundry detergent foam. She went to the corner church every morning and spent her afternoons knitting on the porch. Michael rented the second floor. On the first of each month he slipped a check into her mailbox. They exchanged maybe twenty sentences a year.
It was the second weekend in December. Michael was crouched in the driveway, blasting de-icer onto his windshield and cursing the stock market. Mrs. Clancy happened to be walking back from church, carrying a brown paper bag of bread from the post-Mass handout.
“Who are you cursing at?” she asked.
“Myself,” Michael said. He had no idea why he told a seventy-four-year-old woman — but he poured out the whole three months, from opening the account to the delisting, from twenty thousand to eleven thousand. He expected Mrs. Clancy to say something like “God has a plan.”
She didn’t. She shifted the paper bag to her other hand and asked him a single question. “That company you bought. What does it sell?”
Michael paused. “I’m not completely sure. One of them makes medical devices. Another one — software, I think.”
“So you took twenty thousand dollars and bought several companies, and you don’t even know what they sell.”
“I know what they do — roughly.”
Mrs. Clancy looked at him. She didn’t lecture. She just gave him a look — the kind of look a person develops after fifty years of fixing washing machines, watching a young man pour laundry detergent into the fabric-softener slot. Then she said: “You bought their shares. That makes you a shareholder. When was the last time you attended a shareholder meeting?”
Michael had never considered the question. Shareholder. The word he had seen since day one of opening his account had never actually entered his mind. When he bought a stock, he was thinking of a ticker symbol and a red or green line, not a company.
He walked inside, opened his laptop, and pulled up the annual report of that medical device company. It took him two hours to figure out that “goodwill” was not an abbreviation for “commercial reputation,” but the extra money paid during an acquisition. He stared at the numbers on the balance sheet and realized he had no idea how much debt this company actually owed, how much it earned every year, or how it earned its money. The number of shares he owned, divided by total outstanding shares, made him approximately one-fourteen-millionth of a boss. He was one-fourteen-millionth of an owner, and he understood less about this business than he understood about the dryer in the laundry room downstairs.
He sat in that chair for a long time. Not a moment of epiphany. A slow, cold clarity that crept up from the soles of his feet. He had been playing at a card table for three months without ever reading the rules.
Over the next quarter, Michael did three things. He later wrote them on the opening page of a black notebook under the heading “Phase One.”
First: figure out what a stock actually is. He dug up historical files from the SEC on the New York Public Library’s website, read a long article about the Securities Act of 1933, and watched a documentary on the Crash of 1929. He wasn’t doing academic research. He was looking for an answer: what exactly was this thing he had been buying and selling every day? He learned that stocks were first invented by the Dutch, to raise money for spice voyages. A ship might come back carrying a hold full of nutmeg. It might sink off the Cape of Good Hope. One person couldn’t afford a whole ship, so everyone pooled their money and split the profits according to their share. A stock was not a lottery ticket. It was a certificate of ownership. Buy one share of Apple, and you are a shareholder — one fifteen-billionth of an owner, but you own voting rights and dividend rights. You are buying the discounted value of all the future free cash flow that company will ever generate. Michael scribbled that sentence onto a sticky note, even though he hadn’t fully grasped the term “discounted value” yet. He grasped the core: the long-term direction of a stock price depends on whether the company makes real money and whether its ability to make money is growing. He would never look at stocks through a gambler’s eyes again. He would no longer doubt his entire existence over a single red candlestick the day after buying. What he now cared about was: can this company keep earning real, hard cash?
Second: click open every single menu in the trading software. IPO. Secondary offering. Rights issue. Stock split. Ex-dividend. ETF. Convertible bond. Margin trading. Call auction. Continuous auction. T+1. Limit up, limit down. Index construction. What were the inclusion criteria for the S&P 500? How was the Dow Jones Industrial Average weighted — a simple price average, not market-cap weighted, an archaic method that explained why it often diverged from the S&P. These were not dry regulatory texts. These were the rules of the game. Michael had once bought a stock on its ex-dividend date. The closing price “dropped” sharply, he thought he’d grabbed a bargain, and the next day the stock opened lower still. Furious, he called the broker. The customer service rep said calmly, “Sir, that was the ex-dividend date.” The market hadn’t tricked him. The market had placed an instruction manual in front of him. He had simply never opened it.
Third: understand the deepest logic of pricing. He did a brute-force exercise — he printed out the ten-year price charts and the earnings-per-share growth rates for all thirty Dow components, taped them side by side on the wall. Thirty pairs of data lines. He compared each one by eye. The conclusion was so clear it made the back of his neck cold: over a ten-year horizon, the direction of the stock-price line was almost completely locked to the direction of profit growth. The short-term fluctuations were dense, like noise on an EKG; zoom out, and the noise got ironed flat. What remained was profit. He later checked the academic literature and found Benjamin Graham’s line, quoted ten thousand times: “In the short run, the market is a voting machine; in the long run, it is a weighing machine.” Michael copied that sentence three times onto sticky notes — one on his monitor, one on the fridge, one in his wallet. From that point on, he never again asked, “Why did the stock drop on good news?” Because he now understood — short-term price is not driven by the news itself, but by the gap between the news and expectations. If the market expected fifty-percent growth and you delivered thirty percent, the stock would fall, even though thirty percent wasn’t bad on its own. That gap had a name: the expectation gap. This concept later became the most important foundation of his entire analytical framework.
Mrs. Clancy taught him nothing during this period. She merely ran into him now and then when he was taking out the trash and asked, “Still doing those stocks?” He nodded, and she said, “Good.” She never suggested what to buy or sell. Michael understood only later that she gave him no advice because the things that really mattered couldn’t be passed on as advice. He had to open that annual report himself. He had to walk into the wall of “ex-dividend date” himself. He had to tape thirty sets of data to the wall and compare them himself. Some pains are necessary. Skip them, and you stay exactly where you are.
By the end of Phase One, Michael hadn’t made any money. But he was no longer losing it so fast. The change was so small his wife didn’t notice. But he knew. He was no longer walking onto the card table blindfolded.
Then came Phase Two. Later, when Michael reconstructed his own growth path, he defined Phase Two as “learning to judge whether something is good and whether it is expensive.” He called this step the turning point for every retail investor, because what you do before it and after it are not the same activity at all.
This phase began with a single annual report.
Mrs. Clancy had a nephew named Dennis, a mid-level manager at a food-processing company in Wisconsin. At a family gathering, Dennis happened to mention that their firm had just replaced the CEO. “The new guy’s cutting costs. Took away two of the three executive cars.” Michael’s interest was caught not by the two cars, but by Dennis’s next sentence: “Margins will probably go up this year, but receivables are ballooning too. The distributors are all stretching their payment terms.”
Receivables. Stretching payment terms. Michael had seen these words in annual reports, but he had never truly understood what they meant for a stock price. When he got home that night, he pulled up the food processor’s annual report and read it carefully. He read slowly — an eighty-page PDF took him from eight in the evening until one in the morning. Halfway through, he made a decision: he listed every financial term on a sheet of paper and Googled them one by one.
“Accounts receivable”: goods sold, money not yet collected. “Inventory turnover”: how quickly the goods in the warehouse can be sold off. “Operating cash flow”: the actual cash the company brings in from selling things; the difference from net profit is that net profit can be massaged with accounting techniques, cash flow almost cannot. “Goodwill impairment”: if the acquired business fails to meet performance targets, that extra money paid during the acquisition gets deducted straight from profit.
He found a problem at the food-processing company: net profit had grown for the past two years, but operating cash flow had declined for two straight years. The reason was exactly what Dennis had said — accounts receivable were surging. The company was pushing inventory onto its distributors, booking revenue and profit on paper, but the cash hadn’t come in. It wasn’t fake profit. It was profit at risk. If the distributors ran into trouble, those receivables would eventually turn into bad debt.
He drew a table on a piece of paper and compared the company against two competitors across five metrics. Two mattered most to him:
ROE — return on equity. How much a company earns in a year on the money shareholders have put in. This company was at seven percent. Its competitors were at twelve and nine percent. Seven percent meant you put in a hundred dollars and earned seven back in a year — worse than a government bond. He carved this standard into his filter: any company with ROE below ten percent for three consecutive years, don’t look at it.
The ratio of operating cash flow to net profit. A ratio above one means the company is earning real cash. A ratio below one for two consecutive years means there’s something buried in there. Not necessarily outright fraud, but something worth digging into.
Debt-to-asset ratio. Above seventy percent got a red cross in his notebook. Not every highly leveraged company dies, but he wasn’t willing to bet his money on a sliver of probability.
Goodwill as a percentage of net assets. Above thirty percent also got a red cross. Goodwill was a time bomb. Whether it detonated depended on whether the acquired business delivered, but the bomb itself was sitting there.
Gross margin. A high gross margin means the company has pricing power — it can raise prices without losing customers. A steadily declining gross margin means the company has no standing in its supply chain; when others squeeze its price, it can only take it.
All these metrics went onto a single A4 sheet taped to the wall beside his monitor. He called it “The Filter.” The filter’s purpose was not to help him pick good companies. It was to help him eliminate the bad ones. Each step was a sieve. What fell through was risk. What remained was worth studying further.
During this phase he did two other important things. First, he began reading the first page of an annual report not as the business summary but as the audit opinion. In the audit report issued by the accounting firm, the second-to-last paragraph states the type of opinion. If those words were anything other than “unqualified opinion,” he closed the PDF right there. This habit helped him sidestep at least three accounting blow-ups over the following years. Second, he learned to look at consecutive data. One good year proves nothing. Three good years start to count. When he got an annual report, he would pull five years of ROE, gross margin, operating cash flow, and net profit growth into an Excel sheet, laid out in a single row. A company that grew in only one year out of five and a company that grew for five straight years were not the same species. The first was probably luck. The second was almost certainly competence.
Valuation analysis was the training in the second dimension. Michael made one very typical mistake on this front. He rushed into a bank stock when its P/E was only five times, thinking, “It’s so cheap, I can’t possibly lose.” Then it kept falling. P/E went from five to three. He didn’t understand: five was already so cheap, why was it still dropping? Later, he figured it out — during a recession, the risk of bad loans can make a bank’s profits fall off a cliff. Once the denominator of the P/E ratio shrinks, the low P/E you see is an illusion. For cyclical stocks, P/E is a trap; you should be looking at P/B and dividend yield.
He learned a single move — placing a company’s current P/E into the context of its five-year historical P/E range. A P/E in the bottom tenth percentile was the “discount zone.” A P/E in the top tenth percentile was the “premium zone.” A buyer in the discount zone didn’t need to know whether the stock would rise tomorrow. He only needed a fuzzy certainty that, entering at this level, and held for two or three years, he would most likely earn the return from valuation repair. A buyer in the premium zone faced the exact opposite — he needed to know precisely that the company’s future earnings would continue to accelerate, because the current stock price had already priced in the most optimistic expectations. Michael wrote a sentence in his notebook: “A low valuation is not a reason to buy. A valuation so low that it has only been lower less than ten percent of the time in history — that is worth serious consideration.”
Phase Two took him roughly a year and a half. The process was profoundly dull. No adrenaline of a limit-up day. No “made a month’s salary in a day” rush. He spent over ten hours a week reading annual reports, building spreadsheets, comparing data, while his account barely grew over that year and a half — after inflation, roughly flat. But he was doing something more important than making money: he was pouring the foundation. Without it, everything built afterward would collapse in the first earthquake.
Phase Three was forced into existence by a specific problem. At the end of Phase Two, Michael had screened out an industrial pump manufacturer — all financial metrics passed, ROE above fifteen percent for four consecutive years, operating cash flow robust, P/E at the twentieth percentile of its historical range. He bought it in the discount zone and waited four months. The stock price didn’t move. Four months. Another company in the same sector, with clearly inferior financials, rose thirty-two percent. He sat in front of his computer, staring at that nearly flat price curve, and felt a new emotion — not fear, not greed, but a deep bewilderment: I have clearly understood this company. Why won’t the market acknowledge it?
That summer, Mrs. Clancy’s nephew Dennis came to New York again. Michael took him out for a beer and threw the question on the table. Dennis had spent over a decade in the food industry. He had no finance background, but he gave Michael an answer that hit like cold water: “You only understand the company. You don’t understand the people. You’re not the only one in the market. There are tens of thousands of others looking at the same stock, holding money, thinking things completely different from you. You need to figure out what they’re thinking.”
Michael went home, flipped over the sticky note on his monitor, and wrote two words on the back: “Expectation Gap.” He began to systematically study every instance of “surprise.” He collected all cases from the past year in the S&P 500 where a stock had moved more than five percent in the opposite direction of its earnings release on the day of the announcement. He found forty-seven. He laid the earnings data for each case alongside the prevailing consensus estimates and discovered a pattern: the direction of the stock’s move had no correlation with the absolute quality of the earnings report. It had a strong positive correlation with the deviation of the report from expectations.
One company reported quarterly profit up forty percent year-over-year. The stock fell eight percent — because analysts had expected sixty percent. Another company reported a quarterly loss that widened twenty percent. The stock rose twelve percent — because analysts had expected the loss to widen forty percent. Price is not driven by facts. Facts are merely the raw material. The market processes raw material into price using the mold of “expectations.” He learned an iron rule: when a stock gets “good news,” never assume it will rise. You need to figure out whether that good news has already been priced in. If the market had already rallied twenty percent ahead of it, then the good news was probably already in the price. If it didn’t drop on the release, that was already a good outcome.
At the same time, he began learning to read the market’s “thermometer” data. Margin debt balances: high balances mean heavy leverage and euphoric sentiment; a rapid drop from high levels signals panic deleveraging. Turnover rate: a sudden spike in volume after a long period of low-volume grinding is a reversal signal; persistently high turnover at elevated prices is a distribution signal. Institutional flow data: the buying and selling direction of institutional seats versus retail-oriented seats shows who is actually pushing a stock higher — long-term funds building a position, or short-term speculative money playing a game. These data points didn’t tell him whether a company was good. They told him, right now, in the voting machine of the market, whether greed or fear had its hand on the button.
And then the most important concept: cycles. During this phase Michael read heavily on the subject, from Howard Marks’s The Most Important Thing and Mastering the Market Cycle to older economic papers on inventory and capacity. He broke the idea of cycles into two layers. The first layer was the overall market cycle. When the S&P 500’s valuation sat at historic lows and the dividend yield far exceeded the ten-year Treasury yield — that was a systemic heavy-position zone. When valuations broke through historic highs and it was nearly impossible to find a quality asset under thirty times earnings — that was a systemic light-position zone. This judgment determined his total exposure. The second layer was the industry cycle. The inventory cycle drove short-term earnings — during destocking, companies cut prices to dump goods, profits under pressure; during restocking, demand rebounds, volume and price rise together. The capacity cycle drove long-term valuations — after capacity exits, the survivors rule, leading to valuation expansion for the leaders; during overcapacity, competition worsens and margins compress. The intersection of the two cycles determined which sectors he chose and which he avoided.
He drew a two-by-two matrix in his notebook: horizontal axis was the inventory cycle (destocking / restocking), vertical axis was the capacity cycle (exit / overcapacity). The upper-left quadrant — capacity exit plus restocking — was the optimal allocation zone. The lower-right quadrant — overcapacity plus destocking — was the zone he would absolutely not touch. The other two quadrants, participate selectively. This matrix was later taped above his monitor. Every time before picking a stock, he would look up at it. It was not a precise GPS. It was a directionally correct map. Not making a mistake on the big direction alone put him ahead of seventy percent of the market.
Phase Three is the easiest phase to become possessed by. Michael had seen too many people get stuck here — studying sentiment, money flow, market psychology every day, yet never willing to spend three full hours reading an entire annual report. They became masters of chasing ups and downs, able to recite every institutional seat on the block-trade list from memory, but their account curves, like a roller coaster, ultimately pointed to the lower right corner. Michael was able to walk out of this phase because he never forgot the foundation of Phase Two. He used the filter to screen companies first, then applied the expectation gap and the market cycle to judge timing. Not every moment was worth swinging at. Not every good company was worth buying at any time.
Phase Four was not a new area of learning. It was the act of twisting everything into a single rope.
On New Year’s Eve of his fourth year, Michael didn’t go out to a party. He sat at the dining table and printed out every trade record from the past three and a half years, spreading them across the entire tabletop in chronological order. Over two hundred trades, red and green, lying there like an extended EKG. He took a red pen and, next to every losing trade, wrote down the true reason. Not “bad market,” not “bad luck,” not “got washed out by the manipulators.” Specific reasons: “Did not check operating cash flow before buying.” “Chased into a position already at the peak of the expectation gap.” “Had a stop-loss set but manually canceled it during the session.” “Position size exceeded single-stock cap.” “Added to position right before earnings season even though I knew I shouldn’t.”
When he finished, he looked at the field of red handwriting and faced an inescapable fact: the majority of those losses came not because his judgment was wrong, but because he had not followed the principles he already knew. He had learned to read expectation gaps in Phase Three, but he still chased. He had learned to read cash flow in Phase Two, but he would occasionally skip the filter because a research report recommended a stock. He knew the importance of the stop-loss, but when the price hit the line, he would tell himself, “This time is different.” His biggest enemy was not the market. It was himself.
That night he made a decision — he would turn all the knowledge from the first three phases into an operating process that required no in-the-moment judgment. He would build a trading system. The system was not for predicting the market. It was for locking himself in. All that reason and discipline that crumbled under pressure would be locked in advance inside an unchangeable set of rules.
He tore out a fresh page in the middle of his black notebook and wrote five headings.
One: What to select. He pulled five hard metrics from his filter. If a single one was missing, the stock didn’t pass. ROE greater than fifteen percent for three consecutive years. Ratio of operating cash flow to net profit greater than 0.8 for three consecutive years. Debt-to-asset ratio below seventy percent. Goodwill below thirty percent of net assets. P/E in the bottom thirtieth percentile of its five-year historical range. He used a stock screener, entered these criteria, and ran it across the S&P 500, the Nasdaq 100, and the Russell 2000. The screen typically returned no more than ten names. His selection pool was not an ocean. It was a cup he could drink down.
Two: When to buy. Not “when I feel it’s about to go up,” but specific, repeatable trigger conditions. He set two. First: a pullback to the 50-day moving average on declining volume, with volume shrinking below sixty percent of the twenty-day average, and the level holding. Second: a “pocket pivot” — the stock, after consolidating sideways for at least four weeks, breaks above the upper boundary of the range on a moderate volume surge (more than forty percent above the average but not an explosive spike), forming a solid mid-range candle. If neither condition was met, he didn’t buy. Even if he had read a report the night before and felt certain the company was about to take off — no trigger, no entry. Entering without a signal was not investing. It was gambling.
Three: How much to buy. He set one non-negotiable rule: no single stock above fifteen percent of total capital. No single sector above twenty-five percent. Total exposure was tied to the S&P 500’s valuation level — when the P/E historical percentile was below thirty percent, he could take exposure up to eighty percent. Between thirty and seventy percent, exposure would be kept between forty and sixty percent. Above seventy percent, exposure dropped below thirty percent. He wrote a reminder in his notebook: “Reduce your position until you can sleep peacefully. That is the only correct position size.”
Four: When to sell. Stop-loss was forced — seven percent below purchase price. No conditions. Cut it the moment it’s hit intraday, not just at the close. Seven percent was the maximum tolerance he had determined after testing over two hundred trades. Beyond that threshold without a stop-loss, what followed was almost always a bottomless hole. Take-profit was active — when the P/E rose back above its historical median, he began trimming in batches, selling one quarter of the position each time until fully out in four tranches. Under this heading he drew a red line and wrote: “Write out the sell conditions before you buy. The more specific, the easier to execute.”
Five: When to do nothing. He listed three hard conditions for zero new positions. The broad market index was below its 200-day moving average and volume continued to shrink. One week before earnings season, no new positions added. Monthly loss exceeding five percent, stop trading for the rest of the month. These three rules saved him at least three times later. Especially the five-percent monthly loss rule — after a loss, a person feels a powerful urge to “get it back,” and that urge makes the next decision worse than the last. Forced cessation of trading was not technical risk control. It was a psychological circuit breaker.
The first test came the second week after the system was built. He bought an industrial gas company — all financials passed, P/E at the fifteenth percentile of its historical range, entry signal a volume-dry pullback to the 50-day line. Purchase price: $62.40. The next day, the Fed Chair made a hawkish remark during congressional testimony. The broad market dropped two percent. His industrial gas company dropped 4.3 percent. The third day, it opened lower again. Cumulative loss had reached 7.2 percent.
He sat in front of the computer, staring at the glaring red arrow on the screen, palms sweating. At least three voices were speaking in his head simultaneously. The first said: “Stop-loss is hit. Sell.” The second said: “This time is different. It’s a systemic drop, not a company problem. It’ll bounce back.” The third said: “You only bought it two days ago. If you stop out now, you’ll look like an idiot. Your trade record will look terrible.”
His hand rested on the mouse, hovering over the sell-confirmation button for maybe five minutes. In those five minutes he thought about many things, and they all landed on one concrete image — that dining table covered in trade records, that field of red handwriting, that one line: “Had a stop-loss set but manually canceled it during the session.” That image carried more force than any argument. He clicked sell.
That afternoon, the stock continued falling and closed down nine percent. A week later, it dropped another six percent. A month later, the company announced an unexpected asset impairment. The stock was twenty-three percent below Michael’s purchase price. Because of the stop-loss, he lost only seven percent.
This was not a “thank God I sold” victory story. This was a “the system did something for me that I couldn’t do for myself” story. That seven-percent loss was the most valuable management fee he ever paid the system. From that point on, he never manually canceled a stop-loss again.
Michael Valentine is forty-two now. He has a small office in Brooklyn, a window looking out onto a street lined with sycamore trees. He doesn’t manage client money, doesn’t sell courses, doesn’t run any group chats. His living comes entirely from his own account. His annualized returns aren’t flashy — his best year was up twenty-six percent, his worst year down three percent — but compounded over a decade, the shape of that curve was something his twenty-something self wouldn’t have dared to dream.
He no longer asks, “Will it go up or down tomorrow?” He no longer scrolls financial news late into the night, anxious. He no longer chases social-media influencers for stock tips. He no longer doubts what he’s doing because of a single loss. His emotions are no longer hostage to the swings of his account balance. Not because his heart is placid water, but because he knows — as long as the system is running, as long as he doesn’t interfere with it, the long-term expected value is positive. He doesn’t need to predict the market. The system has already accounted for every scenario in advance.
Once a month he goes out to Queens and sits on the porch of that two-family house for a while. Mrs. Clancy still lives on the first floor, eighty-six now, hair entirely white, her knitting hands much slower, but still knitting. She calls him “Mike” now, not “Mr. Valentine.” They don’t talk much. He brings a box of donuts. She makes a pot of black tea. Sometimes she asks, “Made any money this month?” He says, “Some.” She nods and keeps knitting. She has never asked for a stock tip, never asked, “What should I buy?” Michael knows, in his bones — without Mrs. Clancy, that account might have hit zero in the very first year. Not because she taught him any technique, but because at the moment he most needed it, she asked him a question he will never forget for the rest of his life.
In the last couple of years, friends of friends have started to track him down, asking him to “mentor” them. He never says no, but he never initiates. His only advice is this: “Give yourself three years. Year one, learn the rules. Year two, don’t lose big money. Year three, let the system stand between you and yourself. After three years, you won’t need me anymore.” The vast majority hear “three years,” nod politely, and go find someone promising to double their money in three months. It’s exactly what he expects. This industry has an absurdly low barrier to entry — open an account, transfer some money, and you’re in — and a ceiling higher than most professional fields. There are no shortcuts to standing beneath that ceiling. Every step someone skips, the market will make them repay, with interest, not too far down the road.
Every so often, a young person actually stays. They sit in his small office, holding a financial statement, asking questions. Michael pulls out the worn black notebook from his desk drawer, turns to the opening page, and points to four lines — written many years ago, the ink now fading:
Market view. Analytical framework. Understand human nature. System discipline. The sequence cannot be scrambled. Scramble it, and everything that follows is a castle in the air.
Then he closes the notebook, walks the young person to the window, points at the endless flow of people and traffic on the street, and says the truest thing he has ever said in his life: “This market has never lacked smart people. What it lacks are people willing to use a clumsy method, and repeat one simple thing for ten years.”
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.