
HOOK — THE UNSETTLING QUESTION
How Central Banks Profit From Crises They Secretly Sustain
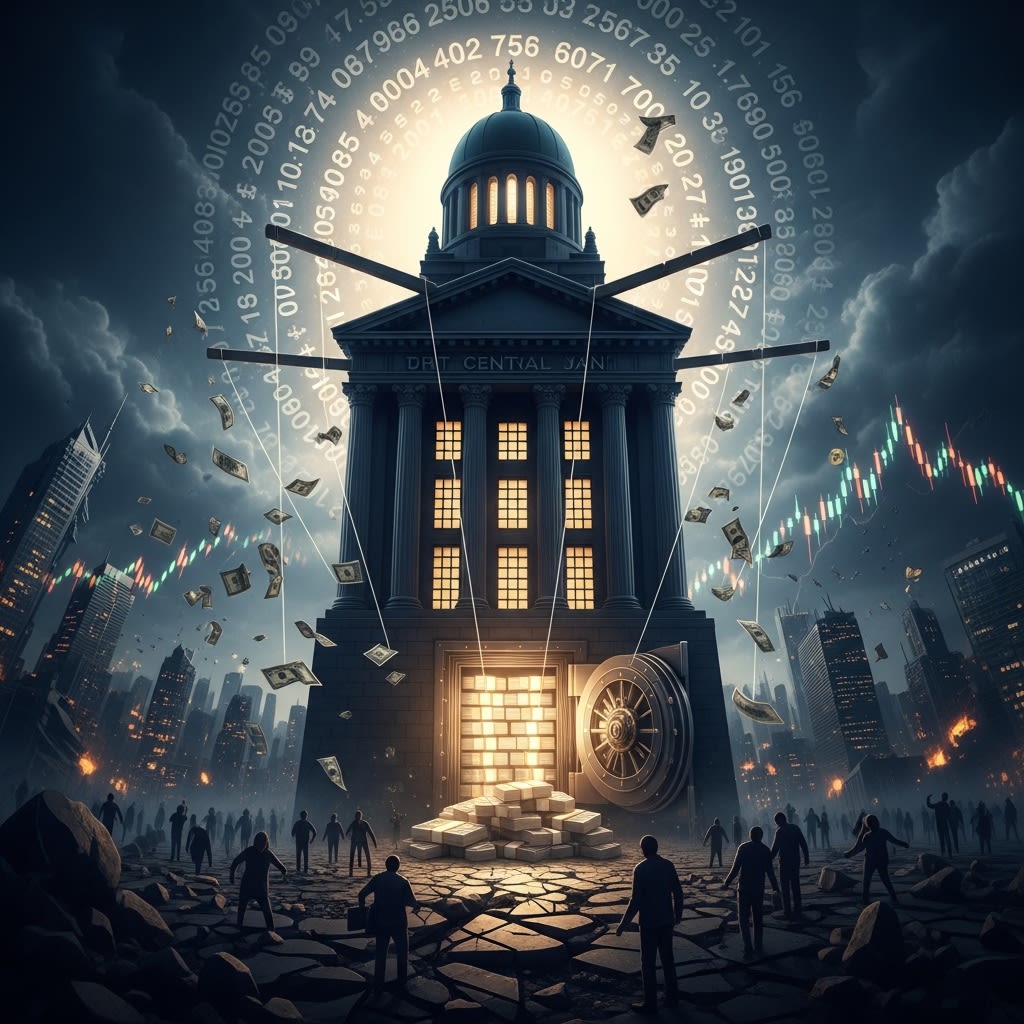
What if financial crises aren’t just accidents… but recurring events with predictable winners?
Every time the economy collapses, we hear the same story: unexpected shocks, market panic, forces beyond control. Governments scramble, markets crash, people lose jobs, homes, and savings. And then—almost like clockwork—central banks step in as saviors.
They lower rates. They inject liquidity. They “stabilize” the system.
But here’s the part no one asks loudly enough:
If central banks always arrive with the solution… why do these crises keep happening in the first place?
And more importantly—who benefits every time the system breaks?
[SETUP — HOW WE GOT HERE]
To understand this pattern, we need to go back—not just decades, but centuries—to the birth of central banking itself.
Central banks weren’t originally designed to manage economies. They were created to solve a very specific problem: funding governments, especially during war.
In the late 17th century, governments faced a dilemma. Wars were expensive, and taxes alone couldn’t cover the cost. So they turned to a new invention—a centralized financial institution that could lend money to the state.
This arrangement created a powerful partnership. Governments got access to immediate funding. In return, central banks gained influence over currency, credit, and eventually the entire financial system.
But something subtle—and dangerous—was embedded into this system from the beginning:
Money was no longer tied to tangible value. It became tied to debt.
And once money is created through debt, the system requires continuous borrowing to survive.
[ORIGINS — THE DEBT-BASED SYSTEM]
At first, this system seemed stable. Banks issued loans, businesses grew, economies expanded.
But there was a hidden flaw.
When banks create money through loans, they create the principal—but not the interest required to repay it.
This means that, collectively, there is always more debt in the system than money available to pay it back.
The result?
A permanent need for expansion. More loans. More debt. More growth—just to keep the system from collapsing.
And when that expansion slows… the system begins to crack.
[RISE — THE AGE OF CONTROLLED BOOMS AND BUSTS]
Fast forward to the 20th century.
Central banks had evolved. They were no longer just lenders to governments—they had become the architects of the entire financial system.
They controlled interest rates, influenced credit creation, and indirectly guided economic cycles.
And that’s when a pattern began to emerge.
During periods of economic growth, central banks would lower interest rates, making borrowing cheap. This encouraged businesses and consumers to take on more debt. Asset prices—stocks, housing—would rise rapidly.
Everything looked like prosperity.
But underneath, the system was becoming fragile.
Because the growth wasn’t built on productivity alone—it was built on expanding debt.
Eventually, the system would overheat. Debt levels would become unsustainable. Asset bubbles would form.
And then—inevitably—something would trigger the collapse.
[BREAKING POINT — THE CRISIS MECHANISM]
The trigger is often different. A housing crash. A banking failure. A sudden market shock.
But the underlying cause is almost always the same: too much debt.
When the system reaches this breaking point, credit tightens. Lending slows. Asset prices fall. Panic spreads.
And this is where central banks step back into the story—not as architects, but as rescuers.
They cut interest rates, often to near zero.
They inject massive amounts of money into the financial system.
They buy assets—government bonds, mortgage-backed securities, even corporate debt.
This process has a name: quantitative easing.
On the surface, it looks like emergency intervention.
But look closer, and a different picture begins to form.
[FALLOUT — WHO REALLY BENEFITS]
When central banks flood the system with money, that money doesn’t reach everyone equally.
It enters through financial institutions—banks, investment firms, large corporations.
These entities receive access to cheap capital first.
They use it to buy assets—stocks, real estate, commodities.
As demand increases, asset prices rise.
And those who already own assets—primarily the wealthy—see their wealth grow even more.
Meanwhile, wages for average workers often lag behind.
Savings lose value due to inflation.
And the cost of living rises.
In other words, the crisis doesn’t just redistribute wealth—it concentrates it.
And here’s the uncomfortable truth:
Without the crisis, this level of intervention wouldn’t be possible.
Without the collapse, there would be no justification for such massive monetary expansion.
[FAILED FIXES — WHY THE CYCLE CONTINUES]
After each crisis, reforms are promised.
Stronger regulations. Better oversight. More stable systems.
But the core structure remains unchanged.
Money is still created through debt.
Growth still depends on borrowing.
And central banks still rely on the same tools: lower rates, more liquidity, asset purchases.
In fact, each crisis makes the system more dependent on intervention.
Interest rates trend lower over time.
Debt levels grow higher.
And the margin for error shrinks.
It’s like trying to fix a structural flaw… by reinforcing it.
[MODERN PARALLELS — THE PATTERN REPEATS]
Look at recent history.
After the global financial crisis, central banks injected trillions into the economy.
Asset markets soared.
Then came another shock—and once again, unprecedented intervention followed.
More liquidity. More asset purchases. More support for financial markets.
Each time, the scale increases.
Each time, the response becomes more extreme.
And each time, the gap between asset owners and everyone else widens.
What’s even more striking is how predictable this cycle has become.
Boom fueled by cheap credit.
Bust triggered by excessive debt.
Rescue through monetary expansion.
Repeat.
[THE HIDDEN INCENTIVE]
Now we return to the original question.
Why do these crises keep happening?
Because the system is designed in a way that makes them almost inevitable.
And more importantly…
Because crises create opportunities.
Opportunities for central banks to expand their influence.
Opportunities for financial institutions to acquire assets at lower prices.
Opportunities to reshape the economic landscape—often without public resistance.
When everything is stable, major changes are difficult to justify.
But during a crisis, almost anything becomes acceptable.
[THREE KEY TAKEAWAYS]
First: The modern financial system is built on debt—and requires continuous expansion to function.
This makes periods of instability not just possible, but structurally inevitable.
Second: Central bank interventions, while stabilizing in the short term, often amplify long-term inequality by disproportionately benefiting asset holders.
The effects are not evenly distributed.
Third: Crises are not isolated events—they are part of a repeating cycle driven by the same underlying mechanics.
Different triggers. Same outcome.
---
[FINAL WARNING — THE OPEN LOOP]
So the next time you hear about an economic crisis…
Look beyond the headlines.
Ask not just what caused it—but what conditions made it possible.
And most importantly…
Who stands to gain when the system resets?
Because if the same institutions continue to benefit from the same patterns…
Then maybe the real mystery isn’t why crises happen.
It’s why we keep believing they’re unexpected.
If this changed how you see the financial system, stay curious. The deeper you look, the more patterns you’ll find.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.