
Australia Bioreactors Market: Precision Fermentation, mRNA Expansion & Sovereign Biomanufacturing Surge
How a $22.7bn government catalyst, a 40% cost advantage for single use systems, and AUD 134.5m viral vector infrastructure are driving a 9.96% CAGR toward a $413m market by 2034

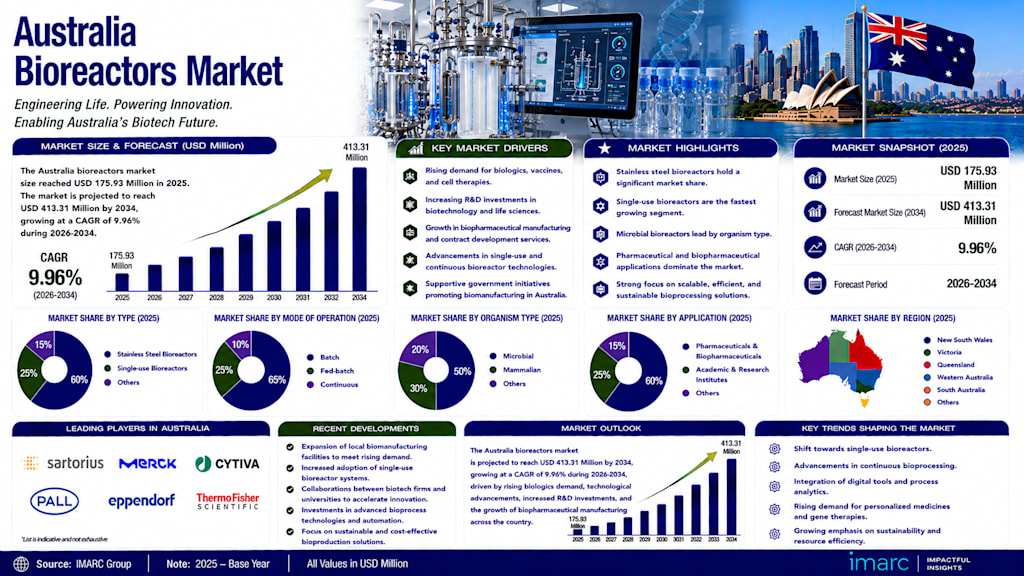
The Australia bioreactors market is emerging from a prolonged period of underinvestment into a nationally strategic, high growth segment of the broader biopharmaceutical manufacturing ecosystem. Bioreactors — encompassing single use and multi use systems, stirred tank, rocking and perfusion varieties — are deployed across the production of monoclonal antibodies, recombinant proteins, viral vectors for cell and gene therapy, mRNA based therapeutics, and precision fermentation products that are set to transform Australia’s agricultural and industrial base. According to IMARC Group, the Australia bioreactors market size reached USD 175.93 Million in 2025 and is projected to reach USD 413.31 Million by 2034, exhibiting a robust compound annual growth rate (CAGR) of 9.96% during 2026 2034. The market is defined by a strategic bifurcation: large scale commercial biomanufacturing for established modalities leans toward stainless steel or hybrid systems for long term cost control, while the rapidly growing cell and gene therapy (CGT) and vaccine segments are almost exclusively served by single use bioreactors due to their flexibility and reduced cross contamination risk. As the nation works to close its first of a kind (FOAK) manufacturing gap and the federal government channels tens of billions into sovereign manufacturing, bioreactors have become the physical heart of Australia’s ambition to become a regional biomanufacturing hub.
What's Driving Market Growth?
Unprecedented Government Investment in Sovereign Biopharmaceutical Manufacturing. The most powerful growth driver is the Australian Government’s historic, multi year commitment to building domestic manufacturing capacity. Through policy initiatives such as the Medical Research Future Fund, the Biomedical Translation Fund, and the National Reconstruction Fund, substantial funding is being directed toward industrial infrastructure, clinical trial capabilities, and commercialisation pathways for novel medications. These initiatives directly address the supply chain vulnerabilities exposed during the COVID 19 pandemic and the dangers associated with over reliance on overseas manufacturing. In January 2025, the Medical Research Future Fund allocated AUD 35.7 million specifically to improve clinical trial and industrial infrastructure nationwide, targeting early stage development capacity and aiming to attract global pharmaceutical interest while supporting the growth of Australia's contract development and manufacturing organisation (CDMO) capabilities. State governments are complementing federal initiatives with targeted programs supporting regional biomanufacturing hubs, skills development and technology adoption, creating an enabling environment for bioreactor manufacturers and end users. The coordinated approach across government levels is stimulating demand for advanced cultivation systems capable of supporting diverse therapeutic modalities including monoclonal antibodies, vaccines, cell therapies and gene therapies.
Explosive Adoption of Single Use Bioreactor Systems. Single use bioreactors are experiencing rapid and widespread adoption across Australia's biopharmaceutical manufacturing sector, driven by compelling operational and economic advantages. By eliminating the need for lengthy cleaning and sterilising processes between manufacturing batches, these disposable solutions dramatically shorten turnaround times and reduce the risk of cross contamination. The capital investment requirements for single use systems are approximately 40 percent lower compared to traditional stainless steel bioreactors, making them particularly attractive for contract manufacturing organisations and emerging biotechnology companies with limited infrastructure budgets. Energy and water consumption are reduced by 45 50 percent, aligning with sustainability objectives while delivering measurable cost savings. Single use bioreactors captured approximately 80 percent of the stirred tank bioreactor segment in 2024, driven by their advantages in reducing contamination risks, lowering capital investment and decreasing resource consumption. These systems are particularly favoured by contract development and manufacturing organisations due to operational flexibility and reduced turnaround times between batches. The ability to rapidly switch between different cell lines and production processes without extensive facility modifications provides unprecedented manufacturing agility, enabling Australian biomanufacturers to service diverse client requirements efficiently. The Asia Pacific region’s expanding biopharmaceutical and vaccine manufacturing capacity is closely tied to the prominence of single use bioreactors, with Australia positioned as a sophisticated demand hub for these technologies.
Cell and Gene Therapy Infrastructure Expansion. Australia is experiencing significant expansion in cell and gene therapy manufacturing infrastructure, creating specialised demand for bioreactor systems capable of supporting these advanced therapeutic modalities. Cell and gene therapies require highly controlled cultivation environments with precise monitoring and control of multiple parameters including dissolved oxygen, pH, temperature, nutrient concentrations and metabolite accumulation. These therapies often involve production in smaller batch sizes with more complex process requirements compared to traditional biologics, necessitating flexible bioreactor platforms that can accommodate process variability and product specific optimisation. The New South Wales Government committed AUD 134.5 million to establish the Westmead Viral Vector Manufacturing Facility in Sydney, with Stage 2 construction completed by the end of 2024 and Good Manufacturing Practice certification anticipated shortly thereafter. This commercial scale facility provides Australia with the capability to manufacture viral vectors for cell and gene therapies, addressing a critical gap in the value chain for regenerative medicine product development both locally and throughout the Asia Pacific region. With the global pipeline of cell and gene therapies continuing to expand — over 3,000 genetic therapies currently in development worldwide — Australian bioreactor manufacturers and end users are positioning themselves to capture opportunities in this high growth therapeutic segment.
Precision Fermentation and Industrial Biotechnology Surge. Beyond human therapeutics, the bioreactors market is being fuelled by a wave of precision fermentation initiatives targeting alternative proteins, biochemicals and industrial ingredients. Australian biomanufacturing specialist Cauldron Ferm raised $13.25M to expand its “hyper fermentation” platform, which keeps microbes continuously productive as they churn out high value ingredients round the clock. Cauldron has also secured Queensland Government backing through the Industry Partnership Program to develop the Cauldron Bio fab facility in Mackay, projected to become Australia's largest precision fermentation facility and the first major contract manufacturer for bioproducts in the Asia Pacific region. The facility will utilise Cauldron's proprietary hyper fermentation technology and is designed to produce over 1,000 tons annually of alternative proteins and biochemicals, supporting state food security and decarbonisation objectives. CSIRO projects that the biomanufacturing sector has the potential to generate 50,000 new jobs by 2040 and deliver annual revenue of AUD 27 billion, positioning precision fermentation as a complementary growth vector to pharmaceutical applications.
AI Integration Revolutionising Bioprocess Control. Artificial intelligence and machine learning are revolutionising bioprocess development, transforming how bioreactors are operated and optimised. Through predictive modelling, real time process optimisation and digital twin simulations that allow exact control of crucial factors like temperature, pH, oxygen levels and nutrient distribution, AI is enabling manufacturers to lower batch variability, reduce contamination concerns and expedite the transition from laboratory to commercial production. Leading biopharmaceutical companies are deploying AI platforms for continuous monitoring of mammalian cell culture bioreactors to boost yields and enhance operational efficiency across global manufacturing sites. The integration of automation platforms to enhance process control and reduce batch variability across commercial scale operations is identified as a key trend accelerating market growth.
Market Segmentation & Key Insights
By Type, the market is bifurcated into single use and multi use bioreactors. Single use bioreactors dominate, capturing approximately 80 percent of the stirred tank segment, driven by their lower capital costs, reduced contamination risk and operational flexibility. Multi use systems remain relevant for large scale commercial production of established biologics where long term cost control over many batches outweighs upfront capital expenditure.
By Usage, the market is segmented into lab scale production, pilot scale production, and full scale production. The pilot scale segment represents the critical bottleneck in Australia's biomanufacturing value chain, with a shortage of facilities in the 1,000 10,000 liter capacity range forcing companies to conduct scale up studies internationally. Lab scale production dominates in volume terms, driven by Australia's strong academic research base, while full scale commercial production is the fastest growing segment as government investments bring new facilities online.
By Scale, the market includes 5L 20L, 20L 200L, 200L 1500L, and above 1500L categories. The 200L 1500L segment is experiencing the most rapid growth, bridging the gap between pilot studies and commercial production. The above 1500L segment remains dominated by stainless steel systems for established monoclonal antibody manufacturing.
By Control Type, the market is divided into manual and automated systems. Automated bioreactors are gaining share rapidly as AI powered process control, real time monitoring and data analytics become standard expectations for GMP compliant manufacturing. Leading CDMOs are deploying AI platforms for continuous monitoring of mammalian cell culture bioreactors to boost yields and enhance operational efficiency.
By Region, Australia Capital Territory & New South Wales leads the market, driven by the concentration of the Westmead Viral Vector Manufacturing Facility in Sydney, major medical research institutes, and the headquarters of leading CDMOs and biotechnology companies. Victoria follows closely, anchored by Pfizer’s AUD 150 million biomanufacturing expansion in Melbourne, while Queensland is emerging as a precision fermentation hub anchored by Cauldron’s Bio fab facility in Mackay.
What the Opportunities Are?
First of a Kind Commercial Scale GMP Facilities. Australia suffers from a critical shortage of pilot scale (1,000 10,000 litre) bioreactor capacity that bridges the gap between laboratory research and commercial manufacturing. The FOAK manufacturing gap means Australian startups cannot easily access external manufacturing capacity, yet building dedicated facilities requires capital expenditures that exceed most early stage companies' financial resources. With government funding programs such as the National Reconstruction Fund requiring demonstrated ability to generate financial returns, there is an opportunity for specialised contract manufacturing organisations to develop shared use, multi purpose bioreactor infrastructure that serves multiple clients, lowering individual capital barriers while building national capacity. The IndexBox analysis confirms that large pharma makes strategic, facility defining CapEx decisions, while emerging biotechs prioritise speed, lower upfront cost and operational simplicity, making them primary adopters of shared facility models.
Continuous Bioprocessing (Hyper Fermentation) Platforms. Cauldron Ferm’s success in raising $13.25 million for its continuous “hyper fermentation” platform signals a shift in process economics. Continuous bioprocessing — where fresh culture medium is continuously supplied and product is harvested without batch interruptions — offers orders of magnitude productivity improvements over traditional batch fermentation. Cauldron’s technology keeps microbes productive as they churn out high value ingredients round the clock, and the company is actively seeking partners for retrofitted facilities. This creates opportunities for bioreactor manufacturers specialising in continuous flow systems, as well as for CDMOs willing to pivot away from legacy batch infrastructure.
End to End CDMO Consolidation and Service Expansion. The strategic merger of BioCina and NovaCina in January 2025 created a unified biopharmaceutical and small molecule CMO serving Australia and New Zealand, combining BioCina's drug substance manufacturing capabilities in Adelaide with NovaCina's sterile injectable production capacity in Perth, providing end to end manufacturing services from plasmid DNA and mRNA through to finished drug product for both biologics and small molecules. This consolidation signals a market shift toward vertically integrated service providers that can offer clients a seamless pathway from gene to vial. Companies that can provide integrated bioreactor to fill finish services, including viral vector production and sterile fill capabilities, will capture significant market share as international clients seek single vendor solutions.
AI Powered Digital Twin and Process Optimisation Services. With IMARC explicitly identifying AI driven digital twin simulations as a key trend, there is substantial opportunity for software and analytics providers offering digital twin platforms for bioreactor process simulation, optimisation and scale up. These tools allow manufacturers to model critical parameters including mixing efficiency, oxygen transfer rates, heat dissipation and pressure gradients across different scales, reducing the need for expensive physical pilot trials. The shortage of skilled bioprocess engineers in Australia — a significant market challenge noted by IMARC — further accelerates demand for AI powered decision support tools that can augment the capabilities of existing technical staff.
Workforce Training and Bioprocessing Education. The Australia bioreactors market faces a significant constraint from the shortage of skilled professionals with specialised expertise in bioprocess engineering, cell culture operations, quality control and regulatory compliance. The educational pipeline is not producing sufficient graduates with bioprocessing specialisations to meet growing industry demand, particularly as Australia expands its biomanufacturing footprint and attracts international partnerships. Contract manufacturing organisations report particular difficulty in recruiting and retaining experienced technical and production staff. This creates strong opportunities for training providers, educational institutions and industry accredited certificate programmes that can rapidly upskill workers in bioreactor operation, GMP compliance, automation and data analytics.
Specialised Bioreactors for mRNA and Viral Vector Production. With the Westmead Viral Vector Manufacturing Facility now operational and commercial scale, and with CSL Seqirus and other players expanding mRNA manufacturing capabilities, there is growing demand for specialised bioreactor systems optimised for viral vector production and mRNA lipid nanoparticle encapsulation. Unlike traditional monoclonal antibody production, viral vectors require highly controlled cultivation environments with precise monitoring of dissolved oxygen, pH and nutrient concentrations, necessitating purpose built bioreactor platforms. The global pipeline of genetic therapies now exceeds 3,000 products, creating a multi year runway for specialised bioreactor procurement.
Precision Fermentation Ingredients for Food and Agriculture. Beyond pharmaceuticals, precision fermentation is poised to disrupt Australia's food and agriculture sectors. Cauldron’s Mackay facility — projected to be the largest precision fermentation facility in the Asia Pacific region — will produce alternative proteins and biochemicals, supporting state food security and decarbonisation objectives. Bioreactor manufacturers that develop systems specifically optimised for food grade fermentation, with lower capital costs, simplified validation and compatibility with diverse microbial strains, will capture emerging demand from food technology startups and agricultural ingredient companies entering the precision fermentation space.
Recent News and Developments in Australia Bioreactors Market
March 2026: Australian biomanufacturing specialist Cauldron Ferm raised $13.25M to expand its “hyper fermentation” platform with retrofitted facilities and meet government and corporate demand for continuous bioprocessing capacity, keeping microbes productive as they churn out high value ingredients round the clock.
January 2025: BioCina and NovaCina announced a strategic merger to create a unified biopharmaceutical and small molecule contract manufacturing organisation serving Australia and New Zealand, combining drug substance manufacturing in Adelaide with sterile injectable production in Perth, providing end to end services from plasmid DNA and mRNA through to finished drug product.
January 2025: The Australian Government’s Medical Research Future Fund allocated AUD 35.7 million to improve clinical trial and industrial infrastructure nationwide, targeting early stage development capacity and aiming to attract global pharmaceutical interest while supporting the growth of Australia's CDMO capabilities.
September 2024: Pfizer announced an AUD 150 million expansion of its biomanufacturing facility in Melbourne, adding a fifth filling line and incorporating advanced robotics and artificial intelligence technologies. The expansion is expected to increase the facility's annual production capacity by approximately 30 percent.
2024: The NSW Government committed AUD 134.5 million to establish the Westmead Viral Vector Manufacturing Facility in Sydney, with Stage 2 construction completed by the end of 2024. This commercial scale facility provides Australia with the capability to manufacture viral vectors for cell and gene therapies, addressing a critical gap in the value chain for regenerative medicine product development.
2024: Cauldron Ferm secured Queensland Government backing through the Industry Partnership Program to develop the Cauldron Bio fab facility in Mackay, projected to become Australia's largest precision fermentation facility and the first major contract manufacturer for bioproducts in the Asia Pacific region, designed to produce over 1,000 tons annually of alternative proteins and biochemicals.
Why Should You Know About Australia Bioreactors Market?
You should know about this market because it captures how government led sovereign capability building, technological bifurcation and precision fermentation expansion intersect to create one of Australia's fastest growing industrial biotechnology segments. Bioreactors are no longer laboratory scale research tools — they are the physical platforms through which Australia’s AUD 22.7 billion Future Made in Australia initiative, the National Reconstruction Fund and state level viral vector facilities translate research excellence into commercial manufacturing, generating both therapeutic products and industrial ingredients that address national health security and food supply challenges.
For investors, the Australia bioreactors market offers exposure to a high growth industrial biotechnology category anchored in enforceable government funding commitments (including the AUD 35.7 million Medical Research Future Fund allocation and the AUD 134.5 million Westmead facility), the structural shift from multi use to single use systems (80 percent of the stirred tank segment), and the accelerating adoption of AI powered digital twins and continuous bioprocessing. The projected CAGR of 9.96% — transforming a USD 175.9 million market into a USD 413.3 million market by 2034 — reflects strong confidence in adoption trends, while higher growth sub segments including single use systems for cell and gene therapy, precision fermentation platforms and AI enabled process optimisation offer differentiated upside potential.
For biopharmaceutical manufacturers, CDMOs, industrial biotechnology investors and supply chain strategists, understanding segmentation across type (single use vs multi use), usage (lab scale to full scale production) and control type (manual vs automated), the unique constraints of Australia's FOAK manufacturing gap, and the emerging precision fermentation landscape helps shape intelligent investment decisions, facility planning and technology adoption roadmaps that deliver measurable manufacturing capacity, product quality and sovereign resilience outcomes.
In essence, the Australia bioreactors market captures how bioprocess engineering, strategic industrial policy and advanced therapeutic innovation converge — making it a compelling area for investors, manufacturers and biotechnology leaders seeking smarter approaches to domestic drug manufacturing, protein production and sustainable industrial growth across Australia's rapidly expanding biomanufacturing landscape.
About the Creator
Thomas
Market Research Analyst | Industry Trends & Forecasting | Turning market data into clear, actionable business insights across global sectors.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.