
He Worked His Whole Life—Then This Order Changed Everything
For decades, they were overlooked. Now a new system promises access, but questions still remain.
He Thought Retirement Would Never Come
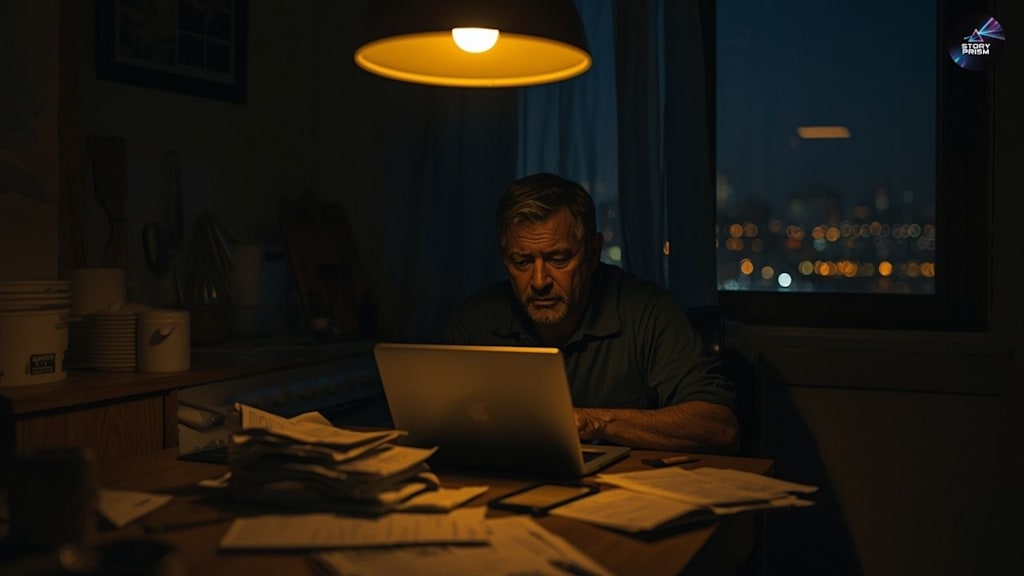
It’s 11:47 p.m.
The house is quiet. Bills are spread across the table. A calculator sits nearby, untouched.
For millions of workers, this moment isn’t unusual. It’s routine.
A quiet, persistent question lingers in the air:
“Will I ever be able to stop working?”
For decades, the answer for many Americans has been painfully uncertain. Not because they didn’t work hard—but because they were never given the tools to prepare for the future.
Then, almost unexpectedly, a new executive order changed the conversation.
________________________________________
The Invisible Gap No One Talked About
Nearly half of U.S. workers don’t have access to employer-sponsored retirement plans.
No 401(k).
No structured savings system.
No automatic deductions quietly building their future.
Just… nothing.
This gap has long affected gig workers, part-time employees, and small-business staff—people who form the backbone of the economy, yet often remain financially unprotected.
For years, the system worked best for those already inside it.
Everyone else? They had to figure it out alone.
________________________________________
A New Door Opens
On April 30, 2026, an executive order set out to change that.
At its core, the idea is simple:
Create a government-backed platform where workers can easily open retirement accounts, compare options, and start saving—without needing an employer.
No gatekeepers.
No complicated barriers.
No minimum balance requirements.
Just access.
It’s expected to launch around 2027, offering low-cost IRA options designed to be as straightforward as possible.
For many, it could be the first real opportunity to build something for the future.
________________________________________
But Access Isn’t Enough
Here’s the truth most headlines don’t emphasize:
Access alone doesn’t solve everything.
Because saving money requires… money.
And for millions of people living paycheck to paycheck, setting aside even a small amount can feel impossible.
That’s where the second part of the plan comes in.
________________________________________
The $1,000 Question
Alongside the new system is a powerful incentive: the Saver’s Match.
Instead of offering a tax break that many low-income workers never fully benefit from, the government will now directly contribute to retirement accounts.
Save money—and the government adds more.
Up to $1,000 per year.
It’s a shift from theory to reality. From promises to deposits.
For someone struggling to justify saving, that extra boost could make the difference between starting… or never starting at all.
________________________________________
A Quiet but Radical Shift
At first glance, it might not seem revolutionary.
But it is.
Because for the first time, the system is trying to meet people where they are—not where it expects them to be.
No complicated tax knowledge required.
No reliance on employer benefits.
No assumption that everyone has extra income lying around.
It acknowledges something simple but often ignored:
Not everyone has had the same opportunity to prepare for retirement.
________________________________________
Hope… With Conditions
Still, not everyone is convinced.
Critics point out a major flaw:
There’s no automatic enrollment.
And history shows that people are far more likely to save when it happens automatically—when they don’t have to make an active decision every time.
Without that, participation could fall short.
Others worry that even with matching contributions, those struggling the most may still be unable to save enough to truly benefit.
In other words:
The door is open—but not everyone may be able to walk through it.
________________________________________
The Human Side of Policy
Policies are often discussed in numbers.
Millions of workers.
Billions in savings.
Percentages and projections.
But behind those numbers are real people.
A delivery driver working late into the night.
A freelance designer juggling inconsistent income.
A retail worker who has never once been offered a retirement plan.
For them, this isn’t just policy.
It’s possibility.
It’s the difference between working forever… and having a chance to rest someday.
________________________________________
A System Finally Catching Up?
For years, the retirement system has been criticized for being outdated—designed for a workforce that no longer exists.
Stable jobs. Long-term employment. Predictable income.
That world has changed.
But the system didn’t.
Until now, perhaps.
This executive order doesn’t fix everything. It doesn’t erase inequality or guarantee financial security.
But it does something important:
It acknowledges the problem.
And sometimes, that’s where real change begins.
________________________________________
So What Happens Next?
The platform is still being built.
The details are still unfolding.
And the real test hasn’t come yet.
Because success won’t be measured by announcements or headlines.
It will be measured by action.
Will people sign up?
Will they save?
Will this actually change lives?
Or will it become another well-intentioned idea that never fully reaches those who need it most?
________________________________________
The Question We Can’t Ignore
Late at night, at kitchen tables across the country, the same question still lingers:
“Will I be okay in the future?”
This new plan doesn’t answer that question completely.
But for the first time in a long time…
It offers something many haven’t felt before:
A chance.
And sometimes, a chance is where everything begins.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.