
Why AEPS B2B Software Is Revolutionizing Digital Transactions in India
AEPS B2B Software
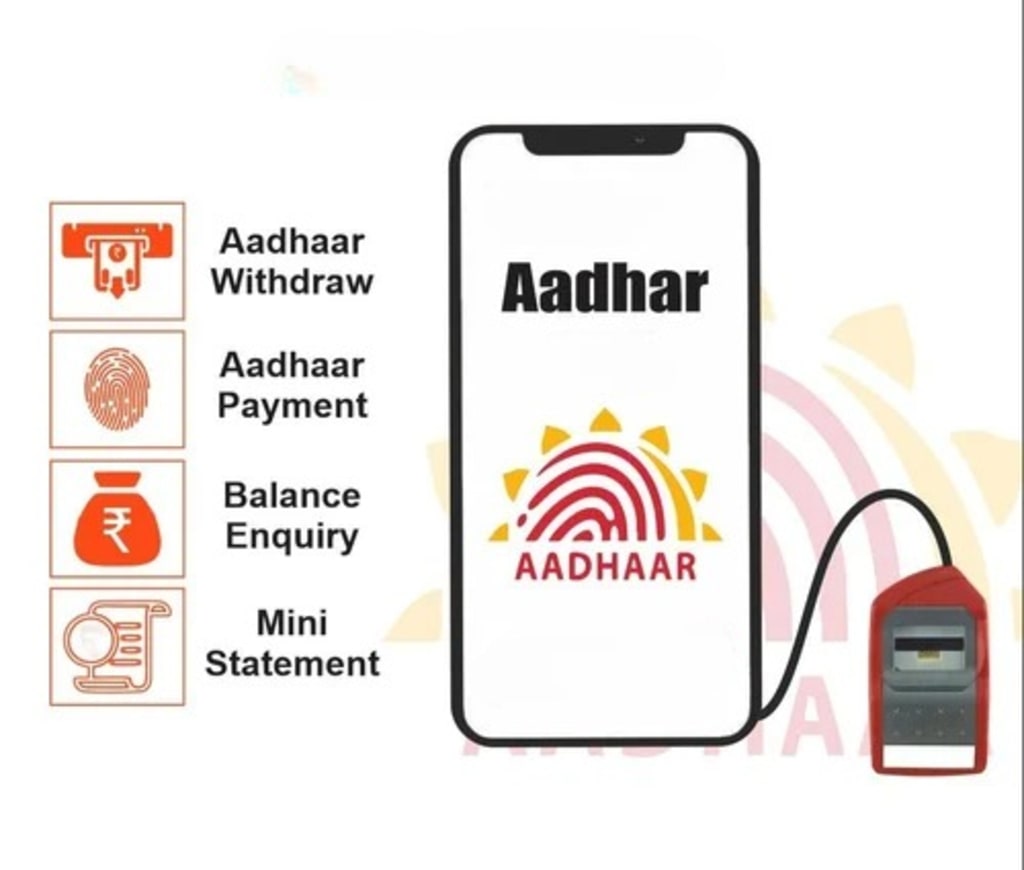
In recent years, AEPS B2B software has emerged as a transformative force in India’s digital payment landscape, revolutionizing how businesses, especially in rural and semi-urban areas, perform financial transactions. As India moves towards a more digital-first economy, solutions like AEPS B2B software are bridging the gap between banks, financial institutions, and end users, facilitating seamless transactions across the country.
What Is AEPS B2B Software?
AEPS (Aadhaar Enabled Payment System) is a government-backed initiative that uses Aadhaar, India’s biometric identification system, to enable secure and efficient financial transactions. AEPS B2B software is designed specifically for businesses, enabling them to integrate AEPS capabilities into their operations. This software allows businesses to perform Aadhaar-based financial transactions like balance checks, fund transfers, and even cash withdrawals, all through biometric authentication.
For business-to-business (B2B) transactions, AEPS software acts as an essential tool for integrating Aadhaar-based transactions into various service platforms, ensuring fast, secure, and cost-effective financial processes.
Key Benefits of AEPS B2B Software
1. Enhanced Financial Inclusion
One of the major advantages of AEPS B2B software is its role in driving financial inclusion in underserved areas. India’s rural and semi-urban regions often lack sufficient banking infrastructure, limiting access to financial services. AEPS software allows users to make transactions without needing a traditional bank branch, making it easier for businesses and individuals to access basic banking services.
Through AEPS B2B solutions, businesses like small retail stores, shops, and micro ATM providers can offer banking services to their customers, expanding access to digital payments and banking features in areas that were once financially excluded.
2. Faster and Secure Transactions
Traditional banking systems often involve time-consuming processes and complex verification steps, which can lead to delays and errors. AEPS B2B software, however, ensures faster, more efficient transactions through biometric authentication. By simply verifying a user’s thumbprint or iris scan, businesses can complete transactions within seconds, improving customer satisfaction and reducing the risk of fraud.
Additionally, AEPS B2B software offers strong encryption and security features, ensuring that transactions remain secure and protected from unauthorized access. This makes AEPS a reliable and trusted option for businesses and consumers alike.
3. Reduced Costs for Businesses
For businesses, especially small and medium-sized enterprises (SMEs), AEPS B2B software significantly reduces the costs associated with payment gateways, banking infrastructure, and physical cash handling. By using AEPS, businesses can eliminate the need for traditional point-of-sale (POS) terminals, ATMs, and cash handling services, making it a cost-effective solution for rural entrepreneurs.
Additionally, since AEPS transactions are facilitated directly through the Aadhaar database, there are fewer intermediaries involved, reducing transaction fees and ensuring more affordable services for businesses and their customers.
4. Seamless Integration with Other Financial Services
AEPS B2B software can be easily integrated with other digital payment solutions, such as mobile recharge software, money transfer software, and BBPS API provider. This means businesses can offer a wide range of financial services, including bill payments, money transfer software, and mobile recharge software, all through a single platform. This not only makes it easier for businesses to expand their service offerings but also creates a one-stop solution for consumers, enhancing user convenience.
The Impact on India’s Digital Economy
AEPS B2B software plays a vital role in driving the growth of India’s digital economy, particularly in rural areas. As the Indian government continues to push for a cashless economy, the role of AEPS becomes even more significant. By providing businesses with the tools needed to facilitate secure and convenient transactions, AEPS B2B software is driving the adoption of digital payment methods and reducing reliance on cash.
With the rise of AEPS software development and AEPS banking software solution, India is witnessing a revolution in its financial landscape. The widespread use of AEPS technology is making it easier for businesses and consumers in rural areas to access financial services, contributing to the growth of digital payments across the country.
Conclusion
In conclusion, AEPS B2B software is playing a crucial role in transforming digital transactions in India, particularly in underserved regions. By enhancing financial inclusion, ensuring faster transactions, reducing costs, and enabling seamless integration with other financial services, AEPS B2B software is a game-changer for businesses across the country. As more businesses and consumers embrace AEPS technology, the future of India’s digital economy looks brighter than ever.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.