
Why AEPS APIs Are the Future of Cashless Transactions in India
AEPS APIs
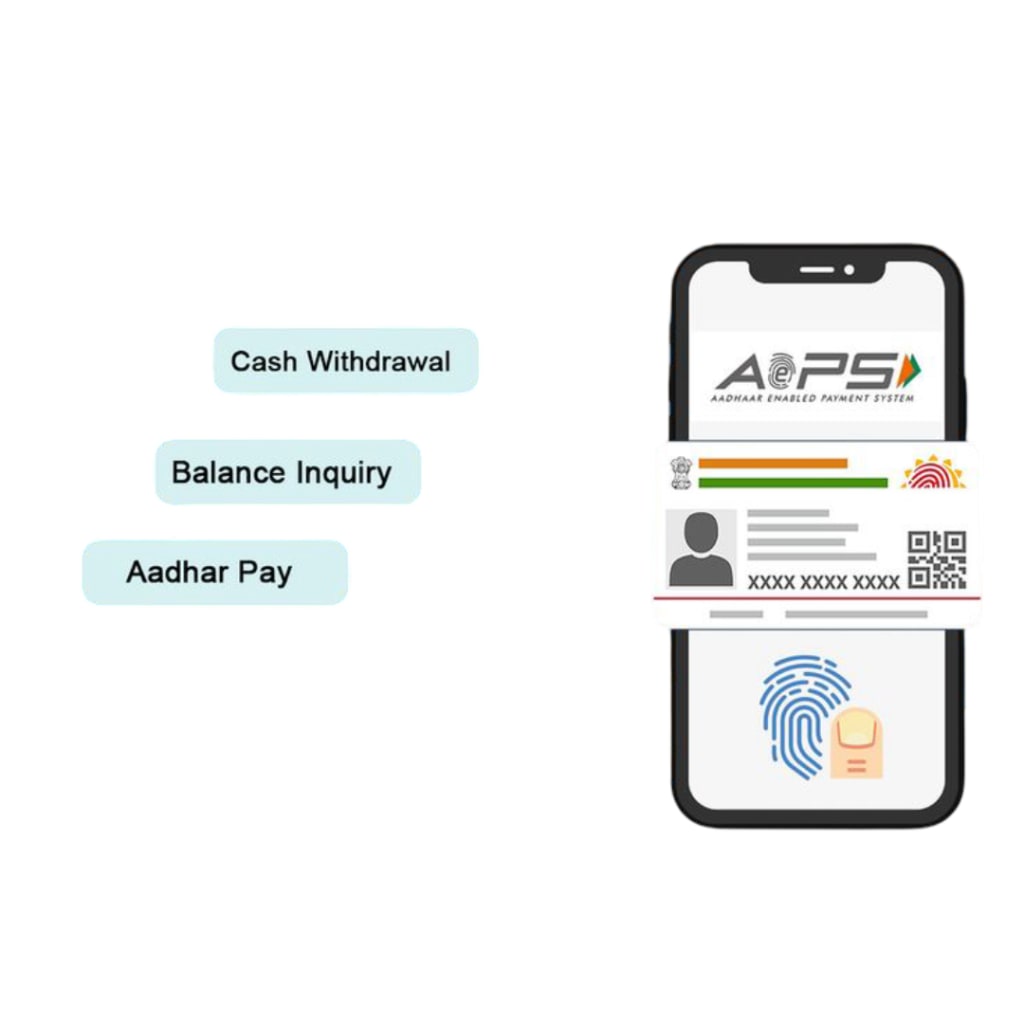
The digital payments landscape in India is evolving rapidly, and at the center of this transformation is the AEPS API provider. AEPS (Aadhaar Enabled Payment System) is a secure and government-backed platform that allows people to perform financial transactions using their Aadhaar number and biometric authentication. AEPS APIs enable fintech companies, retailers, and service providers to integrate these features into their own applications and platforms, making banking more accessible—especially in rural and semi-urban regions where traditional banking facilities are limited.
What is AEPS API?
An AEPS API is a software interface that connects applications and merchant platforms to the AEPS network managed by the National Payments Corporation of India (NPCI). It allows agents and retailers to offer services such as:
Cash withdrawal
Balance inquiry
Mini statement
Fund transfer
The customer only needs their Aadhaar number, the name of their bank, and fingerprint authentication. The AEPS API handles the secure communication between the service provider and the bank’s backend system, ensuring instant and reliable transactions.
Why AEPS API is Crucial for Cashless Transactions
India’s push towards a cashless economy relies heavily on building trust and accessibility for digital payments. AEPS APIs play a major role in this mission by:
Making Digital Banking Inclusive
AEPS brings banking services to areas where internet penetration and traditional banking infrastructure are limited. With an AEPS-enabled retailer nearby, even a small village can access cashless transactions.
Reducing Dependence on Cash
AEPS allows users to pay or transfer funds without physical cash, directly from their Aadhaar-linked bank account. This reduces risks associated with carrying cash.
Supporting Government Subsidy Distribution
AEPS helps in the direct transfer of government subsidies, pensions, and welfare payments, ensuring faster access without middlemen.
Boosting Retail Business Opportunities
Retailers using AEPS APIs earn commissions on transactions, creating an additional income stream while contributing to digital adoption.
Security and Compliance Advantages
One of the strongest aspects of AEPS APIs is biometric security. Since transactions are validated through Aadhaar-linked fingerprints, the chances of fraud are extremely low. Additionally, AEPS APIs comply with NPCI and RBI guidelines, ensuring high security standards, encrypted communication, and full data protection.
AEPS APIs in Rural and Semi-Urban Areas
While UPI and card payments are popular in urban India, rural and semi-urban areas face challenges like poor internet access, low smartphone penetration, and lack of banking branches. AEPS APIs solve these challenges by:
Allowing transactions via micro ATMs operated by local agents
Supporting offline transaction capabilities in certain cases
Reducing the need for customers to travel long distances for basic banking needs
This is why AEPS is often described as the bridge between traditional and digital banking in India.
Benefits for Businesses and Entrepreneurs
Businesses that integrate AEPS APIs gain multiple advantages:
Extra Revenue Source – Agents earn a commission for every transaction they process.
Customer Loyalty – Offering AEPS services makes customers more likely to return for other purchases.
Cross-Selling Opportunities – AEPS services can be bundled with mobile recharge, bill payments, travel bookings, and insurance sales.
For fintech startups, partnering with a reliable AEPS API provider can significantly speed up market entry and reduce operational costs.
AEPS API and the Move Towards Financial Inclusion
Financial inclusion means making sure everyone—regardless of location or income—has access to financial services. AEPS APIs make this possible by:
Allowing people with no ATM or debit card to withdraw money using their Aadhaar number
Providing basic banking services through local retail shops
Making digital transactions accessible to people who are not tech-savvy
This is especially important for empowering women, small farmers, and daily wage workers who might otherwise remain excluded from formal banking.
The Future Potential of AEPS APIs
The adoption of AEPS APIs is expected to grow in the coming years due to:
Rising Aadhaar Enrollment – With most Indians now having an Aadhaar card, the AEPS network is set to expand further.
Better Internet Connectivity – Even remote villages are getting better mobile internet, which will make AEPS services faster and more reliable.
Integration with Other Financial Services – AEPS APIs can be combined with domestic money transfer, bill payment systems, insurance, and loan services to create a one-stop financial hub.
Given India’s ambition to reduce dependency on cash, AEPS APIs will be a core driver of secure, inclusive, and convenient cashless transactions.
Conclusion
The rise of AEPS APIs marks a new chapter in India’s journey towards a truly cashless economy. By enabling Aadhaar-based, biometric-secured banking services through local agents, AEPS APIs are breaking barriers for millions of people who previously had limited access to formal banking.
For businesses, adopting AEPS technology is not just about earning revenue—it’s about becoming part of a larger movement toward digital empowerment. In the coming years, AEPS APIs will continue to evolve, offering greater integration, security, and convenience.
By collaborating with trusted partners and investing in AEPS-enabled solutions—including api for aeps, aeps api cost, recharge api, recharge api provider, aeps software, mobile recharge software, recharge software, recharge software provider, AEPS Portal provider, AEPS B2B Software, AEPS Admin Software, Aadhaar Enabled Payment System Software, AEPS Solution provider, AEPS Banking Software, AEPS Software for Agents, AEPS API Software, AEPS API, AEPS API Provider, AEPS API solution, AEPS Software development company, and AEPS Software development—entrepreneurs can position themselves at the forefront of India’s cashless transaction revolution.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.