
Top Insurance Accounting Challenges and How Businesses Can Overcome Them
Insurance accounting is often described as one of the most complex areas of financial management. Unlike many other industries, insurance organizations must manage large volumes of transactions, regulatory requirements, premium tracking, claims reserves, commission structures, and financial reporting obligations all while maintaining accuracy and compliance.
On paper, everything may seem straightforward. However, behind every insurance policy issued and every claim processed lies a financial system that requires careful coordination. As agencies, brokers, MGAs, and carriers grow, accounting challenges become more difficult to manage, often affecting efficiency, profitability, and decision-making.
The good news is that most of these challenges are not impossible to solve. With the right processes, technology, and operational support, insurance businesses can create stronger financial systems that support long-term growth.
Why Insurance Accounting Is Different
Insurance accounting goes beyond standard bookkeeping. Financial teams must manage premium collections, commission payments, trust accounts, claims-related transactions, policy adjustments, reconciliations, and regulatory reporting. Unlike many businesses that simply record income and expenses, insurance organizations often deal with multiple financial movements tied to a single policy.
This complexity means that even small inefficiencies can create larger operational issues. Delayed reconciliations, inaccurate reporting, and fragmented data can quickly affect business performance if not addressed early.
As the industry evolves, accounting teams are expected to provide greater visibility, faster reporting, and more accurate financial insights than ever before.
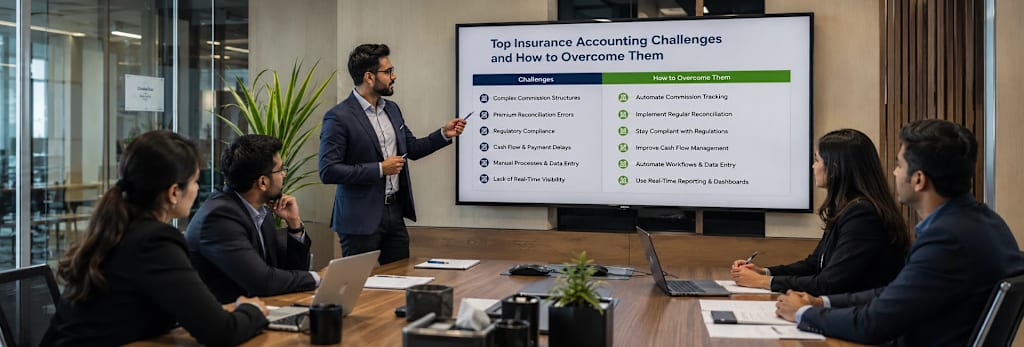
Challenge 1: Managing High Volumes of Financial Transactions
One of the biggest challenges insurance businesses face is handling the sheer volume of financial activity generated every day.
Premium payments, commissions, refunds, endorsements, policy cancellations, claims-related transactions, and carrier settlements all contribute to a constant flow of financial data. As business grows, manually tracking and reconciling these transactions becomes increasingly difficult.
Without structured processes, accounting teams can spend countless hours verifying records, identifying discrepancies, and correcting errors. This not only reduces productivity but also delays access to critical financial information.
The solution lies in creating standardized workflows and leveraging technology that helps streamline transaction management. Automated systems can reduce manual effort while improving visibility across financial operations. Insurance agencies that modernize reconciliation and transaction management processes often experience faster reporting cycles and greater accuracy.
Challenge 2: Data Silos and Fragmented Information
Many insurance organizations operate across multiple systems. Customer data may exist in one platform, policy information in another, claims records elsewhere, and accounting information in separate financial software.
When these systems fail to communicate effectively, accounting teams often become responsible for manually gathering information from multiple sources. This creates inefficiencies and increases the likelihood of inconsistencies.
Data silos can make it difficult to generate accurate reports, track financial performance, and maintain a single source of truth across the organization.
To address this challenge, businesses must focus on improving data integration and creating more connected workflows. Centralized access to financial and operational information helps teams make better decisions while reducing the time spent searching for critical data.
Challenge 3: Complex Reconciliation Processes
Reconciliation is one of the most time-consuming aspects of insurance accounting.
Insurance businesses often receive statements, carrier reports, commission summaries, and payment records in multiple formats. Matching these records accurately requires significant effort, especially when large transaction volumes are involved.
For many accounting teams, reconciliation consumes a substantial portion of the monthly close process. Delays in reconciliation can impact reporting accuracy and limit management's ability to make timely decisions. Industry discussions frequently point to reconciliation as one of the largest accounting bottlenecks in insurance operations.
Improving reconciliation processes through automation, standardization, and better documentation can significantly reduce administrative workload while increasing financial accuracy.
Challenge 4: Maintaining Regulatory Compliance
The insurance industry operates under strict regulatory requirements. Financial records must be accurate, complete, and available for audits, reporting obligations, and compliance reviews.
As regulations continue to evolve, maintaining compliance becomes increasingly complex. Manual processes, spreadsheet-based reporting, and disconnected systems can make it difficult to ensure consistency across financial operations.
Compliance challenges are often magnified when businesses grow rapidly. More transactions, additional reporting requirements, and changing regulatory standards increase operational pressure on accounting teams. Regulatory frameworks such as IFRS 17 have highlighted the need for stronger controls, better data management, and more efficient reporting processes.
Organizations that invest in stronger governance, process controls, and modern reporting solutions are often better positioned to manage compliance effectively.
Challenge 5: Limited Financial Visibility
Many insurance leaders struggle with delayed or incomplete financial information. When accounting processes rely heavily on manual work, reports may take weeks to prepare, making it difficult to respond quickly to business changes.
Without timely financial insights, decision-making becomes more reactive than strategic. Leaders may lack visibility into cash flow, profitability, operational costs, and performance trends.
Modern accounting practices focus on delivering real-time or near-real-time visibility into financial performance. Accurate reporting helps organizations identify opportunities, manage risks, and make more informed decisions about future growth.
Challenge 6: Balancing Growth with Operational Efficiency
As insurance businesses expand, accounting demands grow alongside them. More clients, policies, transactions, and reporting requirements place additional pressure on internal teams.
Many organizations attempt to solve this challenge by hiring more staff. While additional resources may help temporarily, growth often outpaces traditional staffing models.
A more sustainable approach involves optimizing workflows, improving technology adoption, and leveraging specialized operational support when needed. Businesses that focus on process efficiency are often better equipped to scale without creating unnecessary overhead costs.
Building a Stronger Accounting Foundation
Overcoming insurance accounting challenges does not require a complete operational overhaul. In many cases, meaningful improvements come from identifying inefficiencies, simplifying workflows, and adopting tools that support accuracy and visibility.
Strong accounting practices create benefits that extend beyond compliance. They help organizations improve cash flow management, strengthen reporting capabilities, reduce operational risks, and support better business decisions.
The most successful insurance organizations view accounting not simply as a back-office function but as a strategic asset that contributes directly to business performance.
Final Thoughts
Insurance accounting will always involve complexity, but complexity does not have to lead to inefficiency. Challenges such as transaction management, reconciliation, compliance, fragmented data, and limited visibility are common across the industry. The difference lies in how businesses choose to address them.
Organizations that invest in better processes, stronger controls, integrated systems, and operational efficiency position themselves for sustainable growth. By treating accounting as a strategic component of business success rather than an administrative necessity, insurance companies can gain greater financial clarity, improve decision-making, and build a stronger foundation for the future.
In today's competitive insurance landscape, efficient accounting is no longer just about balancing the books it is about creating the visibility, control, and confidence needed to move the business forward.
About the Creator
Fusion Business Solution P Limited
Empowering businesses through innovative outsourcing solutions since 2006. As a leader in BPM & Consulting, we specialize in Insurance Outsourcing, Accounting & Bookkeeping, Data Annotation, BI & Digital Marketing Services
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.