
The Nvidia Lawsuit Everyone Is Sharing Is the Weaker One
The crypto-mining case has a certified class, internal emails, and an SEC fine. The affair case has a stock drop and a materiality problem.
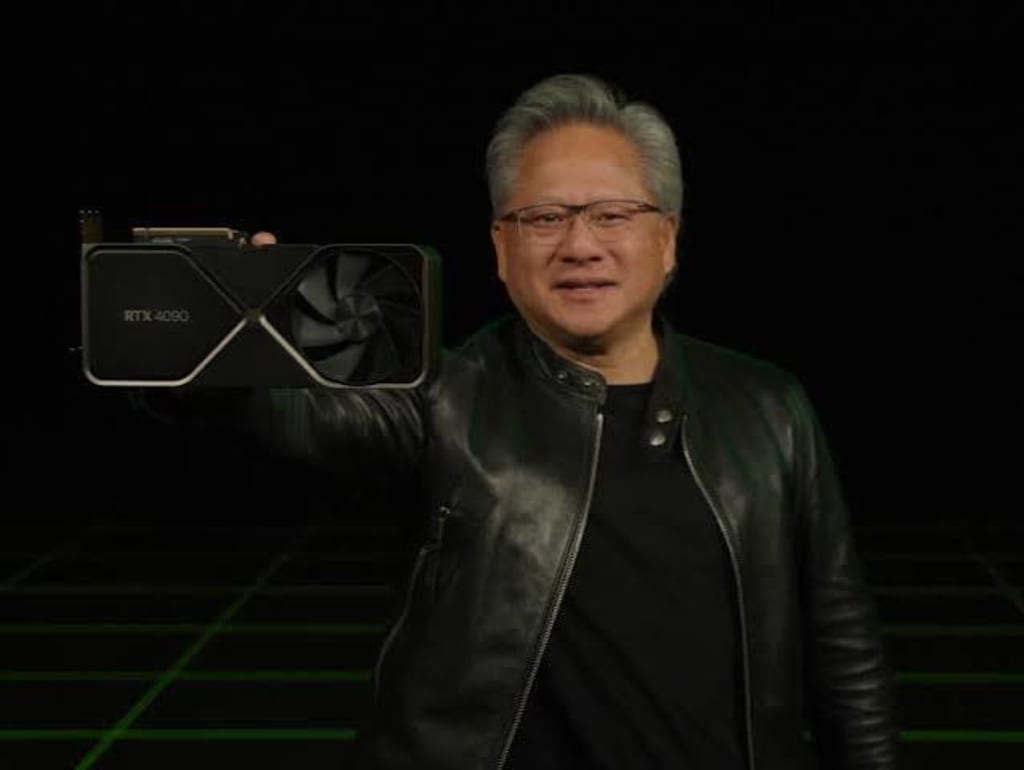
On November 9, 2026, a Nvidia shareholder filed a securities class action in San Jose federal court against the company and CEO Jensen Huang. The complaint arrived about five minutes after the closing bell. Nvidia stock had fallen 4.27% that day and erased roughly $193 billion in market value.
That timing invites a simple story. A personal scandal has turned into a securities fraud crisis. The claims do not fit that story. Two lawsuits are running against the same defendants. They stand on very different ground.
One is the crypto mining case. It has been in litigation for nearly eight years. In March 2026 it crossed the most dangerous procedural threshold in securities class action practice. The other is the personal relationship case, filed the day after Huang acknowledged the affair. Its materiality foundation is thinner. It works more like a pressure instrument deployed into a falling stock.
The standard: what 10b-5 fraud requires
Both cases arise under Section 10(b) of the Securities Exchange Act and SEC Rule 10b-5. To survive, plaintiffs must plead and ultimately prove a material misstatement or omission, scienter, reliance, and loss causation. Scienter means a mental state that embraces intent to deceive. Loss causation means a causal connection between the misstatement and the economic loss.
Materiality is the first gate. The test is objective. A court asks whether a reasonable investor would consider the information important in deciding how to trade. The Supreme Court added a structural constraint in Macquarie Infrastructure Corp. v. Moab Partners, L.P. in 2024. A unanimous Court held that “pure omissions are not actionable under Rule 10b-5(b)”. An omission supports liability only when it makes an affirmative statement misleading. The defendant has said something true as far as it goes but left out critical qualifying information. That creates a half-truth.
Both cases turn on that distinction.
The crypto mining case has already cleared the gate
The crypto mining allegations concern the classification and disclosure of core financial metrics, not personal conduct.
Plaintiffs allege that Nvidia, between August 2017 and November 2018, routed more than $1 billion in GPU revenue driven by cryptocurrency mining into its Gaming segment. They also allege that Nvidia publicly downplayed how much of that demand depended on volatile crypto prices. Investors saw Gaming demand as stable when a material driver was hidden inside that category.
The procedural history is evidence of legal weight. The district court dismissed the case twice for insufficient scienter. The Ninth Circuit reversed in part in 2023. The Supreme Court dismissed Nvidia’s interlocutory appeal in December 2024. On March 25, 2026, Judge Haywood S. Gilliam Jr. issued a 50-page order certifying the class.
Certification matters because securities class actions usually die there. Nvidia argued that the class could not satisfy the predominance requirement of Rule 23 because some class members followed long-term strategies and would have held the stock regardless of the alleged misstatements. Judge Gilliam rejected that argument: “the general fact that some investors purchased a stock as part of a long-term strategy does not mean that the investors would have traded had they known about the claimed fraud”. He noted that under Nvidia’s theory, “defendants like NVIDIA would be almost completely insulated from such class actions”.
The court also refused to exclude plaintiffs’ damages expert. It found that Nvidia had failed to rebut the fraud-on-the-market presumption of classwide reliance. That presumption allows a securities class action to proceed as a class. If the market price incorporated the alleged misstatement, every purchaser can be presumed to have relied on it without proving individual reliance.
Two more features give the case substance. The SEC fined Nvidia $5.5 million in 2022 for inadequate disclosures about how cryptomining affected its gaming business. The SEC found that Nvidia failed to disclose that cryptomining was a “significant element” of its revenue growth from gaming chips in two consecutive quarters of fiscal 2018. That finding does not establish private liability. It does remove the argument that the disclosure issue was immaterial or legally uncontested.
Second, the Ninth Circuit’s 2023 decision reviving the claims rested in part on internal emails and other documents that supported an inference of scienter. Scienter is where crypto cases usually fail. When a court has found enough evidence to let a jury infer that executives knew the gaming narrative was misleading, the case has moved past speculation.
The likely outcome is a settlement, not a defense verdict. The class is certified, discovery is proceeding, and damages exposure runs into the hundreds of millions or more if liability is found. Nvidia’s litigation posture, including its failed trip to the Supreme Court, shows that it understands the exposure.
The personal relationship case has not cleared the gate
The November 9 complaint tells a different story. Plaintiff Mark Kistenmacher seeks to represent investors who bought Nvidia stock between October 9, 2025 and November 8, 2026. The theory is that Nvidia and Huang violated Rule 10b-5 and Section 20(a) by failing to disclose Huang’s relationship with Alice Huang. She is a former executive at Singapore-based Megaspeed International whom U.S. officials have reportedly concluded was working on behalf of Chinese intelligence.
The complaint does not rest on the affair itself. It rests on a half-truth theory. Nvidia had publicly said that its compliance team reviewed Megaspeed and determined the company was not diverting purchases to China. Huang told Bloomberg that Nvidia’s dealings with Megaspeed were “normal and not unusual”. The plaintiff argues those statements were materially misleading because Huang was in a relationship with a Megaspeed executive suspected of helping China evade export controls.
That is more sophisticated than “the CEO had an affair and didn’t tell anyone.” It still runs into three problems that the crypto case does not face.
First, the materiality of the omission is not established by the stock drop. The stock fell 4.27% on November 9. By then Nvidia had fallen roughly 25% from its October 6 high of $243.37, and its one-month return was about -22%. The decline was part of a broader repricing of AI equities. Nvidia can argue that the November 9 drop reflected a market already in correction mode absorbing bad news, not a discrete revelation that rewrote the company’s fundamental value.
Materiality is an objective inquiry. Plaintiffs often use the stock drop as evidence of it. When the stock has already been falling for weeks on sector-wide concerns, the inference becomes contestable. A reasonable investor might care about a CEO’s affair with a suspected foreign intelligence operative. The legal question is whether that fact was material in the context of the statements Nvidia actually made. Nvidia can argue that its compliance review of Megaspeed was independent, that CEO-customer interactions are routine, and that the board found “no reason to believe” national security or company secrets were compromised.
Second, loss causation is vulnerable. Rule 10b-5 requires the plaintiff to show that the economic loss was caused by the misstatement or omission, not by other market forces. If Nvidia’s stock was already in a correction driven by AI valuation concerns, the defendant can argue that the November 9 decline would have occurred in similar magnitude even absent the alleged omission. The plaintiff must isolate the incremental effect of the relationship disclosure from the ongoing sector selloff. That is an empirical question, and the defendant has a factual basis to contest it.
Third, the half-truth theory requires linking the private relationship to the truth of the public compliance statement. Nvidia’s public position was that its compliance team reviewed Megaspeed and found no diversion. The plaintiff argues that this statement was misleading because Huang’s relationship with Alice Huang compromised the independence of that review or created an undisclosed conflict. Nvidia can respond that the compliance review was conducted by the compliance function, not by Huang personally, and that Huang’s personal relationship does not make the public statement false unless it can be shown that the relationship actually affected the review’s outcome or that Huang intervened to shape it.
That is where the Megaspeed investigation timeline becomes relevant and dangerous for Nvidia. The New York Times reported that in late 2025, Commerce Department investigators were pursuing a probe into Megaspeed’s suspected chip smuggling. Nvidia’s general counsel, Tim Teter, sent an email to the Bureau of Industry and Security invoking the name of Jeffrey Kessler, a top Commerce official who had given Nvidia permission to reach out. After that email, the BIS case was abruptly transferred to the Justice Department and the Commerce investigation was halted.
That sequence does not prove securities fraud. It gives the plaintiff a narrative that goes beyond “he had an affair.” It suggests that Nvidia’s general counsel intervened in a live export-control investigation involving a company led by the CEO’s romantic partner, and that the intervention coincided with the investigation being taken away from the agents handling it. If discovery in the securities case uncovers evidence that Huang or other executives knew the relationship created a compliance risk and sought to manage that risk through back-channel pressure rather than disclosure, the scienter and materiality arguments become stronger.
That is a conditional path. The complaint as filed does not rest on that evidence. It rests on the failure to disclose the relationship itself. On that theory, Macquarie is a serious obstacle. Nvidia did not have a standalone duty to disclose the CEO’s private life. The plaintiff must show that the omission made an affirmative statement misleading. The “normal and not unusual” statement is the hook. Nvidia will argue that the statement referred to business interactions with Megaspeed, not to Huang’s personal relationship, and that the two are analytically separate.
What the two cases mean for Nvidia
The two cases carry different risks.
In the crypto case, the class has been certified. The fraud-on-the-market presumption survived. The scienter evidence has already been tested at the appellate level. The SEC has previously found inadequate disclosure on the same underlying subject. The realistic risk is a settlement in the hundreds of millions. That is a financial event, but it is known and bounded.
In the personal relationship case, the claim is new. The class is uncertified. The materiality and loss-causation defenses are substantial. The half-truth theory has not been tested. Its primary function at this stage is to impose litigation and reputational costs while the stock is under pressure. The danger for Nvidia is not a judgment. It is that discovery pulls the Megaspeed investigation sequence into the securities record and converts a weak disclosure claim into something closer to an obstruction or conflict-of-interest narrative.
On governance, the personal relationship case has already done damage that the crypto case never could. It has placed the CEO’s private judgment at the center of the company’s most sensitive geopolitical exposure. The board has opened an independent investigation and expressed confidence in Huang, but the fact that the investigation exists is itself a governance signal. Congressional committees have begun requesting Huang’s testimony. The question is no longer only whether Nvidia disclosed enough to investors. It is whether the CEO exercised appropriate judgment in a relationship that intersected with a live export-control investigation.
The market is pricing both cases into a stock that was already expensive and already correcting. The crypto certification produced a 2.17% decline on the day it was announced. The relationship complaint produced a 4.27% decline, but in a market that had already taken Nvidia down more than 20% in a month. Neither number tells us much about the legal merits. They show that investors are sorting Nvidia’s risk register differently. The AI demand story remains intact. The legal and governance tail risks are no longer hypothetical.
Where the liability sits
The headline story of a CEO’s affair with an alleged spy leading to a securities fraud suit is the weaker of the two claims. It has a plausible half-truth hook. The Megaspeed investigation timeline gives it a path to something more serious if discovery goes badly for Nvidia. As a stand-alone 10b-5 claim, it has not established materiality, it faces a strong loss-causation defense, and it depends on a causal link between a private relationship and the truth of a public compliance statement that Nvidia can contest on the facts.
The crypto mining case has already done the legal work. It has a certified class, a tested scienter record, a regulatory precedent, and a procedural posture that makes a defense verdict unlikely. If you want to know where Nvidia’s securities liability sits, the answer is not in the affair. It is in the revenue classification decisions the company made in 2017 and 2018, and in the eight years of litigation that now sit before a certified class.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.