
PepsiCo’s Drink Sales Are Improving, and It’s Planning to Cut Snack Prices
After beating Wall Street expectations for Q4, PepsiCo aims to boost competitiveness and consumer spending with lower snack prices while sustaining revenue growth.
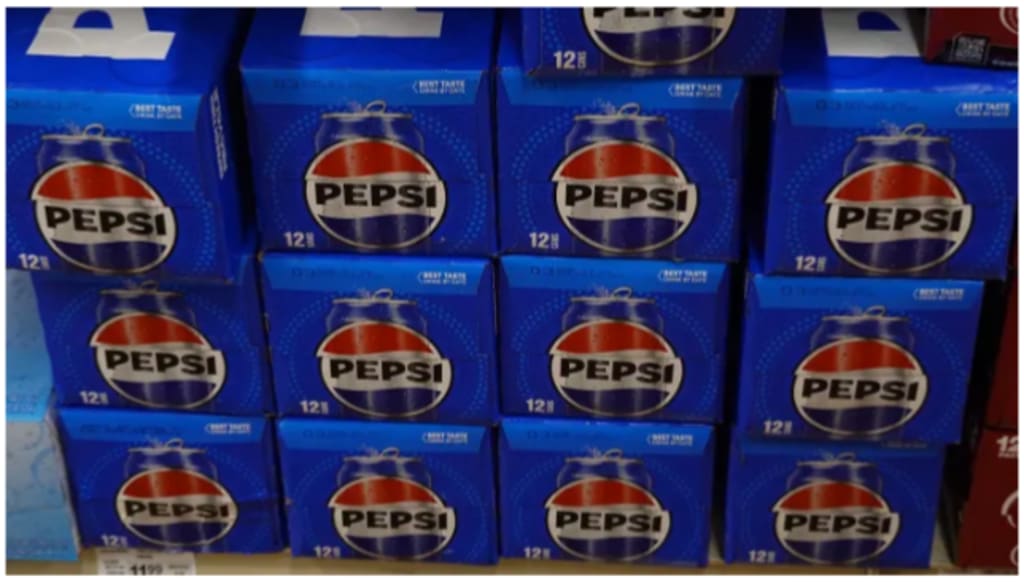
PepsiCo, one of the world’s leading food and beverage companies, reported fourth-quarter earnings and revenue that exceeded analyst expectations, driven by improving sales across its beverages division. While the company continues to face headwinds in its North American snack business, executives announced plans to cut prices on snack products to improve purchase frequency and competitiveness. Strong Quarterly Performance For the fourth quarter, PepsiCo reported revenue of $29.34 billion, surpassing Wall Street’s estimate of $28.97 billion. Adjusted earnings per share (EPS) came in at $2.26, slightly above the anticipated $2.24. Net income attributable to the company rose to $2.54 billion, or $1.85 per share, compared with $1.52 billion, or $1.11 per share, a year earlier. Organic revenue, which removes the impact of currency fluctuations, acquisitions, and divestitures, increased 2.1%, signaling solid underlying demand across global markets. CEO Ramon Laguarta described the results as a “sequential acceleration in reported and organic revenue growth, with improvements in both North America and International businesses.” Beverage Sales Lead the Way PepsiCo’s beverage segment is showing signs of recovery after a period of sluggish volume. Global drink volume ticked up 1%, and organic sales improved across its flagship brands, including Pepsi, Gatorade, Starry, and Poppi. In North America, beverages posted a slight 4% decline in volume, though organic sales still rose 2%, suggesting that demand is improving despite inflationary pressures. Analysts note that the beverage recovery reflects both seasonal consumption trends and successful marketing campaigns that have encouraged repeat purchases. Snacks Face Consumer Resistance While drinks are performing well, PepsiCo’s snack business continues to face challenges. Global food volume fell 2%, with North American snack volume slipping 1%. Products under PepsiCo Foods North America—such as Cheetos, Quaker Oats, and Doritos—are experiencing weaker consumer demand as shoppers push back against higher prices. To counter this trend, the company plans to reduce snack prices across its North American portfolio. Executives emphasized that productivity savings and cost-cutting measures across operations will offset the revenue impact of these price reductions. The goal is to increase purchase frequency and retain consumer loyalty while staying competitive against rival snack brands. Strategic Moves and Investor Engagement PepsiCo’s pricing strategy is part of a broader plan that began in December 2025, when the company reached an agreement with activist investor Elliott Investment Management, which held a $4 billion stake in the company. As part of the plan, PepsiCo committed to: Cutting 20% of its U.S. product lineup Implementing cost reductions across food and beverage operations Lowering snack prices to drive demand Despite Elliott not receiving board seats, the agreement underscores a push to streamline operations and enhance shareholder value. Analysts view these moves as a sign that PepsiCo is proactively balancing growth initiatives and cost management. Looking Ahead: 2026 Forecast PepsiCo reiterated its 2026 outlook, projecting: Organic revenue growth between 2% and 4% Core constant currency EPS growth of 4% to 6% The company expects North American operations to improve as price adjustments take effect and consumer demand stabilizes. International businesses are expected to remain resilient, supported by diversified product offerings and regional market expansion. The outlook indicates confidence in the company’s ability to sustain revenue and profitability even amid a challenging consumer environment characterized by inflation and shifting spending habits. Market Reaction Despite beating analyst expectations, shares of PepsiCo fell slightly more than 1% in premarket trading, reflecting broader market volatility and caution about short-term volume declines. Market analysts suggest that the dip may also relate to concerns over the pace of recovery in the North American snack division. However, long-term investors are likely to view the price-cut strategy and operational efficiency plans as positive steps toward strengthening the company’s core business. By balancing competitive pricing with productivity gains, PepsiCo is positioning itself to maintain market share in a competitive industry. Consumer Trends and Implications The decision to cut snack prices highlights a broader trend among U.S. consumers: sensitivity to inflation and value-oriented spending. Many shoppers are reducing discretionary purchases of higher-priced snacks and drinks, prompting companies like PepsiCo to adjust pricing and promotional strategies. By lowering prices while maintaining productivity savings, PepsiCo aims to stimulate repeat purchases and brand loyalty, a strategy that may also benefit shelf visibility and market penetration. Conclusion PepsiCo’s fourth-quarter results reflect a company navigating a complex consumer landscape with strategic foresight. While North American snack sales are still recovering from inflation-driven declines, the beverage segment shows steady improvement, and global operations remain strong. The company’s plan to reduce snack prices while cutting costs and streamlining its product lineup signals a proactive approach to maintaining competitiveness and driving consumer engagement. With a solid 2026 outlook in place, PepsiCo appears well-positioned to balance growth, profitability, and market relevance in a rapidly evolving food and beverage industry. As consumers respond to lower prices and targeted marketing campaigns, investors and analysts will be closely watching to see whether PepsiCo’s strategy translates into higher volumes and sustained revenue growth throughout the year.
About the Creator
Sajida Sikandar
Hi, I’m Sajida Sikandar, a passionate blogger with 3 years of experience in crafting engaging and insightful content. Join me as I share my thoughts, stories, and ideas on a variety of topics that matter to you.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.