
Nike Just Chopped Off Thousands of Sellers to Save Itself in China — Will It Bleed Out Instead?
The sportswear giant’s radical “Chinese‑Style Amputation” is a high‑stakes bid to reclaim its brand power — but the ghosts of its North American collapse and the hunger of local rivals like Anta and Li‑Ning are closing in fast.
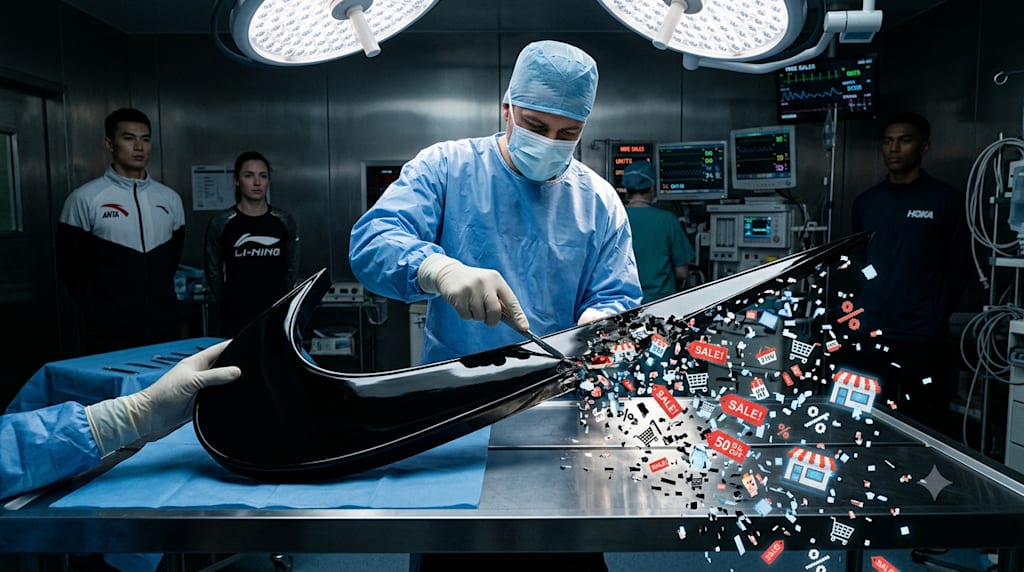
July 2026 – a bombshell landed in China’s sportswear market. A letter from Cathy Sparks, Nike’s newly appointed Vice President and General Manager of Greater China, brought the company’s long‑standing distribution strategy in the region to an abrupt halt. Starting January next year, thousands of online resellers will be cleared from Nike’s digital shelves, and the brand’s online sales footprint will shrink dramatically to a handful of official direct‑operated channels.
This is no routine channel adjustment. It is a high‑stakes strategic gamble, fraught with contradictions and courage. After eight consecutive quarters of revenue decline in Greater China – a regional business now roughly 30% smaller than its peak – Nike seems finally to have admitted that the golden era of coasting on a swoosh and flooding the market through third‑party distributors is irrevocably over.
I. The channel disease: when “middlemen” hollow out brand equity
There was a time when, in the Chinese consumer’s mind, Nike’s Swoosh was synonymous with sporty chic. But over the past five years, that immense brand halo has been chipped away by the unchecked proliferation of distribution channels.
Under Nike’s old model, major distributors like Top Sports, Pou Sheng, and Rui Li acted as “traffic monetizers” – middlemen who simply moved boxes. The brand built trust; the distributors shoved product into every conceivable corner. It was a win‑win – until e‑commerce platforms dragged the whole game into a price‑war quagmire.
Shoppers quickly caught on: the same basketball shoe, officially priced at ¥1,299 on Nike’s website, could be had for ¥300 less during a distributor’s Double 11 livestream, and “uncoded” units on DeWu might shave off another ¥200. The brand equity Nike had painstakingly built was being deconstructed in a frenzy of chaotic discounts into little more than a comparison‑shopping exercise. Once the pricing architecture collapses, the consumer’s mental anchor shifts permanently. As BNP Paribas analyst Laurent Vasilescu put it: “Distributors are not the problem; the product is.” – yet it is precisely those unruly distributors that have become the sharpest blade accelerating Nike’s “disenchantment” in the eyes of consumers.
Nike’s latest “purge” is, in essence, a forced repossession of its pricing power. By funnelling online traffic exclusively into its official app, Tmall, and Douyin flagship stores, Nike is trying to reconstruct a “unified, premium” consumption arena. In this new arena, price is no longer the only competitive dimension; brand storytelling, product presentation, and the consumer experience are returned to centre stage. This is not about shrinking consumer access – it is about ending the chaotic narrative of “one brand, a thousand prices.”
II. Pain and a silver lining: brick‑and‑mortar stores as an “unexpected haven”
The market’s first reaction was visceral. After the news broke, Top Sports – China’s largest Nike retailer – saw its stock plunge more than 24%, as the market fretted over the fate of up to ¥5.6 billion in online‑related revenue. For these channel giants long accustomed to Nike’s “feeding,” losing their online traffic stream is akin to having a wing clipped.
Yet shift our gaze to offline physical retailers, and the picture takes on a strikingly different hue.
In this strategic realignment, Nike explicitly stated that its partnerships with offline authorised dealers remain intact. That sends a crucial signal: the value of offline channels is being re‑assessed. In e‑commerce logic, physical stores are cost centres; in brand‑experience logic, they are value highlands.
Once online discounts are reined in and predatory dumping is eliminated, physical stores will no longer be passive battlefields in a price war. Instead, they can return to the essence of retail – service and experience. Nike’s recent flurry of basketball tournaments, running clubs, and outdoor ACG community events suggest that physical stores are being recast as physical anchors for “emotional connection” with consumers. In this dimension, the instant discounts of e‑commerce cannot replace the sense of social belonging that a local run club provides. So, for compliant brick‑and‑mortar operators, the online retrenchment may not be a shock at all – it may even be a boon. They are being upgraded from mere “pickup points” to the very “load‑bearing walls” of brand premium.
III. The ghost of North America: a dangerous “self‑destruct” imitation?
As logically coherent as the strategy may sound, it still sends chills down the spines of capital markets. Analysts’ concerns are far from baseless – they have seen this ghost before.
A few years ago, Nike made a similar move in North America – drastically cutting wholesale partnerships in favour of a DTC (Direct‑to‑Consumer) model. The results backfired spectacularly: Nike not only lost substantial shelf space, handing market share to upstarts like Hoka and On Running, but also saw profit margins crater under the weight of its own inventory. It was widely regarded in the industry as a “self‑inflicted” strategic blunder.
Now Nike is replicating that playbook in China, and the challenges here are even more formidable. China’s e‑commerce ecosystem is far more fragmented – Douyin, Xiaohongshu, DeWu, and other platforms are deeply intertwined, and the distributor web is intricate. As Nike reclaims channel power, it must simultaneously fill the gaps in traffic acquisition, customer service, after‑sales, and regional logistics – a capillary network of operations that will send its operating costs soaring into the stratosphere.
More lethally, Nike’s “house‑cleaning” is creating breathing room for domestic rivals like Anta and Li‑Ning. While Nike is busy shutting the gates, Anta is telling middle‑class stories inside Arc’teryx and Salomon stores, and Li‑Ning is capturing the hearts of Gen‑Z on the basketball court with designs that feel native and current. Nike’s retreat is, in effect, a tactical withdrawal on the battlefield – giving its pursuers a wider charge lane.
IV. The price of arrogance: you can slim channels, but can you reshape minds?
Set aside the war‑gaming of distribution channels. We must confront the core question that lies at the heart of this transformation – and the one that truly haunts Nike: Will purging distributors make young people fall in love with Nike again?
The answer, I suspect, is not encouraging. Nike’s deceleration in China over the past few years cannot be fully explained by channel chaos. The deeper malaise is that this global giant has contracted a classic case of “big‑company arrogance.” While domestic brands were obsessively iterating on design, signing star athletes, embedding themselves in local basketball culture, and playing the social‑media game with Gen‑Z on their own turf, Nike appeared sluggish and aloof. Even its occasional “China‑themed” products were often panned as soulless window‑dressing.
The shift in consumer mindshare has been silent but inexorable. A few years ago, young people used to say, “I can’t afford Nike.” Now they say, “I’d only buy Nike if I had no money.” That joking reversal captures the quiet erosion of brand premium by domestic alternatives. When consumers feel that a pair of Anta or Li‑Ning better reflects their aesthetic and cultural pride, Nike’s Swoosh becomes little more than a functional badge – stripped of emotional resonance.
Epilogue: more than a channel war
Nike’s “amputation” is a painful course‑correction born of harsh reckoning. It is trying to regain lost brand authority and pricing power by taking back control of its channels. But the brutal truth of the commercial world is this: cutting off ten thousand distributors is easy; winning back ten thousand hearts is the hard part.
If Nike fixes its gaze solely on price control and channel purges, without delivering a compelling next‑generation product and without humbling itself to truly understand the cultural context of young Chinese consumers, then this whole manoeuvre may end up as nothing more than a “self‑congratulatory strategic contraction.”
When the clock strikes 2027, Nike may well have a tidy, orderly pricing architecture. But it will still have to answer the original question: In today’s China, beyond the fading glow of its storied past, why should any consumer willingly spend ¥1,000 on a pair of Nikes that have just become “more expensive”?
The answer to that question does not sit in a distributor’s warehouse. It lies in the design sketches and marketing scripts inside Nike’s Shanghai headquarters.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.