
Mortgage Rates Drop for a Fourth Straight Week, Yet a Long-Term Drop is Dubious
U.S. mortgage rates drop for the fourth week, but inflation concerns and Federal Reserve policies may limit further declines.
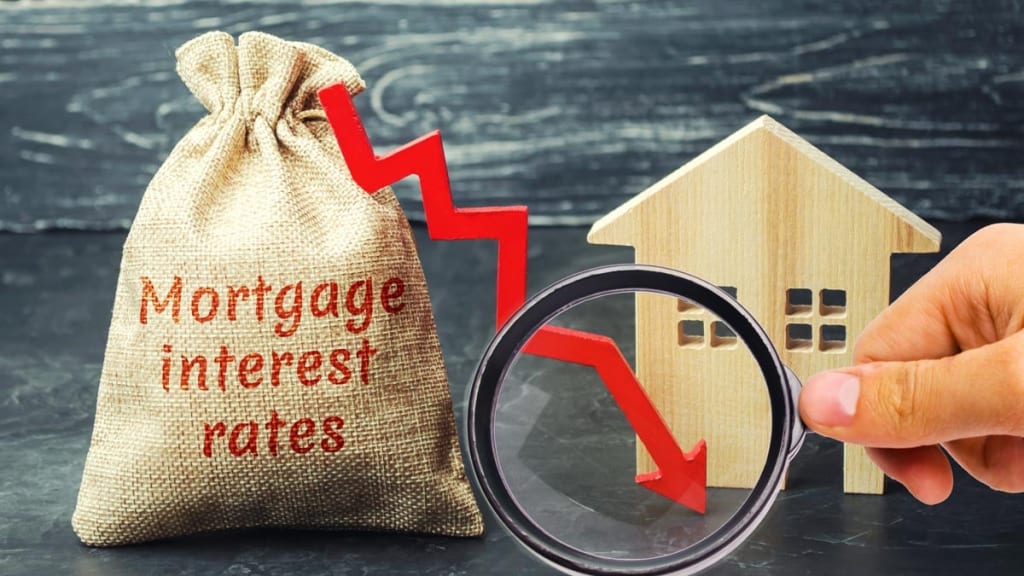
For the fourth week consecutively, mortgage rates within the U.S. have decreased, lessening the burden for homebuyers and refinancers a bit further. From last week, the average rate for a 30-year fixed mortgage has dropped to 6.87%, down from 6.89%. While even this reduction is noteworthy, it also suggests that mortgage rates may not be as volatile as previously - and abhorrently - high.
Current Mortgage Rate Trends
Unfortunately, even this positive shift did not help mortgage rates surpass the historic low of 2.65% in early 2021, with them currently standing at an embarrassingly high figure due to the Federal Reserve aggressively combating inflation with interest rate hikes.
Even this February of last year, the 30-year mortgage rate sat around 6.77%, meaning we are still dealing with lesser economic conditions. While experts are more or less correct about these shifts, it is other glaring issues such as inflation or Federal Reserve policies that are needed for a long-lasting change, which is quite unfortunate.
Impact on Housing Market
The warfare on cash has drastically impacted the US market and sales of previously owned homes shockingly dropped to their lowest levels in almost 30 years and is set to get worse in 2024. Homeowners are facing challenges due to high borrowing costs and limited housing inventory. An approximation made by the National Association of Realtors (NAR) states that homes were sold 18% less year over year which makes this one of the most stagnant housing markets we have encountered since the 1990s.
New home buyers have it tougher than ever, prices and costs left many sidelined waiting for a better outcome. It makes sense to sit on the fence with the current economic situation.
Federal Reserve’s Role and Economic Outlook
The Federal Reserve does not directly set mortgage rates, but it influences borrowing costs. The central bank’s decision to raise interest rates throughout 2022 and 2023 predominantly fueled the merge of a new rate of the mortgage. After 3 consistent reductions in the year 2024, Fed decided in January of 2025 to offer no changes in impose a base lending rate for of a year.
The latest data for inflation hints that the Federal Reserve will remain on the conservative side. The Consumer Price Index for January 2025 came out, and as many economists had feared, inflation was running hotter than expected. This makes aggressive cuts to interest rates much more difficult. Stagnant inflation means bond investors want greater returns, which means that the ten-year treasury bond yields, which are critical in determining mortgage rates, increase.
2025 Market Outlook
Economists are split on their mortgage rate expectations over the course of the year. Some economists expect rates to settle around 6.5 percent, while a significant number believe those rates will stay in the mid-to-high 6 percent to 7 percent range for the majority of the year.
Lisa Sturtevant, chief economist at Bright MLS, stated, “Prospective buyers and sellers should expect mortgage rates to remain in the high-6% range heading into the spring market.”
Realtor.com’s Housing Forecast for 2025 does show, however, that lower rates could be the result of deeper cuts from the Federal Reserve of there is a downside surprise to inflation.
Are homebuyers finally coming up for air?
The Federal Reserve might regain control of inflation, which would allow mortgage rates to moderately drop. Homebuilder construction also appears to be increasing, which might help the housing supply and ease prices. This combined with inflation, indicates that there may be positive indications for affordability, even if it is small at the moment.
Some lenders are also offering buy-down programs that allow buyers to lower their starting interest rates for the first couple of years. This could help temporarily for homebuyers that are facing difficulty with affordability.
Finishing Remarks
Though mortgage rates dropping is a benefit, homebuyers and refinancers need to be careful because there is still concern out there. Numerous facets such as inflation, Federal Reserve policy choices, and the state of the economy will ultimately decide the trajectory of mortgage rates. Rates are anticipated to stabilize, but the chance for the ultra-low mortgage rates experienced in 2020 and 2021 is nonexistent in the near future.
For those looking to purchase a house, the most important piece of advice is to stay updated as well as search for the most suitable financing avenues during these volatile shifts.
About the Creator
Andries Wesseling
Andries is a dynamic Tech & Business Coach dedicated to empowering entrepreneurs and professionals. With expertise in technology-driven strategies and business growth, Wesseling helps clients streamline operations.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments