
Malaysian Banks Poised for Growth Amid Funding Tightness and Wealth Management Upside
Revised loan-growth forecasts signal renewed optimism for Malaysia’s banking sector, but divergent funding pressures and an emerging wealth-management runway are reshaping competitive dynamics among lenders.
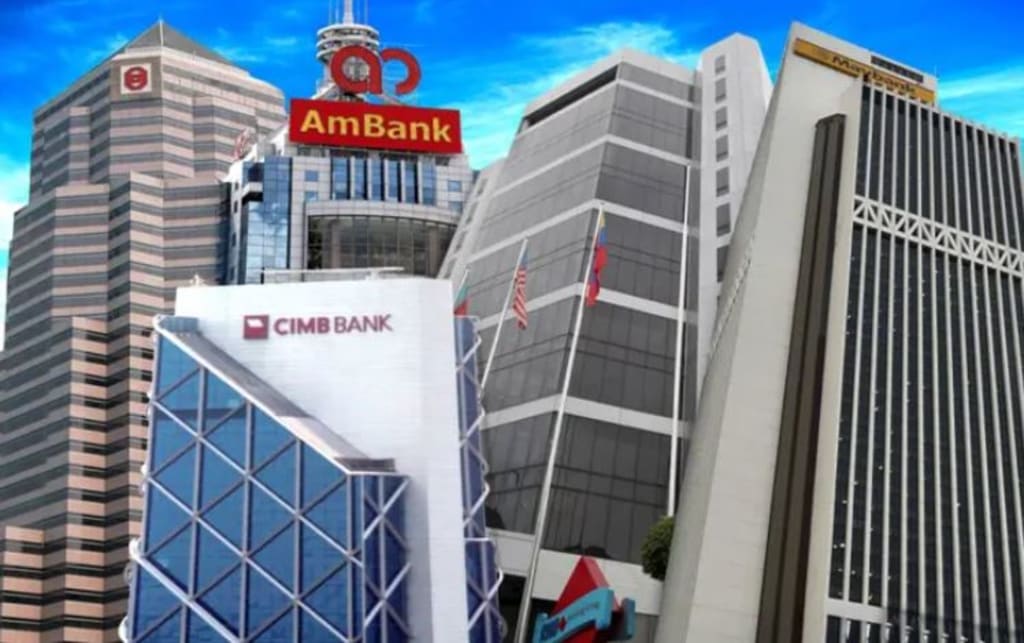
CIMB Research’s upward revision of Malaysia’s banking industry loan-growth forecast to 5.5% in 2026 from 4.8%, with further lifts for 2027 and 2028, reflects growing confidence in the nation’s investment upcycle. This optimism is grounded in tangible data: business loan applications surged 37.7% year-on-year in July, with approvals jumping 51.9%, driven by broad-based demand across construction, manufacturing, working capital, and investment-related financing. Crucially, this aligns with Bank Negara Malaysia’s assessment that capital deepening, resilient domestic demand, and stronger external prospects will sustain momentum through 2027. For investors, this validates the sector’s “overweight” stance, particularly for banks positioned to capture corporate credit expansion. Yet beneath the headline growth lies a critical tension: while asset quality remains stable (gross impaired loans at 1.43%), the banking system’s domestic loan-to-deposit ratio has climbed to 101.1% when excluding foreign-currency deposits, a level that signals latent funding strain despite no immediate liquidity crisis.
This funding dynamic is becoming the key differentiator among banks. CIMB notes that institutions with robust transaction-banking operations, cash-management capabilities, and entrenched corporate relationships enjoy a structural advantage in securing low-cost funding. Conversely, banks overly reliant on retail deposits or wholesale markets face mounting pressure on net interest margins (NIMs) as business credit outpaces domestic deposit mobilization. AmBank Research corroborates this, highlighting that NIMs contracted by two basis points quarter-on-quarter due to intense deposit competition. While banks can mitigate this by replacing expensive deposits with cheaper alternatives, such strategies take time to materialize. Thus, the current environment favors lenders with diversified, sticky funding bases, those able to convert corporate transaction flows into core deposits rather than chasing rate-sensitive savers. This divergence explains why both research houses concentrate “buy” ratings on banks like Public Bank, RHB, Hong Leong Bank, and CIMB, which combine strong corporate franchises with efficient balance sheets.
Beyond traditional lending, wealth management is emerging as a pivotal growth lever. AmBank points to a 43% year-on-year surge in wealth-management fees, underscoring its potential to offset NIM compression and drive non-interest income. Though Malaysia’s wealth sector remains nascent compared to Singapore’s, the smaller base implies significant runway for penetration within existing customer pools. Banks that successfully cross-sell investment products, insurance, and advisory services to their retail and SME clients can deepen wallet share without a proportional increase in coststhe . This shift aligns with broader regional trends where fee income buffers against cyclical credit risks. Critically, AmBank argues that Malaysian banks’ undemanding valuations (~0.9x price-to-book) and ~6% dividend yields fail to reflect this rerating potential, especially given accelerating profit growth expectations (3.7% in FY2027 vs. 1.3% currently). The market’s regional disconnect thus presents an entry point for investors recognizing the dual tailwinds of credit expansion and fee-income diversification.
Asset quality, often a concern during credit upcycles, appears contained for now. Both research houses describe deterioration as “manageable,” supported by adequate provisioning buffers. This resilience stems from prudent underwriting during prior downturns and the current cycle’s focus on productive investment rather than speculative borrowing. However, vigilance remains essential: if funding costs rise sharply or global demand falters, marginal borrowers could face stress. Banks with conservative risk appetites and granular portfolios are better insulated a factor reinforcing preferences for Hong Leong and Public Bank, known for disciplined credit cultures.
For stakeholders, the implications are clear. Borrowers benefit from ample credit availability but should anticipate tighter pricing as banks manage funding costs. Regulators must monitor deposit competition to prevent destabilizing rate wars. Investors, meanwhile, should prioritize banks with three attributes: (1) low reliance on volatile funding, (2) scalable wealth-management platforms, and (3) proven asset-quality discipline. The sector’s upgraded outlook is warranted, but success now hinges less on volume growth and more on strategic positioning amid evolving structural constraints. In this refined landscape, the winners won’t just be those who lend most but those who fund smartest and diversify earliest.
About the Creator
Mark Lim
Hi I am mark an automotive student and a car, tech and food enthusiast ! Im gonna try and post daily & hope you enjoy what I write and do share my page with people you know. I would gladly appreciate it! Cheers
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.