
Integrated Fortress: Sunway’s AA1 Rating and the Power of Vertical Synergy
A robust landbank, a diversified healthcare portfolio, and a self-financing model, Sunway Bhd secures a top-tier credit rating despite high leverage, proving that structural resilience can outweigh balance sheet constraints.
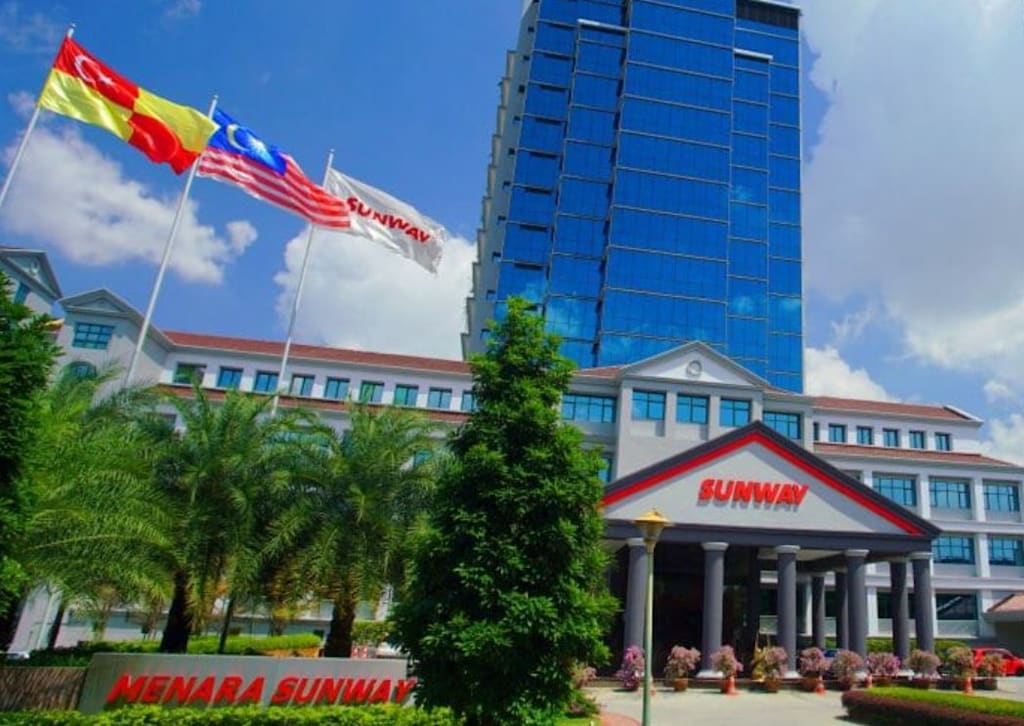
RAM Ratings has assigned initial corporate credit ratings of AA1/Stable/P1 to Sunway Bhd, supported by the conglomerate’s established positions across property development, construction, property investment, and healthcare, as well as strong medium- to long-term earnings visibility. This high rating places Sunway among the elite tier of Malaysian corporations, reflecting confidence in its ability to meet financial obligations even in a volatile economic environment. The "Stable" outlook indicates that RAM expects Sunway to maintain its strong business profile and financial metrics over the next 12 to 18 months, while the "P1" short-term rating underscores its strong capacity for timely repayment of short-term debt.
The rating agency said Sunway’s extensive vertical integration across its core property value chain supports a resilient business model and provides greater earnings stability relative to peers. Unlike developers who rely on external contractors or separate entities for construction and management, Sunway controls the entire lifecycle of its projects—from land acquisition and construction to property management and retail operations. This integration allows for better cost control, faster execution, and higher profit margins, as value is captured at every stage of the process. It also reduces dependency on third parties, mitigating supply chain risks that have plagued other developers in recent years.
These strengths, however, are tempered by modest debt coverage metrics stemming from the sizeable debt accumulated to finance the group’s expansion. Sunway’s aggressive growth strategy, particularly in healthcare and large-scale township developments, has required significant capital expenditure. While this debt is a concern, RAM views it as manageable given the quality of the assets being acquired and the predictable nature of the cash flows they generate. The key is not just the amount of debt, but the ability to service it through consistent operational income.
Sunway had RM8.3 billion of unbilled property sales and an outstanding RM10.5 billion construction order book as at August 2026, providing a substantial pipeline of future revenue. These figures offer a clear window into the company’s near-term performance, reducing uncertainty for investors and creditors. Unbilled sales represent contracts signed but not yet recognized as revenue, indicating strong demand and healthy sales momentum. The construction order book ensures that Sunway Construction, one of the group’s key pillars, will have a steady workflow, supporting employment and operational efficiency.
RAM said earnings visibility is further supported by healthy property take-up rates and steady execution of ongoing developments. In a market where many developers struggle to move inventory, Sunway’s ability to sell units at a consistent pace demonstrates the strength of its brand and the appeal of its integrated townships. Projects like Sunway City continue to attract buyers due to their comprehensive amenities, including malls, schools, hospitals, and theme parks, which create a self-sustaining ecosystem that enhances property values.
Longer-term growth is underpinned by Sunway’s 2,338-acre landbank with an estimated gross development value of RM87.7 billion, alongside an active construction tender book of RM14.2 billion. This massive land bank provides decades of potential development, ensuring that the company will not face a "land drought" that could stall growth. The diversity of this landbank, spanning residential, commercial, and industrial uses, allows Sunway to pivot between sectors based on market conditions, further enhancing its resilience.
Healthcare is also expected to become an increasingly important earnings contributor as Sunway expands capacity and newer hospitals progressively ramp up operations. The recent listing of Sunway Healthcare Holdings Bhd was a strategic move to unlock value and raise capital for further expansion. As the population ages and demand for quality medical services rises, Sunway’s network of hospitals and clinics is well-positioned to capture this growth. The sector’s defensive nature, as people need healthcare regardless of the economic cycle, provides a stable counterbalance to the more cyclical property business.
RAM also viewed positively Sunway’s track record of incubating, scaling, and monetising businesses through established platforms such as Sunway REIT, Sunway Construction Group Bhd, and Sunway Healthcare Holdings Bhd. This "incubate-and-list" strategy allows the group to develop assets to maturity before spinning them off into publicly listed entities. This not only realizes value for shareholders but also recycles capital back into the parent company for new investments, creating a virtuous cycle of growth without excessive reliance on external debt.
The group’s major expansion initiatives are largely self-financed at the operating division level, which RAM said reduces funding concentration and refinancing pressure at the holding company. By allowing subsidiaries to raise their own debt based on their specific asset bases and cash flows, Sunway avoids bottling up all financial risk at the top. This decentralized financing structure enhances overall group flexibility and ensures that a liquidity crunch in one division does not necessarily jeopardize the others.
Financial flexibility is further supported by a sizeable pool of unencumbered assets and RM1.2 billion in committed undrawn funding facilities as at 2025. Unencumbered assets those not pledged as collateral for loans serve as a crucial buffer in times of stress, as they can be easily monetized or used to secure new financing. The undrawn facilities provide immediate access to cash if needed, acting as an insurance policy against unexpected market disruptions.
Despite recent deleveraging following the listing of Sunway Healthcare Holdings Bhd, RAM said debt coverage remains the principal constraint on the group’s ratings. Based on FY2025 figures, net debt-based funds from operations (FFO) and operating cash flow (OCF) debt coverage stood at 0.24 times and 0.32 times, respectively, supported by Sunway’s sizeable cash holdings. These ratios, while adequate, are lower than those of some conservative peers, reflecting the group’s higher leverage. However, the presence of significant cash holdings mitigates the immediate risk of default.
RAM projects gross FFO and OCF debt coverage to range between 0.11 times and 0.16 times from FY2026 to FY2028, based on an estimated peak debt load of RM18 billion. Corresponding net-debt coverage ratios are projected to be between 0.19 times and 0.28 times over the same period. The projected dip in coverage ratios reflects the anticipated increase in debt to fund ongoing projects and acquisitions. While this may seem alarming, it is a typical pattern for growth-oriented conglomerates during peak investment phases. The key will be Sunway’s ability to convert these investments into cash flow as projects complete and stabilize.
Nevertheless, RAM said its assessment takes into consideration the quality and stability of Sunway’s earnings across its diversified asset base, alongside management’s established track record of executing growth initiatives. The AA1 rating is ultimately a vote of confidence in Sunway’s leadership and its proven ability to navigate complex markets. It acknowledges that while the debt load is high, the assets backing it are high-quality, income-generating, and strategically positioned for long-term success. In a world of uncertainty, Sunway’s integrated fortress offers a rare combination of scale, stability, and growth potential.
About the Creator
Mark Lim
Hi I am mark an automotive student and a car, tech and food enthusiast ! Im gonna try and post daily & hope you enjoy what I write and do share my page with people you know. I would gladly appreciate it! Cheers
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.