
How AEPS Solutions Are Reducing the Urban-Rural Banking Divide
AEPS Solutions
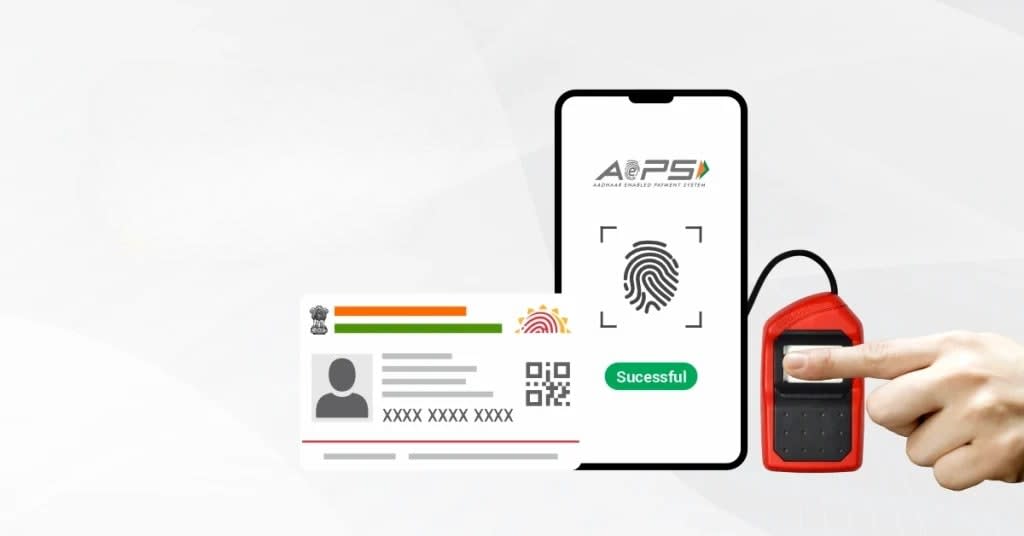
India’s journey towards financial inclusion has taken major strides with the help of technology, especially in the last decade. One key innovation leading this transformation is the Aadhaar Enabled Payment System (AEPS). With support from reliable digital platforms and fintech partners such as a BBPS Software Provider, AEPS is helping bridge the gap between urban and rural banking infrastructure.
This article highlights how AEPS solutions are making banking easier, faster, and more accessible for rural citizens—empowering Bharat to bank without boundaries.
What Is AEPS and Why Is It Important?
AEPS stands for Aadhaar Enabled Payment System. It allows individuals to carry out financial transactions using their Aadhaar number and biometric verification. AEPS makes it possible for people without smartphones, debit cards, or internet access to:
Withdraw cash
Check account balance
View mini statements
Transfer money
These services are provided through local agents or banking correspondents using biometric-enabled devices. In areas where banks are miles away, AEPS has become a reliable and secure lifeline for financial services.
Breaking the Barriers to Rural Banking
Traditionally, rural customers have struggled with access to banking due to:
Lack of bank branches in remote areas
Limited awareness about financial products
Travel costs and time to reach a city bank
AEPS solves these problems by providing doorstep banking services through agents in every village. AEPS devices connect users to their banks using Aadhaar and fingerprints, allowing safe transactions—even in places without an ATM or internet connectivity.
How AEPS Reduces the Urban-Rural Divide
1. Local Access to Financial Services
AEPS services are available at local shops or agent points. This reduces the need to travel and ensures round-the-clock access to basic banking functions.
2. Real-Time Transactions
Customers no longer have to wait for banking hours. AEPS enables real-time processing of withdrawals, balance inquiries, and DBT (Direct Benefit Transfer) payments.
3. Secure Aadhaar-Based Verification
Fingerprint-based transactions mean users don’t need to remember passwords, carry cards, or worry about fraud—ideal for semi-literate or elderly users.
4. Earning Opportunities for Agents
Local agents earn commissions on each transaction, creating jobs and encouraging more retail participation in rural economies.
AEPS as a Multi-Service Business Model
AEPS solutions are now being integrated with other digital services such as:
BBPS (Bharat Bill Payment System) for bill payments
DMT (Domestic Money Transfer) services
Mobile/DTH recharge
PAN card and utility services
This combination helps agents run profitable multi-service businesses, offering urban-grade convenience in rural locations.
Importance of Choosing a Strong AEPS Platform
For AEPS to run efficiently, retailers and fintech companies need dependable AEPS software with:
A responsive admin panel
Biometric device compatibility
Secure API integration
Instant settlement features
Easy user interfaces for rural users
Working with an experienced fintech development partner ensures stability and long-term growth.
Government Push and Rural Response
Schemes like Jan Dhan Yojana and Digital India have made AEPS adoption widespread. More villagers now receive government benefits and pensions directly into their bank accounts. AEPS helps them access this money safely and conveniently.
This positive feedback loop is transforming how rural citizens view banking—from something distant and difficult to something local and empowering.
Conclusion
AEPS has proven to be one of the most impactful digital innovations in India's rural economy. It gives every citizen access to basic financial services, regardless of their location, device, or education level. By reducing the need for traditional bank infrastructure, AEPS is leveling the field between rural and urban India.
If you're planning to enter the digital payment space or expand your services in rural regions, consider reliable partnerships in the fintech domain. Work with an aeps software development company that understands rural needs. Collaborate with an aeps api service provider that offers strong backend support and quick settlements.
For sustainable fintech growth, look for platforms that include:
Micro ATM software development
Multi recharge software development
AEPS solution and micro ATM service
AEPS portal provider, AEPS Admin Software, and Aadhaar Enabled Payment System Software
To cover broader services, ensure your system also supports AEPS Solution provider, AEPS Banking Software, and expansion-ready tools from a trusted Mobile Recharge Software Development Company.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.