
Global Markets Tread Carefully: Oil Eases, Central Banks Loom, and AI Earnings Face the Test
Calm Before the Policy Storm Oil Retreats Amid Diplomatic Glimmers Asia Under Pressure The Rate Path: On Hold Now, Hikes Later AI at the Crossroads Bonds, Currencies, and Commodities A Pivotal Week Unfolds
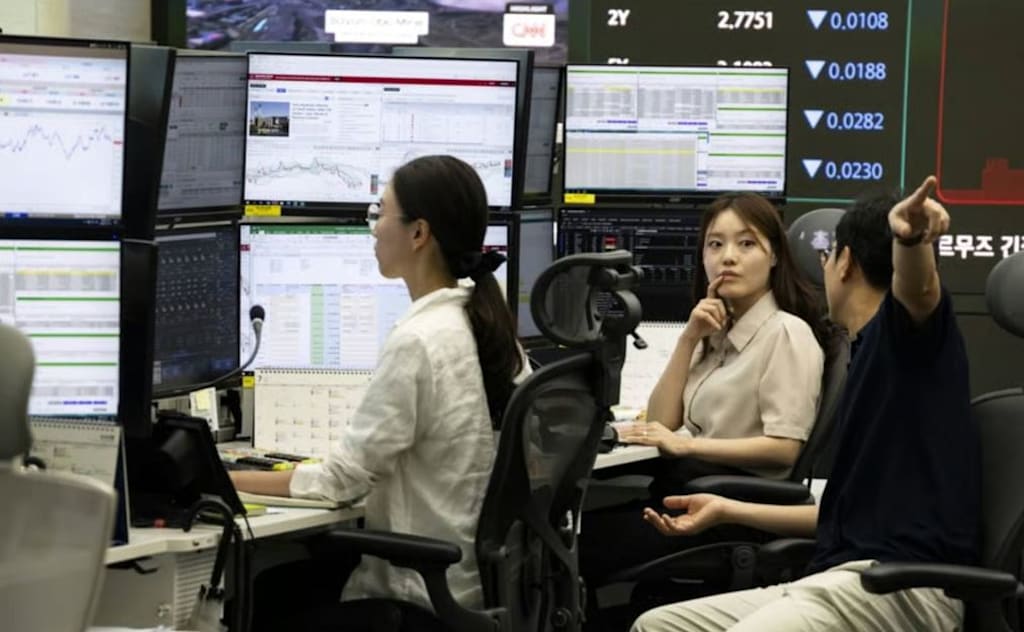
Global share markets began the week in a cautious holding pattern on Monday, as easing crude prices offered modest relief while investors braced for a week of consequential central bank decisions and high-stakes corporate earnings reports that will put the AI boom under intense scrutiny.
Calm Before the Policy Storm
Major indices traded in narrow ranges across the opening session, reflecting deep caution ahead of a packed calendar. Japan’s Nikkei slipped 0.8% following a 4.0% drop the prior week; South Korea’s KOSPI fell 0.4%, extending a difficult month that has seen it lose nearly 19%. The MSCI Asia-Pacific ex-Japan index edged down just 0.1%. In early Western trading, sentiment was more resilient: S&P 500 and Nasdaq futures both rose 0.2%, while Europe’s EUROSTOXX 50 gained 0.2% and the DAX climbed 0.1%.
Oil Retreats Amid Diplomatic Glimmers
Energy markets offered the session’s most encouraging development. Brent crude eased 1.0% to US$115.48 per barrel, and US crude fell 1.1% to **US$102.08. The pullback followed reports that Qatari mediators visited Tehran on Sunday in a US‑backed push to de‑escalate tensions across the Middle East. Just last week, Brent surged 6.2%, its steepest weekly gain since mid‑2022, driven by Houthi attacks in Saudi Arabia and fears of supply disruption. Prices remain elevated, but the prospect of dialogue has eased immediate pressure.
Still, the inflationary footprint of energy costs weighs heavily. As Goldman Sachs analysts noted, “The more extreme and long‑lasting the energy shock becomes, the more Fed participants will worry that inflationary pressures could broaden.”
Asia Under Pressure
Asian markets face multiple headwinds beyond oil. South Korea’s steep monthly decline underscored how sharply investor sentiment has shifted, while Japan’s Nikkei has entered a corrective phase. Even so, the broader regional index proved relatively resilient, suggesting value‑seeking buying is emerging at lower levels.
The Rate Path: On Hold Now, Hikes Later
This week’s defining theme is monetary policy. Five major central banks meet, and while the Federal Reserve, European Central Bank, and Bank of Japan are all seen holding steady, the message they deliver will shape expectations for December and beyond. Markets price in an 80% chance of a Fed hike in December, with a similar timeline for the ECB and BoJ. New Zealand is expected to raise rates as early as Wednesday, while Canada may also act.
Bruce Kasman, Global Head of Economics at JPMorgan, framed the broader shift: “G3 central banks are likely to remain on hold, but Canada should start its tightening cycle and first moves are expected from the UK and Sweden next month.” US data due this week is forecast to show core inflation sticky at 3.1% and annualised growth running a robust 3.2%, powered in part by massive spending on AI data centres, reinforcing the case for caution from policymakers.
AI at the Crossroads
If central banks set the macro tone, earnings will drive the narrative in tech. Roughly one‑third of the S&P 500 reports this week, led by the so‑called hyperscalers Alphabet, Microsoft, and Amazon. These results will test whether the enormous valuations attached to AI are backed by real revenue acceleration. Intel and SanDisk also report, offering critical insight into hardware demand.
Consensus estimates are lofty:
Microsoft: ~US$90.6bn revenue, EPS ~US$4.73
Amazon: ~US$202bn revenue, EPS ~US$1.97
Alphabet: ~US$128bn revenue, EPS ~US$3.00
Equity markets have already faced pressure from climbing bond yields; 10‑year Treasuries yield 5.0%, down from a 5.36% peak earlier this month but still high enough to challenge growth stock valuations. A miss or even soft guidance from these giants could trigger a broad reassessment.
Bonds, Currencies, and Commodities
Treasuries rallied last week before selling pressure returned Friday; 10‑year yields sit at 5.0%, a level that remains competitive and supportive of the dollar.
The yen held its safe‑haven appeal at 157.00 per dollar, having gained 0.8% last week.
The euro steadied at US$1.1204 relieved France avoided a Moody’s downgrade though political unrest keeps investors watchful.
Sterling held at US$1.3346 as new Chancellor John Healey prepares his first budget amid high borrowing costs.
Gold ticked up slightly to US$4,001/oz after a 4% drop last week.
The Brazilian real awaited trading following President Luiz Inácio Lula da Silva’s historic fourth‑term election victory.
A Pivotal Week Unfolds
Monday’s quiet masks significant stakes. By week’s end, we will know whether central bankers see inflation cooling or persisting; whether AI spending is delivering on the promise; and whether geopolitical tensions are truly easing or merely pausing. Markets are holding their breath, and every release, speech, and diplomatic update could shift the balance.
About the Creator
Mark Lim
Hi I am mark an automotive student and a car, tech and food enthusiast ! Im gonna try and post daily & hope you enjoy what I write and do share my page with people you know. I would gladly appreciate it! Cheers
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.