
Beyond Capital: Cultivating Creditworthiness as Malaysia’s SME Growth Catalyst
As Malaysia’s economy accelerates, SME success hinges less on accessing finance and more on demonstrating financial readiness transforming financing from a reactive lifeline into a strategic tool for sustainable expansion.
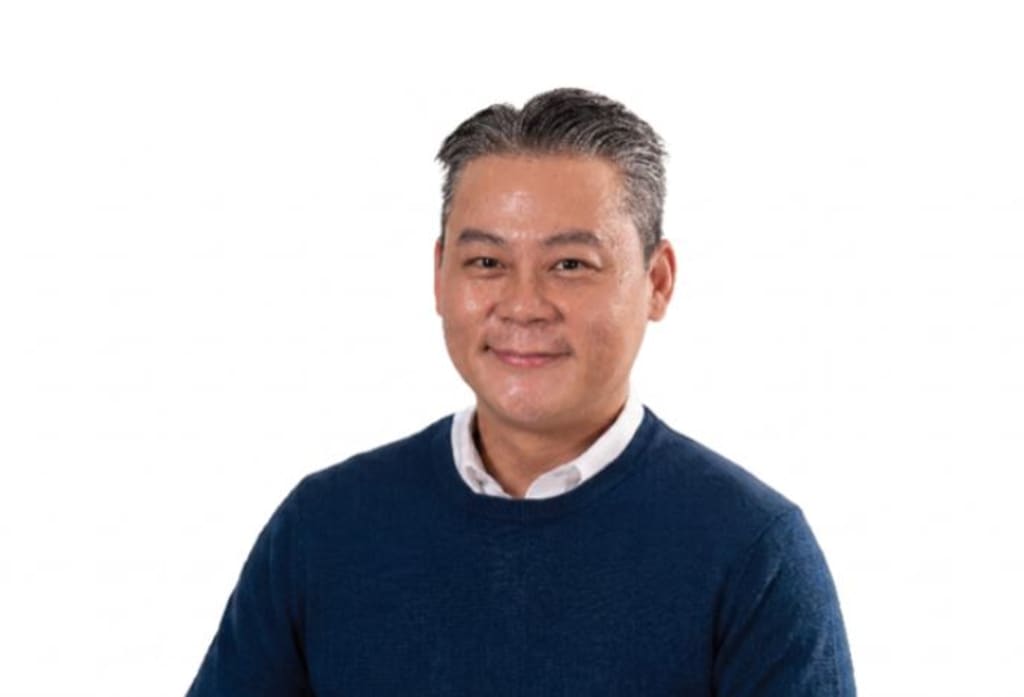
Malaysia’s economic momentum is undeniable. With GDP growth accelerating to 6% in Q2 2026 and trade surging past RM2.16 trillion in the first seven months, the macroeconomic foundation for SME growth is robust. Yet as Credit Guarantee Corporation Malaysia (CGC) Chief Business Officer Sean Tan emphasizes, opportunity alone is insufficient. The critical bottleneck for SMEs isn’t capital availability; it’s financing readiness. In an era where 39.5% of GDP and 48.7% of employment depend on SMEs, the distinction between seeking funds and being fundable has become the defining factor in whether businesses scale or stall. Tan’s reframing is pivotal: financing must be viewed not as emergency cash but as an integrated component of growth strategy, where purpose precedes product and credibility is built long before application.
This shift demands a fundamental reorientation of the SME mindset. Too often, businesses approach financiers only when cash flow tightens, presenting vague needs and weak evidence. Tan counters this with four non-negotiable priorities: know your purpose, build evidence, manage risks, and engage early. Purpose-driven financing starts with clarity: Is the need for working capital tied to specific contracts? Does machinery investment align with production capacity? Without this precision, even viable businesses appear risky. Evidence-building requires disciplined financial hygiene, separating personal/business accounts, documenting receivables, maintaining accurate records not as bureaucratic chores but as proof of operational maturity. Risk management means proactively addressing vulnerabilities like customer concentration or key-person dependency through diversification plans or succession structures. And early engagement transforms financing conversations from transactional negotiations into collaborative planning sessions, allowing banks to understand the business model before pressure mounts.
The Five Cs of credit (Character, Capacity, Capital, Collateral, Conditions) remain relevant, but Tan rightly elevates cash flow and business purpose above collateral. A company with strong management, healthy cash generation, and a clear repayment source is far more bankable than one with assets but opaque operations. This is where CGC’s role becomes transformative. As a risk-sharing partner not an automatic approver CGC bridges gaps for fundamentally sound businesses lacking traditional security. Its portfolio guarantees (up to RM3 million, 70% coverage) and BizJamin schemes (up to RM30 million for mid-tier firms) are designed for viability, not just collateral. Crucially, CGC’s targeted initiatives for startups, climate tech, and digitalization reflect evolving economic priorities, ensuring guarantees catalyze productive growth aligned with national development goals. With RM106.6 billion facilitated for 548,000 MSMEs by June 2026, CGC proves that risk mitigation can unlock opportunity without compromising prudence.
Real-world cases underscore why structure matters as much as amount. A project-based engineering firm struggled to secure working capital because its request wasn’t linked to contract proceeds a failure of purpose alignment. An automotive distributor needed flexibility but hadn’t matched facilities to inventory turnover cycles a mismatch of cash flow logic. These aren’t failures of ambition but of financial storytelling. Financiers don’t reject businesses; they reject unconvincing narratives. When SMEs articulate how financing converts to revenue (e.g., “This RM500k will fulfill Contract X, generating RM2m in 90 days”), they shift from supplicants to partners. This narrative strength is built through daily discipline, not last-minute scrambling.
For Malaysia’s next growth phase, SMEs must internalize that creditability is cultivated, not requested. The most resilient businesses won’t be those with the most capital, but those with the clearest vision, strongest evidence, and proactive risk frameworks. Policymakers and institutions like CGC have created the scaffolding; now SMEs must build the house. This means treating financial readiness as core to management not an afterthought. It means seeing bankers as advisors, not gatekeepers. It means understanding that every ringgit borrowed must have a documented path back to the business. Only then can financing truly catalyze innovation, job creation, and global competitiveness.
Ultimately, Malaysia’s SME story isn’t about overcoming capital constraints. It’s about mastering the art of being investable. As Tan concludes, “Financing is not simply about asking for money. It is about demonstrating why financing this business makes sense.” In a resilient economy brimming with opportunity, that demonstration is the true competitive advantage. For SMEs ready to make that case, the future isn’t just funded; it’s earned.
About the Creator
Mark Lim
Hi I am mark an automotive student and a car, tech and food enthusiast ! Im gonna try and post daily & hope you enjoy what I write and do share my page with people you know. I would gladly appreciate it! Cheers
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.