
Why the Aircraft Ignition System Market Rarely Makes Headlines
One non-negotiable reliability requirement shapes everything about how this aerospace component market is structured.
The Component That Has to Work Every Single Time
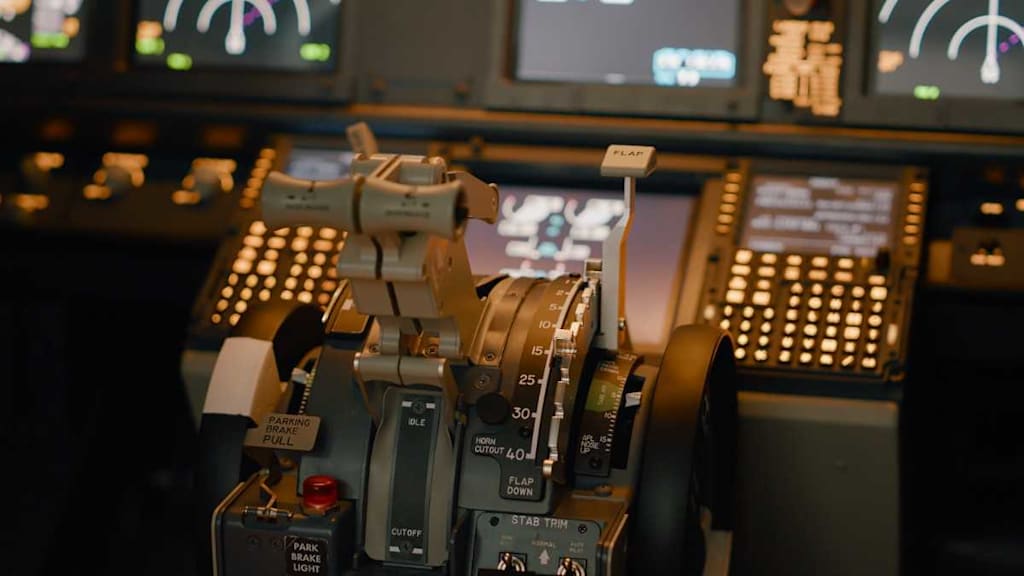
There are parts on a commercial aircraft where occasional failure is manageable. The ignition system is not one of them. Every engine start, every inflight relight in icing conditions or heavy turbulence, every cold soak restart after hours on a winter tarmac — each depends on a spark being delivered at the right energy level, at the right moment, without fail. The engineering and certification standards built around that requirement give the Aircraft Ignition System Market a structure unlike most industrial component categories: slow-moving, heavily regulated, and organised almost entirely around the consequences of getting it wrong.
Those researching this market from an investment or procurement perspective can view the available segment and forecast data here.
What the System Consists Of and When It Operates
A jet engine ignition system has two primary components: an exciter unit, which converts aircraft electrical supply into a high-voltage charge, and igniter plugs, which discharge that energy as a high-intensity spark inside the combustion chamber. The architecture is not complex. The qualification requirements are.
During normal cruise, the ignition system on most commercial engines is inactive. Combustion sustains itself once established. The system re-engages under specific conditions — engine start sequences, flight through heavy precipitation or icing where flame stability in the combustor may be compromised, and any inflight relight scenario. What this means in practice is that an igniter plug must deliver a reliable spark after potentially hours of dormancy, in temperatures that may have dropped well below freezing, at altitude pressures significantly below sea level conditions. Automotive ignition components operate under none of those constraints simultaneously.
Certification testing covers all of it. Vibration profiles, temperature cycling, altitude simulation, electromagnetic compatibility, and endurance testing under degraded conditions are each required before a component can be installed on a type-certificated aircraft. The process is not fast, and it is not inexpensive.
The MRO Channel and Why It Matters
Igniter plugs have defined replacement intervals measured in engine operating hours. That interval creates a predictable, recurring demand stream that continues regardless of whether airlines are expanding their fleets or contracting them. An airline deferring new aircraft orders still operates its existing fleet and still replaces igniters on schedule.
This dynamic makes the MRO and aftermarket channel a structural feature of the market rather than a secondary revenue stream. Research on the Aircraft Ignition System Market identifies MRO demand as a consistent baseline that buffers the market against the order cycle volatility that affects other aerospace component categories more severely.
Fleet expansion in Asia-Pacific — driven by airline growth in China, India, and Southeast Asia absorbing large narrowbody deliveries — adds OEM volume on top of that base. Each new airframe requires qualified ignition components at installation and establishes an aftermarket replacement schedule that runs for the life of the aircraft, typically measured in decades.
How Certification Shapes the Competitive Structure
Parts Manufacturer Approval from the FAA, or equivalent certification from EASA and other authorities, is required before any ignition component can be installed on a certificated aircraft. A new supplier cannot enter with a lower-cost igniter plug on engineering merit alone — the certification pathway takes years and requires investment that is entirely sunk if the application does not succeed.
The result is a market where qualified incumbent suppliers hold positions that are structurally protected from the kind of competitive displacement that characterises less regulated industrial categories. Unison Industries and Champion Aerospace are among the established names on the commercial side. Their positions reflect not only engineering capability but the accumulated certification investment that a new entrant would need to replicate from the beginning.
This is not incidental to how the market works. It is the market working as designed. The regulatory barrier exists because the failure mode it guards against — an engine that cannot be started or restarted — has consequences that make the cost of entry a reasonable price for the reliability it produces.
What the Next Decade Looks Like
Hybrid-electric and hydrogen propulsion programmes under development by several manufacturers will require ignition system engineering adapted to different combustion chemistries and operating profiles. These are not near-term production realities, but they represent the design work currently underway that will eventually create demand for next-generation qualified components.
In the meantime, the existing commercial fleet continues to fly, the replacement intervals continue to run, and the certification process continues to determine who is qualified to supply them. For a market built around one non-negotiable requirement, that continuity is the story.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.