
Veterinary Antiparasitics: Resistance, Innovation, and the Parasite Gap
The market for pet and livestock parasite prevention is growing — but resistance threatens to outpace it.
The Parasite Problem in Veterinary Medicine Is Bigger Than Anyone Wants to Admit
Heartworm disease costs American pet owners an estimated $1,000 to $3,000 per treatment episode. The preventive medication that stops it costs roughly $35 to $80 a year. The math is obvious, and yet heartworm remains endemic across significant portions of the United States, with the American Heartworm Society tracking a measurable northward expansion of the disease's range as climate patterns shift. This is the persistent, frustrating reality of veterinary parasitology: the tools exist, but the behavior gap between "prevention is available" and "prevention is used" remains stubbornly wide.
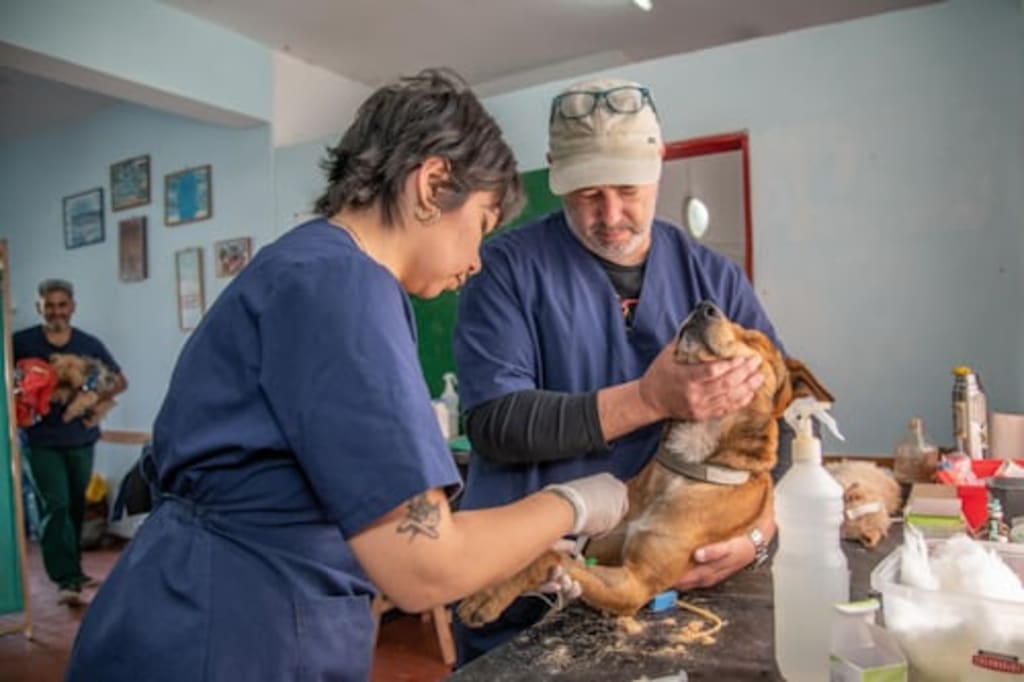
Antiparasitic medications are the backbone of companion animal healthcare, and a thorough breakdown of where this sector is heading is available in this veterinary pharmaceutical and antiparasitic market analysis. The sector is more dynamic — and more contested — than most pet owners realize.
Why Resistance Is the Industry's Uncomfortable Secret
The veterinary antiparasitics market has a resistance problem that doesn't get enough public attention. Macrocyclic lactones — the drug class that includes ivermectin, milbemycin, and moxidectin, which underpin most heartworm preventives — have maintained effectiveness largely because resistance in heartworm populations has been slow to develop. That luck may not hold indefinitely.
In livestock, the picture is already alarming. Benzimidazole resistance in gastrointestinal nematodes affecting sheep and cattle is widespread across Australia, New Zealand, and large parts of South America. Australia's sheep industry has documented multi-drug resistance in barber's pole worm populations that is genuinely difficult to manage. The companion animal sector has watched this unfold with some concern, because the same biological pressures — high drug exposure, rapid parasite reproduction cycles — are theoretically present.
The Flea and Tick Market Is a Different Story
While internal parasite prevention has been dominated by a relatively stable set of drug classes, the external parasite market has seen genuine innovation. The introduction of isoxazoline-class compounds — fluralaner (Bravecto), afoxolaner (NexGard), sarolaner (Simparica) — fundamentally changed the flea and tick prevention market after 2013. These oral products offered superior efficacy to topical treatments, eliminated the mess and contact risk of spot-ons, and came with dosing intervals that improved owner compliance.
The competitive dynamics in this space have been intense. Zoetis, Elanco, and Merck Animal Health have fought hard for market share, and generic entry has begun for some products as patents expire. The veterinary antiparasitics market overall has benefited from pet humanization trends driving premium product adoption, but pricing pressure from online pharmacies and big-box retailers has complicated the margin picture for manufacturers and independent veterinary practices alike.
The Livestock Side of the Equation
Companion animal products capture the most consumer attention, but livestock antiparasitics remain a dominant segment by volume and a critical one by agricultural impact. Internal parasites — particularly gastrointestinal worms in cattle and small ruminants — cost the global livestock industry billions annually in production losses, treatment costs, and animal mortality.
Brazil, which has one of the world's largest cattle populations, has become a focal point for research into anthelmintic resistance management. Strategic dosing protocols, refugia-based approaches that leave some animals untreated to maintain susceptible parasite populations, and integrated parasite management programs are all being implemented with varying degrees of success. The challenge is that best practices developed in research settings are difficult to implement consistently across operations that range from small family farms to industrial feedlots.
The Market's Next Phase
The pipeline for novel antiparasitic compounds has been thin compared to other veterinary therapeutic areas. Much of the industry's recent innovation has been formulation-driven — new delivery systems, combination products, extended-release mechanisms — rather than genuinely new mechanisms of action. That may be starting to change, with RNA interference-based approaches and novel small molecule candidates entering earlier stages of development.
The companies that navigate the next decade well will be those that combine efficacy with resistance stewardship messaging — a harder commercial task than it sounds, because the most responsible antiparasitic use is often the least frequent.
About the Creator
Marvin M. Gibsonv
Marketing enthusiast and Digital Marketing Executive sharing practical tips on SEO, content creation, social media marketing, and online growth. Learn, grow, and stay ahead of digital trends.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.