
Toyota Is Targeting Solid-State EV Batteries for 2027–2028. The Factory Is Still the Hard Part.
Toyota is targeting 2027–2028. But dendrites, solid-to-solid contact, manufacturing yield, and cost still stand between a working prototype and a battery you can buy.
Editorial note: I use AI tools to assist with research, drafting, fact-checking, and editing. The analysis, opinions, engineering interpretation, and final editorial decisions are my own.
Toyota's current public target for its first solid-state battery vehicles is 2027 to 2028. In October 2025, the company received an official production license for the technology in Japan.
So why do so many people who have worked on battery production lines treat that date with caution?
After more than two decades in electronics manufacturing, I've seen the same problem repeatedly: proving that a technology works is only the beginning. The harder question is whether you can manufacture it repeatedly, at volume, at acceptable yield, and at a price customers will pay.
Solid-state batteries are running directly into that problem.
The technology works. The manufacturing doesn't, at least not yet. The gap between those two facts is where billions of dollars and nearly three decades of research have quietly disappeared.
What Actually Changes Inside the Cell
Most battery explainers jump straight to the exciting part. The foundation matters more, because it explains the delay.
Today's EV batteries are lithium-ion cells. A liquid electrolyte carries lithium ions between the anode and cathode every time the battery charges or discharges. It isn't glamorous, but it powers millions of vehicles, and the industry has spent more than twenty years learning to manufacture it cheaply and reliably.
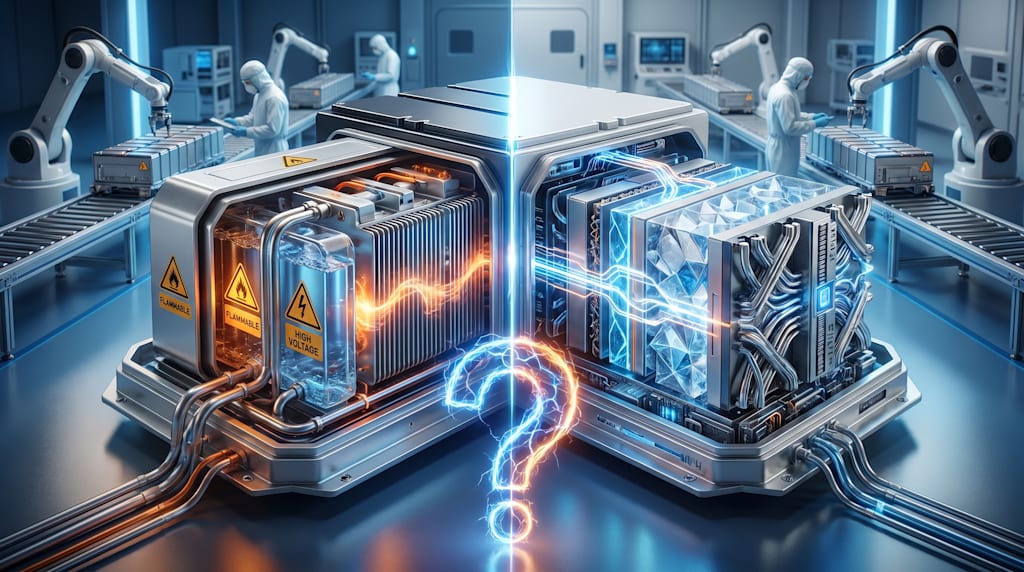
A solid-state battery replaces that liquid with a solid electrolyte. Depending on the company, that solid might be a ceramic, a polymer, or a sulfide-based compound. On paper, that single change opens up several benefits:
Higher energy density. A solid electrolyte can be paired with a lithium-metal anode instead of graphite, and lithium metal has a much higher theoretical energy density.
Better safety, with caveats. The flammable liquid is gone. But lithium metal brings its own reactivity risks when there's a manufacturing defect or physical damage. Safer, not risk-free.
Potentially longer life. Fewer chemical side reactions at the electrode surface could mean slower capacity fade.
Notice the hedging. "Theoretical." "Potentially." Those words are doing real work.
Fast charging is the most oversold claim. Some side reactions that limit charge rates in liquid cells don't occur the same way in solid ones, which is genuinely promising. But many solid electrolytes have lower ionic conductivity than liquid electrolytes at room temperature. In plain terms, ions move through them more slowly. That's an unsolved research problem, so faster charging is conditional, not guaranteed.
Lifespan has the same catch. Some current solid-state prototypes show worse cycle life than top-tier lithium-ion cells.
The industry is taking the technology seriously anyway. Toyota, QuantumScape, Solid Power, Samsung SDI, and CATL have all published research and roadmaps. The U.S. Department of Energy's Office of Manufacturing and Energy Supply Chains selected Solid Power for up to $50 million to build out continuous production of sulfide-based solid electrolyte.
The promise is real. The delivery is the problem.
Two Failure Modes That Get Blurred Together
When solid-state cells fail in labs and on pilot lines, and they still fail regularly, the cause usually traces back to one of two problems. Popular coverage tends to mix them up.
Dendrites
Every time the battery charges, lithium has to plate evenly back onto the anode. Sometimes it doesn't. Instead, it grows into thin, spiky metal filaments called dendrites, which push through the electrolyte toward the cathode. If one reaches it, the cell shorts internally.
Conventional lithium-ion cells have dendrite problems too. The difference is how the electrolyte responds. A liquid can shift and maintain contact as a dendrite grows. A rigid solid has no give, so uneven plating is harder to tolerate, and the failure is harder to contain. A 2026 roadmap on next-generation solid electrolytes, published in Materials Futures (IOP Publishing), treats interfacial engineering, meaning stopping dendrite growth and decomposition at the electrode-electrolyte boundary, as a unifying challenge across materials, processing, and cell design.
Contact loss
The second problem gets far less attention. In a liquid cell, the electrolyte flows into every microscopic gap. A solid can't. As the electrodes expand and contract over thousands of cycles, inside a vehicle dealing with vibration, temperature extremes, and acceleration loads, every void and mechanical mismatch becomes a place where ion flow chokes and capacity fades for good.
A terminology note, because this is where coverage often gets sloppy. The SEI, or Solid Electrolyte Interphase, is a chemical passivation layer that forms on the anode in liquid-electrolyte cells from electrolyte decomposition. What I'm describing here is different: mechanical contact loss between two rigid solid surfaces, sometimes called interfacial contact impedance. Solid-state cells deal with both. They are not the same problem.
Where the Factory Takes Over
This is where a manufacturing background changes how you read the press releases.
A lab hand-assembles a few hundred cells, slowly, with researchers watching every step. A gigafactory has to produce tens of thousands a day, all identical, at a cost that doesn't bankrupt the automaker buying them. Solid-state batteries keep stumbling at exactly that transition, and the reasons are structural.
Stack pressure. Many solid-state designs need constant, uniform mechanical pressure across the cell stack to keep the layers in contact. That pressure has to hold for the life of the cell, through thousands of cycles, in a vehicle operating anywhere from about -20°C to 45°C (roughly -4°F to 113°F). Doing that without adding meaningful weight or cost to the pack is an unsolved systems problem, not a packaging detail.
New processes. Some solid electrolytes need dry-coating or thin-film deposition instead of the wet-slurry coating the lithium-ion industry spent two decades refining. New processes bring new defect modes that nobody has fully mapped.
Moisture sensitivity. Sulfide-based electrolytes in particular are sensitive to moisture, which means tightly controlled production environments. That adds capital cost and operating complexity that never shows up in a lab demo.
Yield. This is the one that decides whether a factory makes money. Yield is the share of cells coming off the line that actually meet spec. Factorial Energy, a solid-state and lithium-metal cell developer, has said publicly that gigafactories need 90%-plus yield just to break even, and that its own pilot line runs around 85%. In a 2026 SEC filing connected to its proposed SPAC merger, Factorial describes state-of-the-art lines as typically targeting 70 to 80% and says its own line has exceeded 85%. Those company-reported figures show the scale of the problem. A process that looks impressive in the lab but can't clear that range at automotive volume has a cost problem, not an inconvenience.
Toyota's history shows how hard this is. Its solid-state commercialization targets have shifted several times across concept demos, prototype milestones, and production dates. The current public target, reaffirmed by executive Keiji Kaita at the Japan Mobility Show, is 2027 to 2028 for initial vehicles. The October 7, 2025 production license is a real regulatory milestone. But a license and a high-volume manufacturing line are very different things.
QuantumScape shows the same gap from the inside. Its separator production process has moved through at least two named generations, Raptor and now a faster process called Cobra, because earlier approaches couldn't hit the throughput and yield automotive-scale demands. In its Q2 2025 shareholder letter, the company wrote that "the challenges of scaling production remain significant." That isn't spin. It's a company being candid about where things stand.
The Semi-Solid Battery That Worked, and Still Got Canceled
NIO shipped a 150 kWh semi-solid battery pack using cells from WeLion New Energy. It isn't all-solid-state; it keeps a small amount of liquid or gel in the electrolyte. It reached 360 Wh/kg at the cell level and 260 Wh/kg at the pack level, and NIO drove one more than 1,000 km on a single charge.
Then NIO discontinued it in late 2025. Industry reporting, including comments attributed to CEO William Li, pointed to cost relative to the range benefit, and limited customer demand at that price, as the major factors.
That detail matters. The chemistry worked. The car drove, and it delivered exceptional range. Customers still didn't want to pay for it. That's an economics failure, not a lab failure, and it happened on a real production line with real buyers.
It's also a reminder that semi-solid and all-solid-state are different technologies. A semi-solid product reaching the market doesn't mean all-solid-state is solved.
What a Realistic Timeline Looks Like
I don't know when solid-state batteries will reach mass-market EVs, and I'd be misleading you if I offered a confident year. Forecasts have shifted repeatedly. Anyone giving you a firm date without heavy caveats is guessing or selling something.
The deployment pattern is clearer than the date. Toyota's reporting suggests early production in the hundreds of tons per year, enough for tens of thousands of vehicles at most, with the first models likely under Lexus, where a higher sticker price can absorb the battery cost premium. Mainstream rollout is generally discussed around 2030, without firm commitments.
Regulation is moving too. China's GB/T 43568-2026, which covers terminology and classification for automotive solid-state batteries, took effect on July 1, 2026. Industry outlets describe it as the world's first national standard of its kind. Before an industry can scale, it has to agree on what it's building, and standards are part of that.
If you want real signals rather than PR noise, these are the ones worth watching:
Pilot production line announcements, not lab demos
Energy density figures verified by a named third party, not internal claims
Cycle life data covering hundreds of full charge-discharge cycles
Automaker partnerships backed by committed capital, not just a research MOU
The Constraint That Matters Most
Solid-state batteries are not vaporware. The physics is sound, and the potential advantages in energy density, safety, and longevity are backed by serious work from credible labs and companies.
But the path from "works in the lab" to "works in a million cars a year" runs through dendrite control, interfacial contact engineering, manufacturing yield, and cost. None of those are solved yet. Of the four, yield is the one that turns every other problem into a financial one, because each unresolved defect mode ends up as scrapped cells on the factory floor.
Solid-state batteries aren't being held back because the underlying idea doesn't work. They're being held back by the part of technology development that rarely makes headlines: manufacturing.
Turning a promising chemistry into something a factory can build reliably, at high yield, in enormous volumes, and at a price customers will actually pay is the real engineering challenge.
And ultimately, that's what puts batteries in cars.
Sources
Toyota production license and roadmap: Shanghai Metals Market
QuantumScape Q2 2025 Letter to Shareholders: SEC EDGAR
Solid Power DOE award: Solid Power press release
DOE technical report: Challenges for and Pathways Toward Solid-State Batteries, OSTI.GOV
2026 solid-electrolyte roadmap: Materials Futures, IOP Publishing
Yield benchmarks: Factorial Energy; Factorial's own disclosure in Cartesian Growth Corp III SEC Form S-4/A
NIO 150 kWh semi-solid pack launch: CarNewsChina
NIO discontinuation: Electrive
China GB/T 43568-2026: Shanghai Metals Market; Battery Design
About the author: Imran Valiani is a Sales Director in PCB electronics manufacturing with 20+ years of industry experience. He writes about the hardware layer of technology — semiconductors, PCB manufacturing, AI infrastructure, embedded systems, and emerging electronics — at Silicon to Software.
Read more engineering analysis at SiliconToSoftware.com
About the Creator
Imran Valiani
Engineering the hardware behind modern technology. Silicon to Software covers semiconductors, PCBs, AI infrastructure, embedded systems, and emerging hardware — with practical analysis from 20+ years in electronics manufacturing.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.