Tencent Q1 Revenue Rises 9 Percent as AI and Cloud Growth Offset Gaming Slowdown
CEO Ma Huateng cites significant initial progress on AI products with WorkBuddy leading China agentic services market despite revenue miss versus estimates
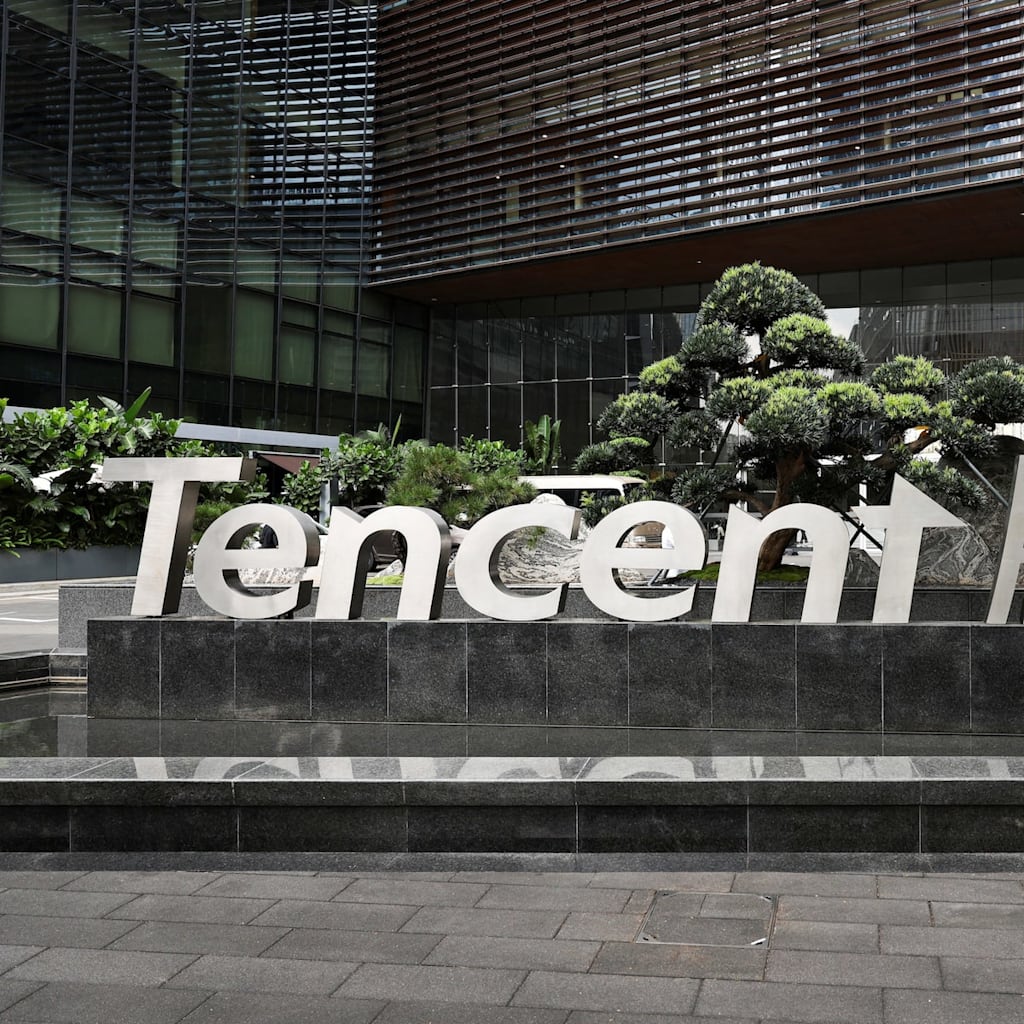
Read Time 6 minutes Tags Tencent AI Cloud Computing Gaming China Tech Earnings WorkBuddy Chinese tech giant Tencent on Wednesday reported revenues rose 9 percent in its first quarter 2026 earnings but missed analyst expectations Revenue came in at 1965 billion Chinese yuan 289 billion dollars compared to estimates of 199 billion Chinese yuan Domestic games revenues were 454 billion Chinese yuan up 6 percent year on year but a slowdown compared to the 24 percent rise the segment saw in the first quarter of 2025 We started 2026 by making significant initial progress on our new AI products as well as continuing to utilise AI to grow our existing core businesses Ma Huateng chairman and CEO of Tencent said in a statement Our core businesses continued to grow their engagement revenue and profit providing the cash flow to fund our AI investments as well as use cases for future AI deployment he added AI and cloud as growth drivers One Business Services and AI demand Tencent fintech and other business services segment brought in 60 billion Chinese yuan in the first three months of the year up from 55 billion Chinese yuan during the same period a year ago Business Services revenues rose by 20 percent year on year with growth led by increased cloud services revenues supported by higher demand across domestic and international markets including demand for AI related services the company said It added its AI agent tool WorkBuddy was the most popular agentic service in China The firm AI investments are already delivering a return Ivan Su senior equity analyst at Morningstar told CNBC An upgraded AI driven ad recommendation model drove an acceleration in advertising revenue growth to 20 percent he said AI spending is tracking in line with the full year numbers management previously guided to Two Gaming revenue slowdown Domestic games revenues were up 6 percent year on year a slowdown compared to the 24 percent rise the segment saw in the first quarter of 2025 Su flagged the slowdown in gaming revenue growth as a negative adding that the slowdown appeared to be driven mostly by the timing shift of Chinese New Year affecting revenue recognition rather than any underlying demand problem The timing effect means that underlying user engagement and paying user trends remain stable but quarterly recognition is lumpy Three AI product development Tencent stated that it made significant initial progress on new AI products in the first quarter The company is leveraging its WeChat ecosystem cloud infrastructure and data assets to build AI agents and copilots for enterprise and consumer use WorkBuddy being the most popular agentic service in China indicates traction in workplace automation and workflow augmentation This aligns with a broader trend where Chinese tech firms deploy AI agents inside their own ecosystems before opening them to external developers Financial and strategic implications One Margin and investment balance Tencent is using cash flow from core businesses including gaming advertising and payments to fund AI investments The strategy mirrors US peers Meta and Google where core ad businesses subsidize AI infrastructure and model training The risk is that if gaming and ad growth slow further the capital available for AI expansion shrinks Tencent guidance that AI spending is tracking in line with full year numbers suggests disciplined allocation for now Two Cloud competitiveness in China Tencent cloud growth is supported by domestic demand for AI inference and training as Chinese enterprises build applications on domestic models to comply with data residency and regulatory requirements Competition from Alibaba Cloud Huawei Cloud and Baidu Cloud remains intense but Tencent advantage lies in integration with WeChat enterprise services and fintech products The 20 percent growth in Business Services revenue indicates that AI demand is translating into billable cloud usage Three Advertising recovery driven by AI An upgraded AI driven ad recommendation model drove an acceleration in advertising revenue growth to 20 percent This shows that generative AI and recommendation systems can improve ad targeting and yield even in a slowing macro environment The improvement also suggests that Tencent first party data and ecosystem lock in remain defensible against short form video competitors like Douyin Market and policy context One China AI ecosystem dynamics Tencent positioning as a leading agentic service provider puts it in direct competition with Alibaba ByteDance and Baidu for enterprise AI adoption The market is fragmented across verticals with no single player dominating yet WorkBuddy popularity gives Tencent an early lead in workplace AI but sustainability depends on model performance integration depth and enterprise trust Two Regulatory environment China AI regulation remains supportive of domestic model development while restricting foreign model access Export controls on advanced chips continue to constrain training capacity for all Chinese players Tencent strategy of optimizing inference efficiency and building smaller specialized models aligns with the hardware constraints Three Valuation and investor focus Investors are watching two things whether AI investments convert into durable revenue growth and whether gaming can reaccelerate post Chinese New Year timing effects The 9 percent revenue growth rate is solid but below expectations and the stock reaction will depend on forward guidance for AI monetization and cloud margins What to watch First monetization of WorkBuddy and other AI agents through subscription or usage based pricing Second cloud gross margin trajectory as AI workloads scale Third gaming pipeline and international expansion to offset domestic timing effects For enterprise buyers Tencent AI tools offer deep integration with WeChat and WeCom which are critical for reaching Chinese consumers and employees For developers the ecosystem provides distribution but requires alignment with Tencent platform policies Do you think Tencent AI agents can sustain leadership against Alibaba and ByteDance in China enterprise market Share your view in the comments
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.