
Shrinkable Lidding Films Market: The Quiet Packaging Arms Race
Fresh food shelf life, sustainability pressure, and cold chain expansion are rewriting the rules of lidding film specification.
The Packaging Layer Nobody Talks About — Until It Fails
Imagine a refrigerated salmon fillet at your local supermarket. The film stretched tightly over the tray isn't just decoration — it's doing critical work: maintaining a controlled atmosphere, preventing contamination, extending shelf life by days, and surviving a cold chain that spans multiple countries. That film is almost certainly a shrinkable lidding film, and the Shrinkable Lidding Films Market is quietly becoming one of the more consequential corners of the global packaging industry, driven by food safety standards, retail aesthetics, and the relentless push for longer shelf life.
Want to see the numbers behind this trend? Access your free industry sample report before reading further.
More Than a Wrapper
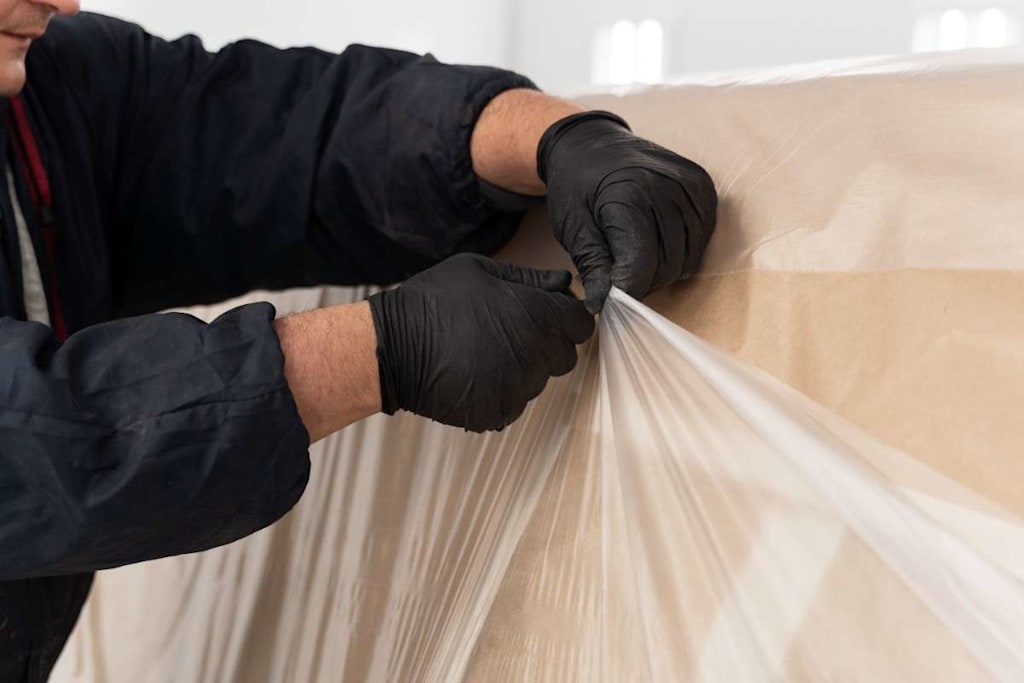
Shrinkable lidding films are heat-sealed, thermoformed covers applied to trays and containers, most commonly in fresh protein, ready-to-eat meals, and modified atmosphere packaging. When heat is applied, they conform tightly to the tray geometry — creating a tamper-evident, airtight seal that passive packaging simply can't match.
The functional benefits compound quickly. Retailers get a consistent, visually clean presentation across thousands of SKUs. Manufacturers get reduced oxygen transmission rates that measurably extend product freshness. Logistics operators get packaging that survives handling and stacking without delamination or seal failure.
What makes the current market moment interesting is how these functional requirements are colliding with sustainability pressure. Brands that spent years optimizing for barrier performance are now being asked to achieve the same results with less material, recyclable substrates, or mono-material structures that can actually be processed at end of life.
Where the Real Demand Is Coming From
Fresh and processed meat remains the dominant application — a category where atmosphere control directly determines whether a product reaches a consumer in a saleable state or becomes shrinkage on a retailer's P&L. But the growth story in the sector isn't just volume; it's specification complexity.
Take the European ready-meal market as a reference point. Retailers in the UK, Germany, and France are increasingly specifying dual-ovenable lidding films that can go from refrigerator to microwave or conventional oven without changing packaging. This requirement alone narrows the supplier field significantly — not every film chemistry handles the transition from cold seal integrity to high-temperature performance without compromising barrier properties.
Research covering the Shrinkable Lidding Films Market highlights how this specification escalation is reshaping competitive dynamics, with suppliers investing heavily in co-extrusion technology to build more functionality into thinner film gauges.
Asia Pacific is the fastest-growing regional market, with organized retail expansion in India, China, and Southeast Asia driving adoption among fresh food processors who previously relied on less sophisticated packaging formats.
The Sustainability Tension
Here's where the market gets genuinely complicated. Most high-performance shrinkable lidding films are multi-layer co-extrusions — combining polyester, polyamide, polyethylene, and barrier layers in precise sequences. Each layer serves a function. The problem is that this compositional complexity makes mechanical recycling nearly impossible with current infrastructure.
The industry's response is bifurcating. Some manufacturers are developing mono-material PE or PET-based structures that sacrifice minimal barrier performance in exchange for recyclability credentials. Others are doubling down on lightweighting — arguing that a thinner, more efficient multi-layer film has a lower overall environmental footprint than a thicker mono-material alternative, even accounting for recyclability.
Neither path has won the market yet, which is actually creating near-term opportunity. Brands that can credibly communicate a packaging sustainability story — backed by lifecycle assessment data — are differentiating at the shelf in a way that commoditized packaging can't support.
The Decade Ahead
The market trajectory here is built on foundations that aren't going away: global protein consumption growth, cold chain expansion in developing economies, and food waste reduction as a regulatory and commercial priority. Packaging formats that can demonstrably extend shelf life, reduce in-store waste, and survive increasingly complex supply chains have structural tailwinds.
The manufacturers, brands, and retailers who understand where the performance bar is moving — and which film technologies are actually capable of meeting it — will be better positioned than those still evaluating packaging as a commodity input. Shrinkable lidding films are a small line item on a bill of materials, but the decision about which one to specify carries disproportionate downstream consequences.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.