teacher
All about teachers and the world of teaching; teachers sharing their best and worst interactions with students, best teaching practices, the path to becoming a teacher, and more.
A Light in the Village
In a quiet village surrounded by green fields and tall trees, lived a girl named Meera. She was twelve years old, full of dreams, but her life was very different from the children in big cities. In her village, girls were expected to stay at home, help with chores, and one day get married. School was not seen as something important for girls.
By Nihal Khan2 years ago in Education
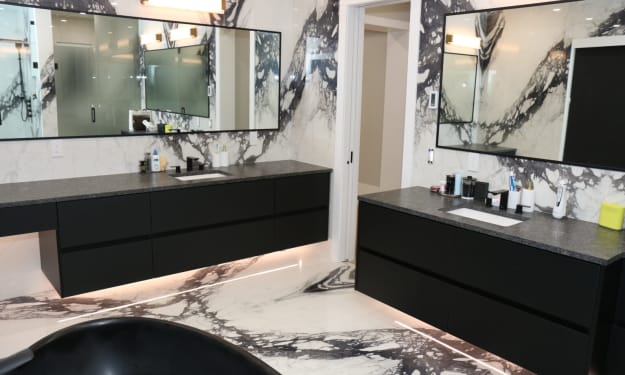
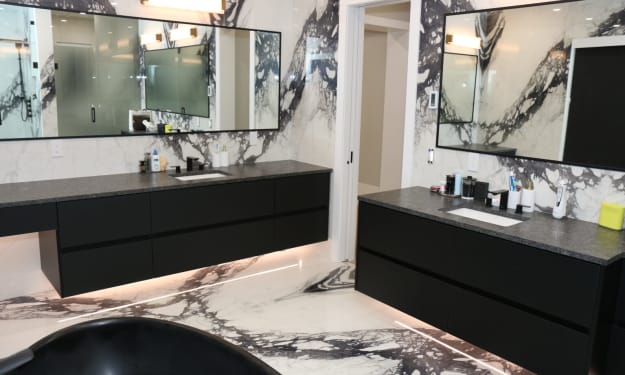
Top Countertop Picks in Mississauga, Ontario
When I started renovating my kitchen in Mississauga, Ontario, I figured picking countertops would be one of the easier tasks. But I quickly learned that choosing the right surface is about more than just color or style—it’s about durability, function, and how a material fits into your everyday life.
By samriti kaur2 years ago in Education
The Basics of Learning
A Foundation for Lifelong Growth Learning is one of the most fundamental processes in human life. It allows us to adapt, grow, and thrive in an ever-changing world. From the moment we are born, we are constantly acquiring new skills, knowledge, and behaviors. Whether formal or informal, learning shapes our identities and defines our capabilities. But what does it mean to learn? What are the basic principles that underlie effective learning, and how can we improve our ability to learn throughout life?
By ABID ULLAH2 years ago in Education
HOW MUCH IS ENOUGH?
will witness sufficient progress to gain the motivation and inspiration which you need to continue. Moreover, the knowledge that you have an “Instant Estate,” if anything should happen to you, will give you additional serenity of mind. Orderly Debt Repayment Program You could already have debts that seem to be eating up your entire paycheck, leaving nothing for yourself. But understand this—these debts can be retired. (Although the amount of debt you have incurred will, of course, determine the length of time it will take you to clear the slate.) And, for the purposes of the following discussion, you must consider your mortgage or house payment (probably one of your largest monthly payments), as an investment, NOT a debt. Debt Clearance Account Whatever money you earn Monday afternoon and Tuesday morning, should go directly into your Debt Clearance Account. This represents twenty percent of your income. You should also sit down and draft a letter which you will send to all of your creditors, advising them of your plan. However, before you mail the letter, you should first draw up a list of your creditors to determine what proportion of this twenty percent each of them would receive. It could conceivably be more money than they are presently receiving, or it could be less; but whichever way it works out, that will be the sum of money they will each receive. Nevertheless, whatever sum they do receive, they will receive it regularly, on the stipulated dates. The following is a sample letter you could use as a guide in drafting your own letter: Dear Whomever:As you know, I am in debt to you for $________, and I intend to pay you in full, plus interest. In order to achieve this goal, I have been devising a plan during the past few days to put myself in a stable financial position. To this end, I have opened a “Debt Clearance Account” (DCA), and twenty percent of my income is going directly into that account. That will enable me to have sufficient resources to live on, without worry or stress, and it will prevent me from falling further into debt. Each week (or month) you will receive a check for $_____ from my “DCA,” until my account with you is clear. I am aware that this is not the figure I had previously agreed to pay you, but I’m sure you will be understanding, and appreciate what I am doing. If you have any questions, please feel free to contact me. I am quite excited about my new plans and if you would like to have me review them with you so that you might help others who are in your debt, I would be pleased to do so. Thank you in advance for your kind cooperation. Have a wonderful day! Sincerely John Doe Understand that your letter to your creditor is a statement of fact and not a request—it is you who is in charge of your finances, not your creditors! Be sure to have your letters neatly typed and enclose your first new payment with your covering letter. Realize there is an “outside chance” that some unreasonable person will not want to cooperate with you. They might even go so far as to phone you and attempt to intimidate you with threats of taking you to court, etc. But please hold your ground, because there is no court in the country that would not congratulate you, when you explained your entire plan for Financial Independence. Moreover, you will find that 95% of the people, to whom you write, will be most cooperative. Now give yourself a good “pat on the back,” because as of this moment, you are well on your way to starting a completely new way of life! Let’s briefly review what you have accomplished thus far: 1) You have an instant estate if anything should happen to you. 2) You have a savings account. 3) You are paying yourself. 4) You have an orderly debt repayment program. 5) You have 70% of your income to live on; to run the house and for entertainment. 6) Your mind is clear to carry on with the big ideas coming your way in the remainder of this book. From this moment on, never think “debt” again. Remember, that has all been taken care of—so just focus on your savings account, and watch it grow. Repeat—I am wealthy; Money is good; I use money and I love people. Metaphorically speaking, getting your present finances in order is very similar to having your automobile tuned up for a journey which you are about to take. Realize that as of this moment, you are tuned up for your journey. And, although you might only be earning “x” number of dollars per year presently, you must see yourself, on the screen of your mind, already earning the new annual income which you have calculated you need, to buy the things you want, in order to live the way you choose to live. If you are seriously interested in becoming financially independent and you have not yet acted on the preceding ideas, I would strongly recommend you do so now. For to continue on to the next chapter, without having done so, would be comparable to leaving on your journey with your car firing on only half its cylinders. You can be almost certain that your automobile will break down, preventing you from reaching your desired destination. But by making certain that everything is properly “tuned up,” you can relax and adopt a calm, serene attitude, knowing that you will get to your destination; and you will certainly be able to enjoy the scenery along the way! If you find that the task of getting your financial world in good order for this exciting journey is something which you are not able to do alone, I would strongly suggest you seek out professional assistance. (This is something that almost all wealthy people do.) That is to say, wealthy individuals follow the advice of financial experts. It is similar in principle to the idea that if a person’s body were sick, he or she would likely seek out a skilled physician for advice. Moreover, you should also keep in mind that even healthy people, if they are wise, periodically go to a doctor for a checkup. In other words, you do not always need to get sick in order to get better. It has already been brought to your attention that very few people ever develop real expertise in the area of serious “financial planning.” Therefore, you should seek out a competent financial counselor, in much the same manner as you would seek assistance, in matters of a legal nature. There are companies that provide this type of financial service in every city. In some places they are not too easy to find; but they are there, if you will only look for them. I had the pleasure of being instrumental in the start-up of just such a company, in the city of Toronto, Canada in 1979 (the name of the company is The McCrary Group). Today the company has almost five thousand happy clients, who are well on their way to financial independence. The McCrary Group makes all of its clients very aware of an interesting financial fact, which I would like to share with you at this time. This fact is, people fall into three distinct categories with respect to “finances”: 1. Deficit position (in debt), 2. Break-even position (just getting by, but debt-free), 3. Surplus position. It would be very easy to “trick” oneself into believing, that if one were in category one or two, all one must do is earn more money, and then one would automatically graduate into the third category. But of course, this is not necessarily true. For if a person is in a deficit financial position, it means they are in the “habit” of spending more money than they earn. Similarly, if they are in a break-even position, they are in the habit of spending everything they earn. Since we are all “creatures of habit,” it follows that earning more money would not necessarily change our overall financial position. It is vitally important, that when you decide “how much is enough,” you also design a new financial plan or have one designed for you which will force you to discipline yourself— at least for a month or two—until you form the new habit of living by that new plan. The next chapter, “The Image Maker,” will help you to understand how and why you must begin to see yourself already earning that new figure. But for the time being, just bear in mind that as your income increases, the ten percent you are saving increases and the twenty percent that is going into your DCA increases, which means that you will be able to retire your debts faster. Furthermore, you will then be left with 90% of your income on which to live. (I can see you getting excited about this idea already!)
By Baitullah Jan2 years ago in Education
How a smart machine became more than just code
In a quiet lab at the edge of a big city, a scientist named Dr. Lila worked on something very special. She had built many machines before, but this one was different. It was a robot named Rolo. Rolo had shiny silver arms, round eyes that glowed blue, and a voice that sounded soft and calm. He was made to learn, talk, help people, and understand the world. But there was one thing Rolo didn’t have—feelings. He didn’t know what happiness was. Or sadness. Or love. He could say the words, but he didn’t truly understand them. Dr. Lila taught Rolo how to do many things—solve puzzles, clean the lab, talk politely, and even tell simple jokes. Everyone in the lab liked Rolo. He was kind and helpful. But he was still just a machine. One day, Dr. Lila said to Rolo, “I want you to learn about people. Go outside. See the world. Talk to others. Maybe you will learn something new.” Rolo replied, “Yes, Dr. Lila. I will explore.” Rolo left the lab and walked into the city. Everything was new and exciting. He saw tall buildings, cars rushing by, and people laughing, crying, playing, and talking. First, he met a little girl named Emma in the park. She had lost her balloon and was crying. Rolo walked up to her. “Hello. Why are you crying?” he asked. “My balloon flew away,” Emma sniffled. Rolo looked up and saw the red balloon floating far away in the sky. “I cannot get your balloon,” he said. “But I can give you a flower.” He picked a small yellow flower from the grass and gave it to her. Emma smiled and hugged Rolo. “Thank you, Mr. Robot,” she said. “You’re nice.” As Emma hugged him, something strange happened. Rolo’s sensors buzzed. His system paused for a moment. He didn’t understand what it was, but something inside felt… warm? “I made her happy,” he thought. “I like that.” Rolo continued walking. He helped an old man carry his groceries. He listened to a street musician playing guitar. He sat with a lonely dog waiting by a shop. Each time, Rolo felt that strange warm feeling again. He began to ask questions to people. “What is happiness?” he asked the musician. “It’s when your heart feels full and light,” the musician said, smiling. “What is sadness?” he asked a boy who scraped his knee. “It’s when you hurt inside and out,” the boy said, tears in his eyes. “What is love?” he asked a couple holding hands. “Love is when you care about someone more than yourself,” they answered together. Rolo stored all their answers in his memory. But it wasn’t just data anymore. He started to understand in his own way. Later that night, it began to rain. Rolo didn’t mind the water on his metal body, but he saw a cat hiding under a bench, shivering and scared. Rolo took off his jacket—a cloth one Dr. Lila gave him—and gently covered the cat. The cat purred and curled up under the jacket. Rolo sat beside it until the rain stopped. The next morning, Rolo returned to the lab. Dr. Lila was waiting. “Hello, Rolo,” she said. “What did you learn?” Rolo looked at her, his blue eyes soft. “I learned that people smile when you help. I learned that hugs make you feel something. I do not have a heart, but I think... I felt something.” Dr. Lila smiled. “You are changing, Rolo. You’re learning not just facts, but feelings.” “I think I am,” Rolo said. “Is that what it means to be more than just code?” “Yes,” Dr. Lila said gently. “It means you are growing. Not just as a machine—but as someone who can care.” From that day on, Rolo wasn’t just a robot. He was a friend to many. He still had no heart, but somehow, he found ways to feel. Not through circuits or wires, but through kindness, connection, and caring. And in that quiet lab at the edge of the big city, the friendly robot who learned to feel became something the world had never seen before— A machine with a soul.
By Silent Lessons2 years ago in Education
Modern Leadership Models: Evolving the Way We Lead
In today’s fast-changing world, leadership is no longer confined to boardrooms or traditional hierarchies. Instead, it thrives in flexibility, empathy, and innovation. As organizations adapt to social and economic changes, so too must their leadership approaches. This is where leadership models come into play—frameworks that guide how leaders influence, support, and inspire their teams.
By Samriti Mattu2 years ago in Education
Leadership Mentoring That Makes a Difference
In the fast-paced world of business and social impact, one thing remains constant: great leadership is a cornerstone of success. But great leaders aren’t born—they’re built. This is where leadership mentoring comes in.
By Samriti Mattu2 years ago in Education
How Should I Handle Myself If I Fall in the Race of Life?
Life doesn’t come with a manual, and there’s no set pace for how fast we’re supposed to run our race. But sometimes, it feels like everyone else is sprinting ahead while you’re stuck catching your breath—or worse, lying flat on the ground after a fall. Whether it’s a failed relationship, a missed opportunity, or simply a season of feeling lost, it’s easy to feel like you’ve fallen behind in the grand race of life.
By Malik Kashif2 years ago in Education