
NSE FY26 Results: The 15% PAT Drop Nobody Fully Explained | Planify
Published: May 2026 | Category: Markets & Exchanges | Reading Time: ~8 mins | Planify
Introduction
India's largest stock exchange just closed what looks like a rough year on paper. NSE's profit after tax fell 15% in FY26, EPS dropped from ₹49 to roughly ₹42, and EBITDA margins compressed noticeably. On the surface, that sounds bad.
But the full picture is far more layered. A closer look at the quarterly breakdown, the regulatory context, and the emerging growth drivers tells a very different story — one where the damage was largely concentrated in the first three quarters, and the final quarter showed a clear, strong recovery.
NSE FY26 at a Glance: Key Numbers You Need to Know
Before diving into the reasons and implications, here is a clean summary of all the critical numbers from NSE's FY26 consolidated results. This snapshot covers income, profitability, per-share metrics, and the dividend declared by the board.
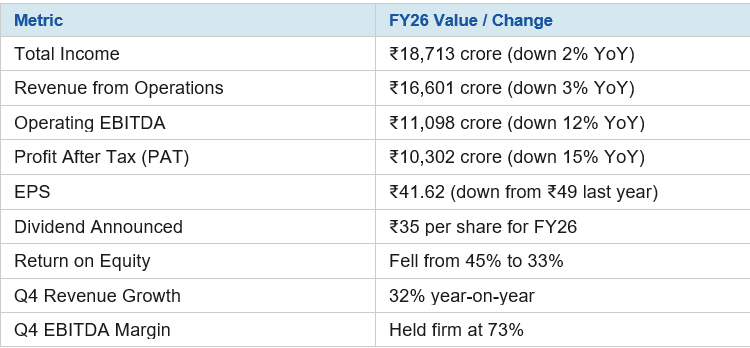
One figure that stands out beyond the full-year numbers is the Q4 performance. Revenue from operations grew 32% year-on-year in Q4 FY26. EBITDA grew 30%. Options premium average daily volumes surged 43% quarter-on-quarter to ₹76,375 crore per day. These numbers tell you that the underlying business did not break — it bent under regulatory pressure and then began straightening out.
Also worth noting: on a normalised basis, stripping out the SEBI settlement fees and other one-time items, consolidated profit before tax fell only 5% — not 15%. The reported PAT decline is real, but it significantly overstates how much the core business actually deteriorated.
Full Year vs Q4: Why the Headlines Are Misleading
The biggest mistake most readers will make with NSE's FY26 results is treating the full-year numbers as a single story. They are not. FY26 was effectively two very different years stitched together — a difficult first three quarters and a sharply recovering fourth quarter.
The full-year PAT decline of 15% came almost entirely from the cumulative impact of Q1, Q2, and Q3. The SEBI F&O circular hit in October 2024 — right at the start of Q3 — and its effect was immediate and severe. Options volumes dropped. Transaction revenues contracted. The cost base, however, kept rising regardless.
By Q4, the market had adjusted. Traders found new patterns. Options volumes stabilised and then surged. NSE's Q4 FY26 normalised profit before tax grew 22% year-on-year and 20% quarter-on-quarter. That is not the performance of a business in structural decline. That is a business that absorbed a regulatory shock and came out the other side.
This distinction matters enormously for how you think about FY27. If the damage was structural, the earnings pressure continues indefinitely. If it was cyclical and regulatory — which the Q4 data strongly suggests — then the base effect alone will make FY27 look considerably better, and actual growth drivers could make it look significantly better still.
Why Did NSE's Profit Fall in FY26? The Four Real Reasons
Most commentary on NSE's FY26 results stops at blaming SEBI's F&O rules. That is true but incomplete. There were four distinct forces at work, and each one contributed meaningfully to the ₹1,886 crore PAT decline. Together they account for every rupee of the shortfall — no mystery, no ambiguity.
The SEBI F&O Circular Hit NSE Harder Than Anyone Else
In October 2024, SEBI fundamentally restructured India's equity derivatives market. The changes included fewer weekly expiries, larger lot sizes, and higher minimum contract values. The stated goal was reducing retail speculation. For NSE, the consequences were severe.
The reason NSE was hit harder than any other exchange is structural. Equity options alone account for 77% of NSE's total transaction revenue. When that single segment faces a regulatory disruption of this scale, there is nowhere else to hide. Options average daily volumes on a premium basis fell from ₹62,449 crore per day in FY25 to ₹57,662 crore in FY26. Cash market ADV fell 7% year-on-year. Equity futures ADV fell 15%. After accounting for tax, the combined volume decline knocked approximately ₹420 crore off consolidated profits.
SEBI Settlement Fees Were a Large and Unexpected Hit
NSE booked ₹1,432 crore in SEBI settlement fees in FY26, up from ₹670 crore the year before. These relate to ongoing regulatory proceedings, including matters stemming from the co-location episode that has followed the exchange for years. After tax, this added approximately ₹556 crore to the profit decline — the single largest contributor to the earnings shortfall.
This is a particularly uncomfortable line item because it is not operational. It does not reflect how the core exchange business is running. It reflects unresolved legacy issues. The good news, if there is any, is that these are by definition non-recurring — they should not repeat at the same scale in FY27.
Discontinued Operations Income Collapsed
NSE earned ₹582 crore from discontinued operations in FY25. In FY26, that figure fell to just ₹123 crore — a direct ₹459 crore hit to reported PAT with no operational offset anywhere else in the business. This is a clean, mechanical reduction that flows straight through to the bottom line.
The Cost Base Kept Rising Regardless of Revenue
Technology spending rose 29% to ₹1,315 crore. Total other expenses surged 44% year-on-year to ₹3,790 crore. CSR expenses jumped to ₹230 crore. The new Labour Codes created a ₹126 crore one-time charge in Q3. After tax, this cost inflation contributed roughly ₹430 crore to the profit decline.
These cost increases were not irrational — NSE is investing in technology infrastructure, new segments, and compliance. But the timing was painful. Revenue was under pressure at the same moment the cost base was expanding. That combination compressed margins across the year.
Put it all together and you get a precise accounting: lower transaction charges (−₹420 crore), SEBI settlement fees (−₹556 crore), discontinued ops decline (−₹459 crore), higher costs (−₹430 crore), lower associate profit share (−₹21 crore), partially offset by lower income tax (+₹153 crore) — and you land exactly at the ₹1,886 crore PAT decline. Every rupee accounted for.
NSE vs BSE: Who Won FY26 and Why the Same Rule Hit Them Differently
While NSE absorbed a 15% PAT decline, BSE had one of its best years in recent memory — with estimates suggesting PAT growth of around 65% in FY26. How does the same regulatory change that hurt NSE end up benefiting BSE? The answer is the weekly expiry rule.
Before October 2024, NSE dominated every expiry day of the trading week. Nifty on Thursday, Bank Nifty on Wednesday, FinNifty on Tuesday, MidCap Nifty on Monday. BSE had essentially no meaningful F&O volumes to speak of. SEBI's new rule — one weekly expiry per exchange — forced NSE to give up most of its expiry calendar in one stroke.
BSE responded intelligently. It positioned its Sensex options expiry on Friday, a different day from NSE's remaining Thursday Nifty expiry. This directly captured the massive pool of displaced retail traders who had nowhere else to go. BSE's Sensex options went from near-zero to lakhs of crores in notional turnover within months.
The structural asymmetry makes this even more striking. NSE's revenue from operations in FY26 stands at approximately ₹18,000 crore. BSE's is around ₹4,200 crore — roughly one-fourth the size. BSE's cost base is correspondingly leaner, which means when incremental options revenue flows to BSE, a far larger percentage drops straight to profit. NSE runs the world's largest derivatives exchange — the clearing infrastructure, the technology backbone, the settlement guarantee fund — and those fixed costs do not disappear when volumes dip.
In valuation terms, markets are pricing this difference clearly. BSE currently trades at around 70 times earnings. NSE trades at approximately 45 times in the unlisted market. MCX is at around 80 times. Singapore Exchange at 35 times. NASDAQ at 30 times. NSE sits comfortably in the middle of its global peer range — not cheap, but not obviously expensive for a near-monopoly exchange of this quality.
What Is NSE Unlisted Share Worth Today?
Here is a peculiar reality of Indian financial markets: the country's largest stock exchange is not itself listed on any exchange. NSE has been trying to go public for years, with its IPO repeatedly delayed due to regulatory issues. In the meantime, it trades actively on the unlisted market at approximately ₹1,900 to ₹2,000 per share.
At ₹1,900, NSE trades at roughly 45 times its FY26 EPS of ₹41.62. Book value per share stands at ₹129.75, implying a price-to-book of around 15 times. That sounds high by conventional standards, but exchange businesses are capital-light near-monopolies — premium multiples are the norm globally.
The Bull Case for NSE Unlisted Shares
If the market assigns BSE-like multiples after NSE's IPO, fair value could reach ₹2,300 to ₹2,500 per share. This scenario requires the IPO to happen reasonably soon, new segments like commodities and debt to scale meaningfully in FY27, and SEBI to refrain from further F&O restrictions — or even relax some existing ones.
The Bear Case for NSE Unlisted Shares
If global exchange multiples prevail instead of Indian peer multiples, the downside scenario points toward ₹1,200 to ₹1,400. This scenario is more likely if the IPO is delayed further, if SEBI adds additional F&O curbs, or if BSE continues gaining options market share at NSE's expense.
The IPO itself is the single biggest valuation catalyst. Management has set a June 15, 2026 deadline to file the DRHP. When the IPO eventually happens, expect a meaningful re-rating — in either direction, depending on market conditions and the multiple the street assigns.
FY27 Growth Drivers: What Could Make NSE's Comeback Story Real
Beyond the cyclical recovery from the FY26 regulatory shock, NSE has several structural growth engines that are genuinely new and genuinely exciting. These were not part of the business two or three years ago, and they are growing at rates that could materially shift the revenue mix over the next few years.
Commodity Derivatives
Commodity derivatives saw average daily turnover grow nearly 10 times in FY26 to ₹91 crore per day. NSE has also tied up with S&P Global Energy for crude oil derivatives on Platts benchmarks, and with IGX for India's first domestically benchmarked natural gas derivatives contract. These are entirely new revenue streams with significant room to scale.
Electricity Futures
The Electricity Futures segment was launched only in July 2025. In its first partial year, it already generated ₹11,098 crore in annual turnover and captured a 72% market share in the segment. As India's energy transition accelerates, this could become a meaningfully large market — and NSE is in pole position.
Mutual Fund Platform
The NSE mutual fund platform processed 12.1 crore orders in FY26, up 91% year-on-year. Revenue from this segment grew 38%. India's SIP culture is still deepening, and passive investing currently accounts for only around 15% of equity assets under management in India — versus over 50% in the United States. As that number grows, the NSE platform sits directly in the path of a multi-decade structural tailwind.
Index Licensing: The Most Undervalued Asset in the Portfolio
NSE Indices currently generates only ₹152 crore in annual revenue, growing at 26% year-on-year. That sounds modest. But consider this: 73% of all passive fund assets under management in India track Nifty indices. If India's passive share grows from 15% to even 30% over the next decade — which is a conservative assumption given global precedent — the value of that index licensing business could multiply several times over.
Index licensing businesses globally are valued at premium multiples because they are pure royalty streams with almost no marginal cost. NSE's index business currently barely registers in most analyst models. That gap between current revenue and long-term potential is one of the most interesting valuation opportunities in the entire NSE investment case.
Debt Market
The Request for Quote platform has grown at a 27% CAGR. The Tri-party Repo segment has grown at a 289% CAGR since FY24. As India's corporate bond market matures — which it must if the country is to sustain its infrastructure investment ambitions — NSE's debt infrastructure becomes increasingly central and increasingly valuable.
Key Risks That Could Slow NSE's FY27 Recovery
The bull case for NSE is compelling. But there are three specific risks that investors need to watch closely, because each one has the potential to materially change the trajectory.
Further SEBI Action on F&O
Any additional SEBI restrictions on equity derivatives — position limits, STT revisions, further expiry reductions — would be damaging. Conversely, any relaxation of existing rules, such as allowing more weekly expiries, would be significantly positive. The regulatory environment is the single biggest swing factor for NSE's near-term earnings.
IPO Delay
Every additional year of delay means investors remain stuck in a thin, illiquid unlisted market with no price discovery mechanism and limited exit options. The IPO is also a valuation re-rating event — without it, the upside scenario simply cannot play out. The June 2026 DRHP deadline is the key date to watch.
BSE Gaining More Market Share
BSE has the regulatory wind at its back and is growing from a small base — a dangerous combination for any incumbent. If BSE continues to capture options volume and begins competing more aggressively in other segments, NSE's structural position weakens over time. The directional shift in market share matters enormously, even if NSE remains far larger in absolute revenue terms.
Final Verdict: Is NSE FY26 a Story of Structural Decline or Temporary Pain?
FY26 was a year of absorbing regulatory shock. The reported numbers — PAT down 15%, EPS down from ₹49 to ₹42, ROE falling from 45% to 33% — look bad in isolation. But the context changes the conclusion significantly.
The underlying business is intact. NSE remains the world's number one equity derivatives exchange by number of contracts. It has 25.7 crore investor accounts. It holds near-monopoly positions across most Indian market segments. The Q4 FY26 recovery was real, broad-based, and strong. Normalised profit before tax grew 22% year-on-year in Q4 — that is not the data of a broken business.
The ₹1,886 crore PAT decline can be attributed entirely to four specific, largely non-recurring factors: SEBI settlement fees (the largest single contributor at ₹556 crore after tax), discontinued operations income falling away, the F&O volume hit, and a rising cost base. Most of these pressures are either one-time in nature or already partially behind the business.
For investors with a medium-term horizon and comfort with regulatory and illiquidity risk, NSE at current unlisted prices is a high-quality bet on India's financial market deepening story. The index licensing opportunity alone could justify a significant re-rating over a five-to-ten-year horizon. The IPO, when it comes, will be the defining catalytic event.
For those needing near-term earnings visibility, clean liquidity, and certainty on regulatory direction — the wait may still be longer than comfortable. The upside is real. So is the uncertainty. That asymmetry defines the NSE investment case in FY27 and beyond.
Disclaimer
This article is based on NSE's Q4 FY26 Investor Presentation dated May 5, 2026. This is not investment advice. All figures are in Indian Rupees crore unless stated otherwise. Unlisted share market price estimates are indicative only.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.