
Who's Actually Paying $230 a Gig for Internet?
Off-roaders, live-streamers, and the last cash grab of a Chinese satellite monopoly—before the low-orbit revolution kills it.
Satellite Data at 28,000 Yuan a Year: Who Uses It, Who Pays, Who Profits
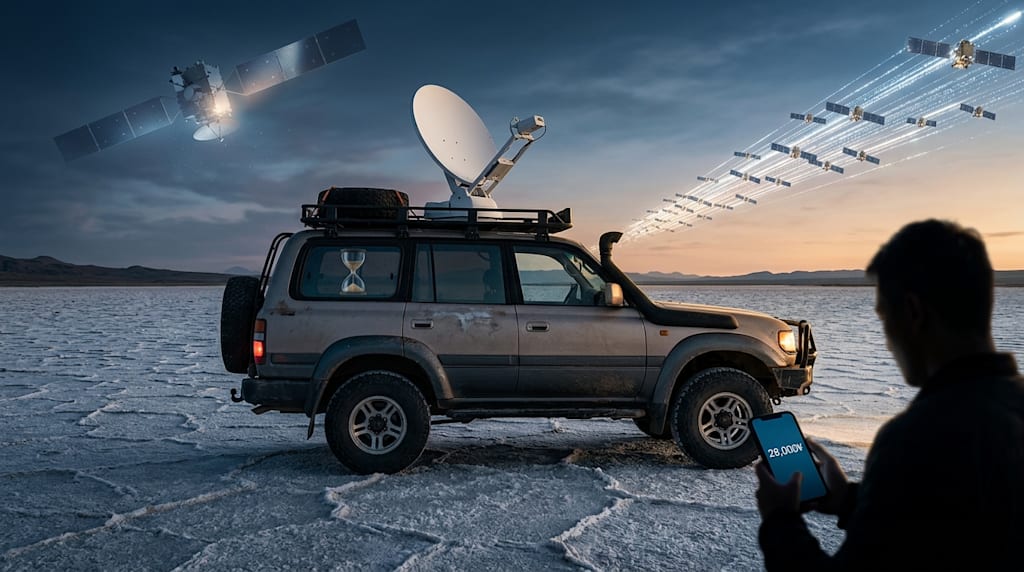
On August 21, 2026, a modified off‑road vehicle pulled over on an unnamed dirt road near Mangya, Qinghai. The owner opened the trunk, took out a parabolic antenna, aimed it at the sky, connected to Wi‑Fi, and his phone displayed "China Satcom satellite network connected." Three minutes later, he placed a WeChat video call — in an area with no terrestrial coverage, that call costs 27,999 yuan per year.
That same day, China Satcom launched its "satellite mobile data service" for the consumer market. Three contract device packages went on sale: the portable parabolic model at 27,999 yuan (120 GB annual data), the vehicle‑mounted flat‑panel at 35,800 yuan (data customisable), and the phased‑array mobile‑in‑motion at 47,200 yuan (also 120 GB). In equivalent terms, users pay about 230 yuan per GB for data. Starlink's comparable pricing in most global markets is roughly 7 yuan per GB, but Starlink cannot legally operate within China.
Who pays
China Satcom's own surveys show that 90% of hard‑core off‑road vehicle owners are willing to spend up to 1,000 yuan per trip on satellite communications. This group is the most direct target for the packages.
In June 2026, China Satcom appeared at the Taklimakan Rally with nearly 50 satellite internet terminals, covering six race zones, seven base camps, and thirteen stages. It was the densest deployment of satellite internet terminals ever seen in a domestic off‑road race. The live‑broadcast vehicles on the stages, the support teams' dispatch communications, and the real‑time data backhaul for event safety personnel — these are the scenarios that define China Satcom's "consumer market": not everyday internet for the general public, but a rigid need for specific people in specific places.
RV travellers are another group. People who live on the road need stable connectivity for work, entertainment, and staying in touch — the vehicle‑mounted flat‑panel package is aimed at them. The maritime sector is a third scenario: sport‑fishing boats, ocean‑going fishing vessels, and offshore exploration platforms, where no terrestrial base stations exist and satellites are the only option. There is one more group that does not fit any of the above: outdoor content creators. Their need is upstream bandwidth — pushing high‑definition video from no‑signal areas to platform servers in real time. The weight and deployment time of the portable antenna are now line items on their equipment checklist.
These four types of people share one common trait: they can afford an annual outlay of 28,000 yuan, and they have no alternative.
Who profits
China Satcom's 2025 annual report shows two starkly contrasting numbers.
Domestically: revenue of 2.089 billion yuan, up 8.85% year‑on‑year, with a gross margin of 37.25%. Broadcasting and security services, government and enterprise private networks, and wholesale VSAT transponder leasing — these B2B and B2G operations form the foundation. The domestic market has virtually no direct competition. GEO satellite spectrum and orbital slots are scarce resources, and licences are a hard barrier.
Overseas: revenue of 556 million yuan, down 10.64% year‑on‑year, with a gross margin of just 0.16% — a decline of 12.32 percentage points from the previous year. The annual report states: "We are making every effort to overcome the impact of Starlink on our international business." In plain language: in open overseas markets, Starlink Maritime has pushed China Satcom's GEO transponder wholesale business below the break‑even line.
Starlink Maritime terminals cost between US$299 and US$599, with monthly plans from US$250 to US$5,000 (depending on data tiers), latency of 30–50 milliseconds, and downstream speeds of several hundred Mbps. China Satcom's GEO satellites have a latency of about 600 milliseconds, terminals weigh kilograms, and bandwidth is sold wholesale to ship owners and ISP resellers in megabits per second. The two are not in the same competitive dimension.
In August 2026, the global GEO satellite communications industry saw a series of events: Hughes Network Systems filed for Chapter 11 bankruptcy, with its CEO acknowledging that "the impact of LEO constellations on GEO satellite internet is structural and cannot be addressed through business adjustments"; Europe's Eutelsat cancelled its GEO expansion orders; and Viasat retreated to government, enterprise, and maritime private networks. China Satcom is the only company still relying on a licensing barrier to sustain a consumer‑grade GEO broadband business.
What this package really is
Defensive, not offensive.
Using the domestic monopoly window, China Satcom packages surplus GEO capacity as a "consumer satellite internet" product, sells it at a high premium to domestic users with inelastic demand, and uses the proceeds to offset the gross‑margin erosion caused by Starlink in its overseas business.
The operating costs of China Satcom's domestic assets are already covered by its government and enterprise base. The in‑orbit satellites are sunk costs. Every additional GB sold to end‑users has a marginal cost close to zero. At 230 yuan per GB, the vast majority of that price is pure profit. This is not about opening a new market — it is incremental monetisation on existing satellites.
The window has a shelf life.
Two clocks
Thousand Sails (Qianfan). As of July 2026, 238 satellites in orbit. Target for end‑2026: 324 satellites, to achieve basic Asia‑Pacific coverage. Measured downlink speeds are 450–500 Mbps, uplink 100 Mbps, latency around 50 milliseconds. In June 2026, Qianfan successfully demonstrated 5G voice and video calls directly to unmodified commercial smartphones. The industry expects that after large‑scale commercial deployment, LEO constellation pricing will enter a range of "hundreds of yuan per month, no more than a thousand yuan per year." The gap between that and China Satcom's 230 yuan per GB is an order of magnitude.
China StarNet (GW constellation). Planned total: 12,992 satellites. As of August 2026, about 200 are in orbit. Target: 400 by 2027, 1,300 by 2029, full deployment by 2035. Its positioning is the national space‑ground integrated 6G foundation, emergency backup, government and border communications, and direct‑to‑handset services. StarNet has not released any consumer pricing plans. But its existence is redefining the role of GEO satellites — when LEO constellations provide blanket coverage, low latency, and direct terminal connectivity, GEO satellites will retreat to broadcasting, emergency backup, and specific government/corporate private‑line scenarios. This does not eliminate China Satcom; it redraws its business boundaries.
The Zhongxing‑16 satellite was launched in 2017 with a design life of 15 years. Thousand Sails plans to achieve Asia‑Pacific coverage by 2027. The overlapping window — 2027 to 2032 — is the period during which China Satcom's premium package can still exist. After that, whether through technological substitution or price compression, 230 yuan per GB will no longer have a place in the market.
One last thing
China Satcom's government and enterprise foundation will not be shaken. Broadcasting security, emergency border communications, and maritime/government private networks account for more than 70% of its revenue, carry a gross margin of 37%, and the company's debt‑to‑asset ratio is only 9.63%. LEO constellations will not take these businesses — broadcasting and emergency backup are natural strengths of GEO satellites that LEO cannot replicate.
What will be eliminated is a single product model: selling broadband access to ordinary consumers via GEO satellites.
The three packages launched on August 21, 2026, are a rational choice by China Satcom on the eve of an industry transformation. It uses the last window of its licensing advantage to sell the unused transponder capacity of a satellite launched in 2017 — at 230 yuan per GB — to the live‑broadcast vehicles at the Taklimakan Rally and the off‑road owners in the uninhabited areas of Mangya.
A sensible business decision. The clock is ticking.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.