
The Elevator Just Got a Fourth Person: CXMT’s $85 Billion IPO Is About to Ruin the Memory-Chip Party
Samsung, SK Hynix, and Micron have enjoyed a near-perfect oligopoly. But China’s lone DRAM maker doesn’t care about their unwritten rules — and it’s pressing every single button.
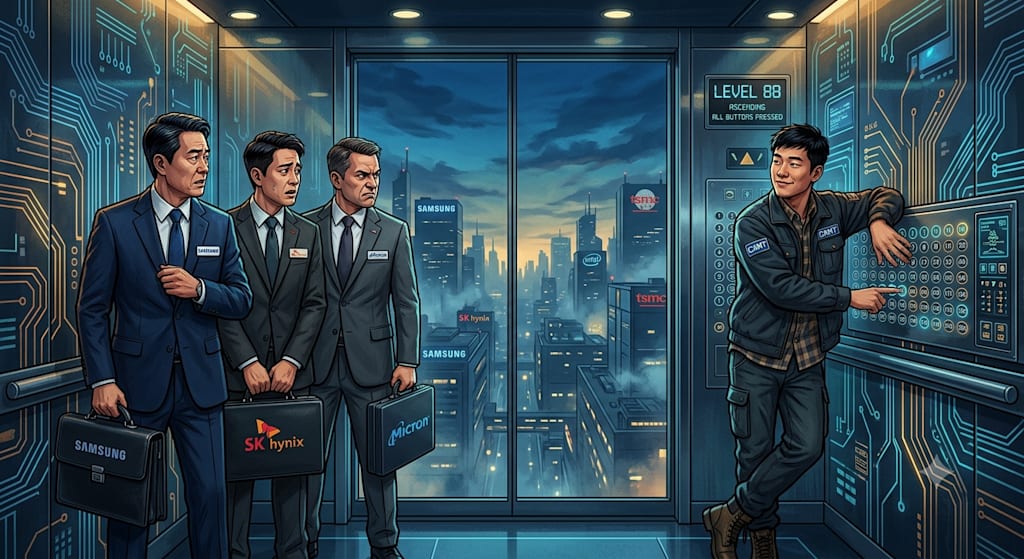
CXMT’s IPO: When Chinese Speed Collides with the Koreans’ Memory-Chip Party
On July 27, 2026, the Shanghai Stock Exchange will host an IPO the likes of which haven’t been seen in a decade. ChangXin Memory Technologies (CXMT), China’s sole DRAM chip manufacturer, will begin trading at a valuation of approximately $85 billion, with a fundraising scale of $9.8 billion.
On that same day, the CEOs of the global memory-chip industry’s three giants — Samsung Electronics, SK Hynix, and Micron Technology — will most likely be staring at the opening price, each in their own silence.
The past five years have treated these three well. Together, they hold roughly 90% of the global DRAM market. They set prices. They’ve ridden the AI wave to outsized profits, thanks to High-Bandwidth Memory (HBM) paired with Nvidia’s GPUs. In the first quarter of 2026, Samsung held 38% of the market, SK Hynix 29%, and Micron 22%. It’s a near-perfect oligopoly: few players, high barriers, rational capital spending, and fat margins.
But now, a fourth person has stepped into the elevator.
The four people inside the elevator each carry their own thoughts. The three old-timers know each other’s habits. They know when to push and when to yield. The newcomer carries no past baggage and has no intention of respecting the unwritten rules of the elevator. He presses every single button.
I. 90% Market Share Isn’t a Moat; It’s a Target
Where does the three giants’ money come from? Not from computer RAM sticks. That segment’s gross margins are razor-thin. The big money comes from HBM, the premium memory bundled with Nvidia’s GPUs. In this segment, SK Hynix holds 58%, with Samsung and Micron each at about 21%. AI server demand is going insane. HBM orders are booked years out. The three don’t need to engage in price wars. They just expand cautiously and collect the checks. From 2025 through 2026, their quarterly profits broke records one after another.
The fragility of this structure lies in one assumption: that no one can build production capacity fast enough to break the supply-demand balance.
The traditional barriers to entry in DRAM are indeed high. A single fab takes three to six years from groundbreaking to mass production, with investment starting at $10 billion. Add the difficulty of acquiring EUV lithography machines and a dense thicket of patents, and you’ll see why countless challengers have washed up on this beach over the past two decades. Investors trust this structure, which is why they assign premium valuations to the three giants. Analysts like to write “extremely high industry entry barriers” in their reports and then raise their price targets accordingly.
But CXMT doesn’t play by that rhythm.
Look at the numbers. In 2020, its monthly production capacity was 40,000 wafer starts per month (WSPM). By the end of 2026, it’s projected to reach 350,000 WSPM, almost catching up to Micron’s projected 375,000 WSPM for the same period.
Some will argue that numbers alone mean nothing. Capacity ramps face technology bottlenecks; low yield rates just produce piles of defective silicon. Fine. Then let’s talk about yields. CXMT’s DDR5 products have already entered the supply chain of mainstream PC OEMs. Yield data isn’t publicly disclosed, but if you’re making it into procurement lists at that level, it means your product holds its ground on the cost-performance curve. Otherwise, Apple wouldn’t be testing their chips. More on that later.
More critical is the construction speed. CXMT builds cleanrooms in roughly 12 months. The industry average is 21 to 24 months. That means it converts capital into production capacity twice as fast as its rivals. This isn’t some technological magic. It’s something you’d be hard-pressed to replicate in other markets: the ability to mobilize resources at scale and execute with singular focus. When Samsung, SK Hynix, or Micron builds a fab in South Korea or the U.S., they have to navigate environmental reviews, community hearings, local government tax-incentive negotiations; just the pre-construction process can take a year. CXMT doesn’t wait for any of that.
Some might say I’m overstating the case, that “building fast” isn’t the same as “building well.” But put yourself in the shoes of the three giants. Your competitor is adding capacity at twice your pace. Even if their individual chip performance lags half a generation behind yours, once the volume piles up, prices in the commodity market are heading downward. And the commodity market is exactly the part of your profit structure that acts as your “foundation.” It’s like your restaurant makes its money on signature dishes but relies on everyday staples to keep the customer flow steady. Now someone opens a basic-diner right across the street. Their food isn’t as good as yours, but the portions are bigger, the service is faster, and they’re running discounts every day. Can your customer flow possibly hold steady?
II. Where to Strike First? The Commodity Market, Not HBM
CXMT’s current technology level can’t yet reach HBM.
Constrained by its inability to acquire EUV equipment, it lags the three giants by about a generation and a half in advanced nodes. What it mass-produces is DDR5 and LPDDR5X. Its main battleground is PCs, smartphones, and standard servers; in other words, commodity DRAM.
This market has distinct characteristics: massive volume, price sensitivity, and violently fluctuating margins. In 2024, the industry suffered a supply glut. During that period, the three giants’ gross margins were crushed into the single digits. Running their fabs meant bleeding money; shutting them down meant even greater losses. Then AI came to the rescue. HBM demand pulled up the average price across the entire DRAM market, and commodity DRAM got to ride the coattails.
But after CXMT enters the game, that ride may be over.
Its market share doubled from 3% to 8% in a single year. That doesn’t sound like much, but the marginal effect is substantial.
DRAM is a highly homogenized commodity: your DDR5 and my DDR5, plugged into a computer, are indistinguishable to the end user. Price is determined by tiny shifts in supply and demand. As CXMT’s capacity continues to ramp while the three giants also expand, the supply-demand equilibrium in commodity DRAM will break. Every additional 10,000 WSPM means another batch of chips that have to be sold at lower prices.
Over the past decade, the three giants developed a kind of “tacit restraint”: they wouldn’t blindly expand capacity and trigger price wars, because history had taught them brutal lessons. The memory price crash of the 2010s pushed the entire industry into losses. Samsung’s semiconductor division lost a billion dollars in a single quarter back then. They all remember that taste.
But CXMT isn’t bound by that tacit understanding. Its primary goal isn’t profit maximization; it’s “meeting domestic substitution demand from the Chinese market.” Under that objective, the logic of capacity expansion is entirely different. You’re not chasing short-term returns. You’re chasing share. You don’t care what this quarter’s gross margin is. You care about whether you can get downstream manufacturers to cross out “Samsung” on their procurement forms and write in your name instead.
The three giants aren’t sitting idle. Starting in 2025, they accelerated their own capacity expansions, trying to use their scale advantages to squeeze CXMT out. Samsung is expanding its Pyeongtaek plant. Micron is investing $100 billion to build four fabs in New York. SK Hynix, together with the South Korean government, is pouring over $500 billion into a new HBM manufacturing hub. But almost all of these projects won’t come online until the second half of 2027 through 2029.
This gives CXMT a window of opportunity. The $9.8 billion raised in its 2026 IPO, combined with potential future financing, will allow it to fill its arsenal before that window closes. It’s a war of attrition, not a blitzkrieg. The three giants have to defend the global market. CXMT only needs to attack the Chinese market. The defender has to spread its forces across the globe; the attacker can concentrate its forces and strike a single point repeatedly. In military terms, this is “concentrating superior forces to annihilate the enemy.” In business terms, it’s called a “regional focus strategy.”
III. Apple Is Testing CXMT’s Chips. This Is Bigger Than It Looks.
Geopolitics is the variable you can’t ignore.
The U.S. has placed CXMT on the Entity List, banning it from acquiring advanced semiconductor equipment. In theory, that should choke off its upward trajectory. No EUV means you can’t make DRAM below 7 nanometers. In HBM and other advanced products, you’ll never catch up.
But CXMT changed its approach. It isn’t going after HBM. It’s going after the commodity market, where EUV isn’t required. It uses mature nodes, combined with deep ultraviolet (DUV) lithography and multi-patterning techniques, and still produces DDR5-class products. The main damage of U.S. export controls is in “blocking the future.” But in the “present” segment, CXMT is already up and running.
More importantly, there’s a “downward force” at work in the market.
According to reports, Apple is testing CXMT’s memory chips for use in devices sold outside mainland China. The reason: memory costs are too high, and Apple needs to push prices down. Think carefully about how delicate this situation is. Apple’s supply chain vetting is notoriously stringent. Suppliers have to pass checks on quality, capacity, stability, ESG compliance, and a dozen other criteria. If Apple has reached the testing stage, it means CXMT’s yields and performance have at least cleared the bar; not “barely usable,” but “won’t cause problems when installed in tens of millions of devices.”
And if even Apple is looking for alternative suppliers, it’s not hard to imagine what procurement departments at other device makers will do. Dell, HP, Lenovo: their procurement managers have cost control as a hard KPI. When CXMT’s memory chips are 15% to 20% cheaper than Samsung’s, and the performance difference is imperceptible in consumer-grade scenarios, do you think they’ll hesitate?
Export controls have indeed slowed CXMT’s progress on advanced nodes. But they can’t stop its penetration of the mid-to-low-end market. And that mid-to-low-end market is precisely the weakest link in the three giants’ profit structure. The money earned from HBM subsidizes the thin margins of commodity DRAM. If commodity DRAM gets pushed into losses, HBM profits will be severely eroded. At that point, the three giants aren’t dealing with “making less money”; they’re dealing with “what do we use to fund R&D?”
There’s one detail worth elaborating on. During CXMT’s IPO roadshow, its CEO was asked about capacity glut risks. His response: “We’re not just looking at the Chinese market; we have a global layout.” The subtext: CXMT’s long-term goal is to compete directly with Samsung, SK Hynix, and Micron overseas, not merely to serve the domestic market. But given the current technology gap and geopolitical constraints, that path is still long. The more realistic route is to first consolidate the domestic market, capture 15% to 20% share, and then use the cost advantages from China’s economies of scale to spill outward.
If it reaches that point, global DRAM market pricing power will no longer rest with the three giants. It will shift to the largest buyer, and the largest buyer is China. This is exactly the logic of the oil market: it’s not the oil-producing countries that set prices; it’s the largest consumers and producers together. China is the world’s largest semiconductor importer. Once it has domestic alternative capacity, its bargaining power in global procurement negotiations will undergo a qualitative transformation.
IV. The Investor’s Dilemma
The day CXMT’s IPO was announced, Micron’s stock price fell 8%. The market has already delivered its initial verdict.
But the situation isn’t that simple. Optimists and pessimists each have their own data.
The optimist’s logic: AI demand is large enough to absorb all new capacity. The memory supply-demand gap over the next few years is enormous. Some institutions project that by 2028, the world will need to produce chips equivalent to “all currently existing DRAM combined” just to meet AI training and inference demand. The incremental market is large enough to feed four or even five players. As long as the AI narrative holds, the three giants can maintain their excess profits through HBM’s technological moat. The short-term impact of CXMT’s IPO is largely psychological; fundamentals remain unaffected.
The pessimist’s logic: DRAM is a commodity at its core, and commodities don’t escape cycles. CXMT’s entry breaks the three giants’ capacity discipline. Once Chinese capacity floods the market in full force, the industry will slide directly from “shortage” to “oversupply,” followed by price wars and industry-wide losses. We’ve seen this movie before. Japan in the 1980s, Korea in the 1990s: every time a new player entered, it was accompanied by price collapses and the elimination of incumbents.
Both logics have merit. The critical point of divergence is the timing.
CXMT’s current capacity ramp will accelerate into high gear between 2027 and 2028. Meanwhile, the three giants’ expansion projects in the U.S. and South Korea mostly come online between the second half of 2027 and 2029. That is to say, from late 2027 through 2028, the global DRAM supply side will face a concentrated surge. At that point, whether AI demand can maintain its current growth rate is a huge question mark.
If AI demand growth slows while all four players ramp up supply simultaneously, the price war will be brutal. But if AI demand continues to grow at 30% to 50% annually, the new capacity might just get absorbed by demand, prices hold steady, and all four survive.
So what you’re betting on now is essentially your judgment of AI demand growth in 2028. And AI demand depends on several even larger variables: global tech giants’ capex plans, progress in commercializing large models, and whether the U.S. will tighten AI chip exports to China at some point, thereby affecting China’s domestic AI computing infrastructure buildout.
An investor friend once told me: “Making predictions in the DRAM industry is essentially guessing a four-dimensional function co-determined by Samsung, SK Hynix, Micron, and the Chinese government. Move any one variable, and the entire curve shifts.”
That may be true, but money still has to be deployed. CXMT’s IPO will definitely be oversubscribed, that’s the combined effect of political alignment and market enthusiasm. But how long-term capital allocates itself is another matter entirely. Fund managers are thinking: if a price war does break out in 2028, CXMT, backed by the Chinese market and state funding, might be the most resilient of the four players. It doesn’t need to be profitable. It just needs to survive. The three giants answer to shareholders. A drop in profits will trigger a stock crash and the CEO’s head on a platter.
Thinking this through, CXMT’s IPO may pose a threat to the three giants not by “stealing your market share,” but by “forcing you to choose between holding share and holding profits.” And that choice itself is a form of attrition.
V. History Doesn’t Repeat, But It Rhymes
In the 1990s, Japanese manufacturers swept the global DRAM market with low prices. Then they were dethroned by the Koreans.
The Japanese manufacturers of that era had some similarities with today’s CXMT: government backing, low-cost financing channels, and an intense hunger for market share. NEC, Toshiba, Hitachi: they once controlled half the global DRAM market. What happened next? The Koreans used faster capacity expansion, more aggressive pricing strategies, and more flexible capital deployment to push the Japanese out of the market. The Japanese retreated to materials and equipment, ceding the finished DRAM market.
History doesn’t repeat, but it rhymes. Now the challenger is China. The incumbents are Korea (Samsung and SK Hynix) and the U.S. (Micron). The technological barrier is EUV equipment. Geopolitics is the new variable.
But the underlying driver hasn’t changed: when an industry’s profit margins get high enough, capital and capacity will flood in. CXMT is just the specific person who showed up. If CXMT didn’t come, someone else would. China’s semiconductor self-sufficiency strategy ensures this challenge would have arrived sooner or later.
Some will say things are different now. U.S. export controls will block CXMT’s technology upgrade path forever; it’ll never reach HBM-level products. That argument has merit, but it ignores one fact: the commodity DRAM market is several times larger than HBM. Even if CXMT never makes HBM, as long as it establishes a foothold in the commodity market, it can materially impact the three giants’ overall profits. Just like an attacking army doesn’t necessarily need to capture the enemy’s headquarters; cutting off their supply lines is enough to cripple the forward troops.
VI. The Cards Are Dealt, But Not Yet Flipped
The reason CXMT’s IPO matters isn’t that it’s going to topple the three giants overnight. It matters because it marks the global DRAM market’s transition from a steady state of “three rational players” to a dynamic game of “three rational players plus one cost-indifferent capacity-expander.”
For the management of the three giants, the toughest stress test isn’t the day of CXMT’s IPO. It’s 2028, when CXMT’s full capacity comes online, and AI demand growth may be slowing. They’ll face a choice:
Hold capacity discipline, and let CXMT take market share.
Launch a price war, sacrifice profits, and hold share.
Whichever path they choose, the end result is the same: declining margins. The only difference is “a slow decline” versus “a cliff drop.”
Capital markets have already begun pricing this in. Micron’s 8% drop, SK Hynix’s pullback in the Korean market, the valuation discounts on Samsung’s semiconductor division in recent financing rounds: these signals stack together, all pointing in the same direction. The market knows the three giants’ “excess profits” aren’t permanent. It just doesn’t know when the inflection point will come.
CXMT’s IPO is the final step taken before sitting down at the table. The $9.8 billion raised is the chips on the table. The $85 billion valuation is the confidence. The domestic demand of the Chinese market is the hole card. The three giants’ hand is clear: they have HBM’s technological advantage, decades of customer relationships, and a global capacity footprint.
But the game has just opened. The dealer has placed the chips on the table. The cards haven’t been flipped yet.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.