
Nanotechnology Packaging: The Invisible Barrier Between Market Leadership and Obsolescence
The market is projected to grow from a base value of USD 18.2 billion in 2026 to USD 37.6 billion by 2033, reflecting a robust CAGR of 10.8% during the forecast period.
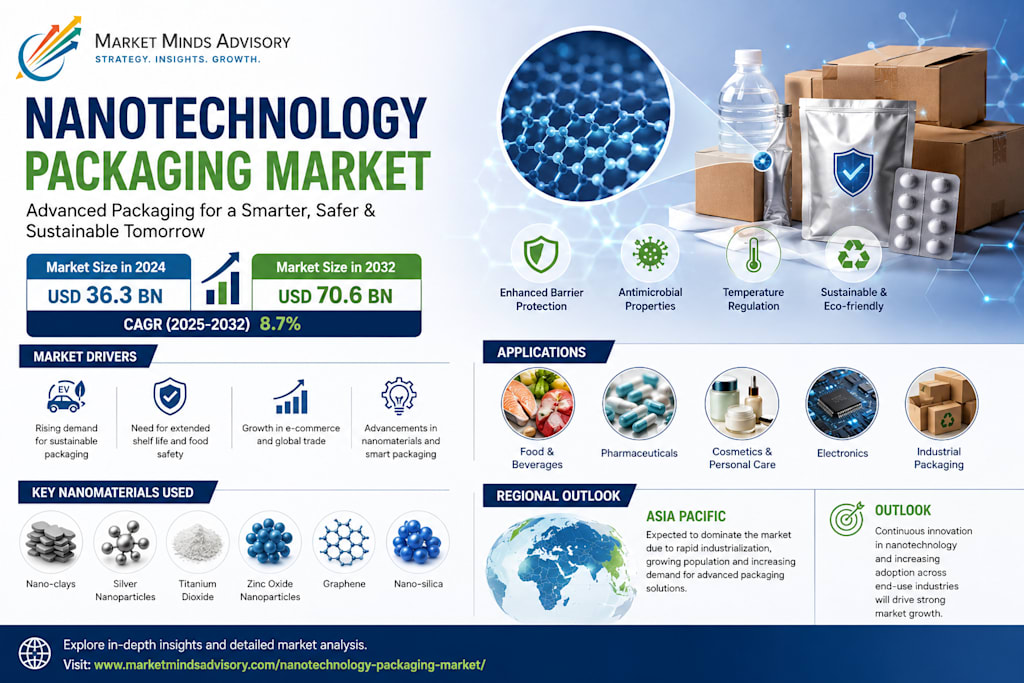
The packaging industry faces a silent disruption that most companies are underestimating. While competitors debate sustainability messaging and incremental material improvements, a fundamental shift in molecular engineering is redrawing competitive boundaries. Nanotechnology packaging isn’t emerging as a premium option anymore; it’s becoming the baseline expectation for brands that refuse to accept contamination, waste, and supply chain vulnerability as cost-of-doing-business realities.
Why Molecular-Level Performance Now Defines Commercial Viability
The traditional packaging value proposition has collapsed. Consumers and regulators no longer accept the trade-off between protection and environmental impact. Brands are discovering that conventional barrier materials cannot simultaneously deliver extended shelf life, reduced plastic usage, and verifiable sustainability credentials. This three-way tension is forcing a material science reckoning.
Nanotechnology packaging solves what incremental innovation cannot. By manipulating materials at the nanoscale, manufacturers achieve barrier properties that were physically impossible with traditional polymers. A nanolayer measuring 50 nanometers can outperform conventional barriers ten times thicker, fundamentally changing the economics of material usage, transportation weight, and end-of-life processing.
The business case has shifted from theoretical to operational. Food manufacturers are documenting 40-60% shelf-life extensions without refrigeration upgrades. Pharmaceutical companies are eliminating cold chain requirements for temperature-sensitive biologics. Electronics brands are reducing corrosion-related returns by factors that materially impact warranty reserves. These aren’t marginal gains; they represent structural cost advantages that compound across global supply chains.
Structural Shifts Driving the Market
Regulatory Pressure Is Eliminating Conventional Options
Governments worldwide are implementing packaging regulations that traditional materials cannot satisfy. The European Union’s push toward circular economy mandates, combined with single-use plastic restrictions across Asia-Pacific markets, is creating compliance gaps that only advanced materials can bridge. Nanotechnology packaging offers the rare combination of enhanced performance with reduced material volume, directly addressing regulatory intent while improving product protection.
Extended Producer Responsibility schemes are changing cost structures. When brands bear financial responsibility for end-of-life packaging management, the economics of lightweight, high-performance nano-enhanced materials become compelling. Companies that delay adoption are building future liabilities into current product designs.
Supply Chain Fragility Is Accelerating Adoption
Recent disruptions exposed how packaging limitations constrain business continuity. Products requiring continuous refrigeration, multiple protective layers, or frequent replacement due to barrier failure create systemic vulnerabilities. Nanotechnology packaging reduces these dependencies through:
Passive temperature regulation via phase-change nanomaterials
Antimicrobial surfaces that extend safe handling windows
Oxygen and moisture barriers that eliminate preservative requirements
Structural reinforcement that reduces damage-related waste
Organizations are recognizing that packaging performance directly determines supply chain resilience. The ability to extend product viability without active environmental controls translates into strategic flexibility during disruptions.
Consumer Transparency Demands Are Forcing Material Innovation
Brand value increasingly depends on verifiable sustainability claims. Consumers and institutional buyers are rejecting greenwashing, demanding proof of environmental impact reduction. Nanotechnology packaging provides measurable advantages: quantifiable plastic reduction, extended product life that reduces food waste, and enhanced recyclability through material purity.
Smart packaging integration is becoming table stakes. Nano-enabled sensors that communicate freshness, authenticity, and handling conditions are transitioning from premium features to competitive necessities. Brands without this capability face growing disadvantage in channels where product integrity verification drives purchasing decisions.
Where the Real Opportunity Lies
The highest-value applications aren’t where most companies are looking. While food and beverage dominate current adoption, the strategic opportunity concentrates in sectors where packaging failure carries catastrophic consequences.
Pharmaceutical and biotech applications represent the most defensible market position. Nano-enhanced packaging for cell and gene therapies, personalized medicines, and temperature-sensitive vaccines creates switching costs and regulatory moats that protect margins. Companies establishing expertise here build capabilities that translate across multiple high-value verticals.
Electronics and semiconductor packaging is undergoing forced evolution. As chip geometries shrink and performance requirements intensify, moisture and contamination sensitivity increases exponentially. Nanotechnology packaging that provides molecular-level environmental control is becoming a prerequisite for next-generation product reliability.
Active and intelligent packaging integration offers the clearest path to differentiation. Combining nano-enhanced barriers with embedded sensors, time-temperature indicators, and authentication features creates integrated solutions that command premium positioning while generating recurring data value.
Competitive or Strategic Shift
The competitive landscape is fragmenting between material innovators and application integrators. Traditional packaging manufacturers face a strategic choice: invest in nanotechnology capabilities or accept commoditization of their core business. The middle ground is disappearing.
Early movers are establishing patent positions and manufacturing expertise that create meaningful barriers to entry. The technical knowledge required to consistently produce nano-enhanced materials at commercial scale, while meeting food-contact and pharmaceutical-grade safety standards, represents years of development investment. Companies delaying entry are conceding these positions to competitors.
Partnership strategies are diverging. Some manufacturers are licensing nanotechnology from material science specialists, accepting margin pressure to maintain market access. Others are acquiring capabilities through M&A, betting that vertical integration will provide sustainable advantage. Both approaches carry risk, but inaction carries certainty of marginalization.
Brand owners are beginning to specify nanotechnology packaging in supplier agreements, shifting adoption from optional to mandatory. This demand-side pull is accelerating faster than many suppliers anticipated, creating fulfillment gaps that advantage prepared competitors.
The Cost of Delayed Action
Companies that postpone nanotechnology packaging adoption are building compounding disadvantages into their operations:
Regulatory non-compliance risk: Upcoming packaging regulations in major markets will make conventional materials legally unviable for specific applications, forcing rushed transitions under unfavorable terms
Competitive product performance gaps: Rivals using nano-enhanced packaging will demonstrate measurably superior shelf life, safety, and sustainability, eroding market share in quality-sensitive segments
Stranded capital in obsolete infrastructure: Manufacturing and supply chain investments optimized for traditional packaging will require premature replacement as nano-enhanced alternatives become standard
Lost data and consumer engagement opportunities: Smart packaging capabilities that competitors deploy today create customer relationships and insights that become increasingly difficult to replicate
Margin compression from commodity positioning: Brands without advanced packaging differentiation face intensifying price pressure as packaging becomes their only remaining variable cost to cut
The window for strategic positioning is narrowing. Early adopters are securing supply agreements, building technical expertise, and establishing brand associations with innovation that late entrants will struggle to overcome.
About the Creator
Sanjay Vane
At Market Minds Advisory, we’re more than just consultants—we’re partners in your journey to growth and success.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.