
Jensen Huang’s Son-in-Law Runs Nvidia’s AI Money Machine
Nico Caprez married the boss’s daughter, skipped a layer of management, and now helps turn GPUs into loans, credit, and demand.
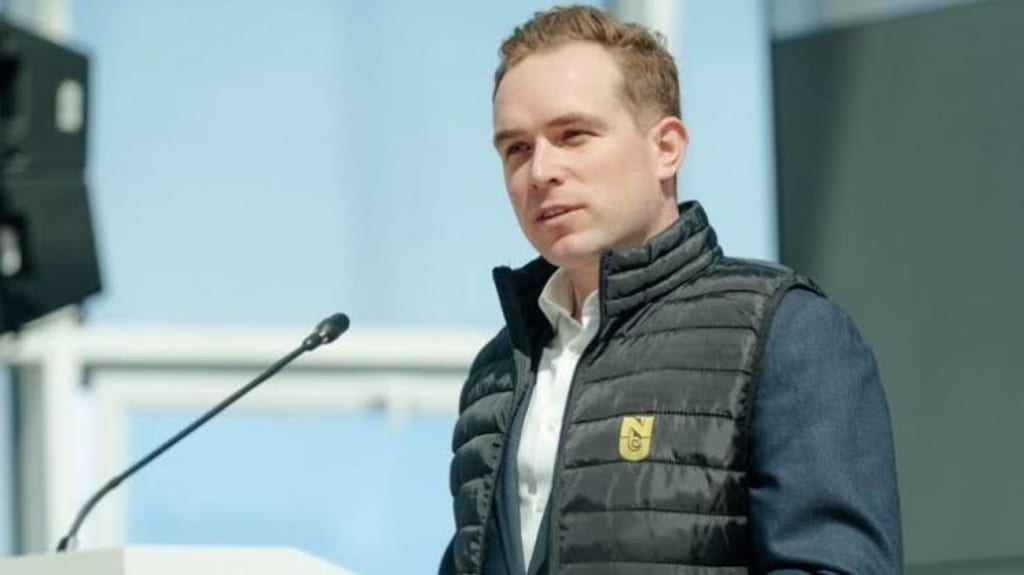
A little over a week after the wedding in Hawaii, Nico Caprez returned to Nvidia’s offices. He is 35, Swiss, a former professional alpine ski racer. After retiring, he joined Boston Consulting Group’s Zurich office, then went to London Business School for an MBA. There, he and Jensen Huang’s daughter, Madison Huang, became classmates.
Two and a half years ago, Madison recommended him to join Nvidia. In February 2024, his title was corporate development manager. In January 2026, he skipped senior director and was promoted directly to Vice President of Global AI Infrastructure Growth.
Nvidia employees are blunt about it. One employee who worked with Caprez said, “I think Jensen is paving the way for Madison and Nico to take over the next stage of work.” Another employee said Nvidia’s operating model is “far more like a family business than outsiders realize, which is very rare in tech.”
Jensen Huang responded to nepotism questions at an all-hands meeting in 2025. He said, “Parents won’t recommend children who would embarrass the company, and some second-generation employees are more capable than their parents.” That statement did not deny that family members had entered the core layer. It placed legitimacy on being capable enough.
Both of Jensen’s children have long been in business roles. His daughter Madison joined as a marketing intern in 2020. In March this year, she was promoted to Senior Director of Product Marketing for “Physical AI,” responsible for 3D world models, robot simulation, and other products. She frequently travels with her father to overseas supply-chain meetings. His son Spencer joined in 2022 as Director of Product Management for Robotics. In fiscal 2026, Spencer’s total compensation jumped from $530,000 to $1.32 million, surpassing Madison’s $1.232 million.
In Silicon Valley, founders handing off to professional managers is the default path. Bill Gates handed Microsoft to Steve Ballmer. Steve Jobs handed Apple to Tim Cook. Warren Buffett designated Greg Abel as Berkshire’s successor. Jensen Huang took another path.
Pan Helin, a scholar at Renmin University of China, wrote in an analysis that wealthy Western families tend to choose professional managers partly for estate-tax and financial reasons, and partly because dispersed equity creates governance constraints. Jensen Huang owns only 4% of Nvidia. His control rests on personal authority and internal social networks built over more than 30 years, not on an absolute controlling stake. This made him less psychologically burdened about appointing his children. What he wants to pass on is social relationships, not control itself.
This arrangement can be traced back to his long-term approach to raising his children. Madison studied a wine-related major and worked at LVMH. Spencer studied art and media and ran an Eastern aesthetics bar for eight years. Both did MBAs and entered key Nvidia management roles in the 2020s. Pan Helin summarizes this as “loosen first, then reel in”: let the children pursue their interests and build their own social circles during their “rebellious phase,” then return to Nvidia once mature to inherit the social relationships that made their father successful.
Caprez’s path was slightly different. BCG, London Business School, an asset management firm. Each step accumulated finance, management, and network resources. Meeting Madison at London Business School completed the most critical step. After joining Nvidia, his resume order was: corporate development manager, familiarizing himself with investment and partnership frameworks; exposure to emerging cloud vendors and financing structures, building client and capital relationships; Vice President of Global AI Infrastructure Growth, representing Nvidia in global AI infrastructure growth.
Jensen Huang’s trust in Caprez is almost public in the industry. Sikander Rashid, head of AI infrastructure at Brookfield Asset Management, recalled that when Jensen introduced Caprez at their first meeting last year, he said directly, “If there’s anything, find Nico.” A cloud company executive called Caprez Jensen’s “consigliere,” a term that originally meant a mafia boss’s most trusted confidant.
The business Caprez runs is the next growth model Jensen designed for Nvidia. Jensen has said Nvidia “started by making chips, and is now helping create a new, investable productive infrastructure: AI factories,” and asserted that “in AI, compute is revenue.”
Caprez is the core executor of this strategy. He mainly works with emerging AI cloud vendors such as CoreWeave and Nebius, helping them find customers and design financing and revenue-sharing plans. He helps these companies get the money to build data centers, then turns that money into Nvidia GPU orders. He is also designing credit backstops so undercapitalized AI cloud companies can afford expensive chips. Nvidia has provided loan guarantees to some customers totaling about $3.5 billion and may provide up to $250 billion in credit support to OpenAI.
In August 2026, Caprez helped push Nvidia to sign memorandums of understanding with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to establish an independent compute financing platform. The goal is to mobilize more than $500 billion in third-party capital to provide compute financing channels for AI labs, enterprises, and AI cloud service providers. Many details remain unsettled, but the direction is clear: turn GPUs from rapidly depreciating hardware into a “financeable asset class.”
Jensen Huang likens chips to aircraft: expensive, durable, and able to share risk through complex financial structures. Caprez put it more bluntly on LinkedIn: “Nvidia chips are financeable assets.”
Jensen Huang’s larger ambition is for Nvidia to play the role of an “AI central bank.” Gavin Baker, chief investment officer of Atreides Management, said on the Silicon Valley podcast All-In Podcast that Jensen, by providing unprecedented “vendor financing” to his largest customers, has bypassed currently constrained credit markets and “fundamentally changed Nvidia’s positioning, making it not just a hardware supplier but effectively a central bank of the AI economy.” Baker described Nvidia as a matchmaker between compute buyers and lenders, with the potential to become “the central bank of AI, the Fed of AI.”
Over the past several months, Nvidia has completed more than $140 billion in equity investments and M&A combinations and holds nearly $100 billion in equity investment market value. As of its latest quarter, Nvidia held $99 billion in cash and marketable securities. These numbers mean Nvidia is no longer just a chip company. It simultaneously acts as investor, loan guarantor, customer matchmaker, and network builder, four roles stacked into one entity.
Caprez is the daily executor of these roles. He connects customers, capital, cloud vendors, and Nvidia chip sales. Whoever controls these relationships controls the most important orders and partners for Nvidia over the next several years. Jensen placing his son-in-law in that position requires no additional explanation of strategic intent.
The core argument of critics is “circular financing”: Nvidia invests in AI companies or cloud service providers; those companies use the funds to buy Nvidia hardware; the revenue flows back to Nvidia. This cycle blurs the accounting boundary between investment and sales, and between real demand and financially manufactured demand.
Jensen Huang strongly rebuts this, saying Nvidia provides only “up to 25% of project scale” in financing support, with decision-making authority and independent due diligence handled by financial institutions. “Our role is to help unlock vast pools of independent capital while maintaining disciplined risk exposure.” He even quipped: “If this is circular financing, let’s do more of it.”
Market worries have not dissipated. Some analysts compare Nvidia’s backstop to “supplier financing” during the 2000 dot-com bubble. Back then, Lucent and other telecom equipment companies lent to financially troubled customers so they could buy Lucent equipment they otherwise could not afford. They recognized revenue on delivery while pushing credit and collection risk into the future.
This model created a growth flywheel in the upcycle and disaster in the downcycle. Lucent lent $6.7 billion to customers, of which $1.3 billion was effectively unrecoverable. When the dot-com bubble burst and telecom startups could not repay, Lucent had to write off billions of dollars in revenue tied to those deals and eventually went bankrupt. A Guolian Minsheng Securities research report summarized the transmission chain as: “financed customer bankruptcy → equipment maker bad debt → equipment maker credit rating downgrade → banks refuse to arrange new financing → new financing to customers constrained → sales decline → more bad debt → further credit rating downgrade.”
There is one key difference between Nvidia and Lucent: Lucent mainly made loans, while Nvidia mostly makes equity investments. The risk profile of equity investment differs from loans. You will not “default” just because a stock falls, but you may lose both your principal and the customer’s revenue stream. The Financial Times Lex column noted that when supplier financing “goes wrong, you lose both the customer and the financial exposure. Credit guarantees amplify risk. A bad equity investment may just waste money, but assuming customer debt can turn a valuation problem into a solvency problem.”
Nvidia currently has $80 billion in current assets and about $200 billion in annual operating cash flow. One or two customer problems will not shake its foundation. But as the $500 billion financing platform advances and customer concentration continues, risk exposure will only expand, not shrink.
The key variable here is whether revenue growth from end-user AI applications can keep up with capital expenditure growth. If financing becomes easier, customers are more able to buy equipment; more equipment purchases further “prove” AI demand is strong. This self-reinforcing narrative is powerful in an upcycle, but once end-user revenue disappoints, the problem of “financial demand replacing real demand” may appear. Stanford University’s 2026 AI Index shows Nvidia accounts for more than 60% of global AI compute capacity, while its top three direct customers contributed 44% of its first-half revenue. Customer concentration itself is a structural fragility. These large customers are also investing billions of dollars in self-developed substitute chips.
A more realistic risk comes from physical-world constraints. Morgan Stanley’s latest report points out that US data centers will face a net power gap of about 34% between 2026 and 2028, equivalent to 32 gigawatts. Power shortages may prevent chips from being deployed as planned. Even if AI servers are racked, without power they cannot be converted into actual compute and revenue. Oracle’s 1.3-gigawatt data center “Project Lighthouse” in Wisconsin is a real-world mapping of this risk: after transmission approval restarted, full-power supply may be delayed until October 2028 at the earliest, and in a pessimistic scenario until spring 2029. This means that even if all financing is in place and all chips are sold, physical infrastructure bottlenecks may still prevent “financial demand” from converting into “real compute revenue.”
Another warning signal comes from prediction markets. Kalshi data shows the H100 SXM GPU rental price is currently $2.79 per hour, and the market gives a 61% probability that it will stay above $3.23 by year-end. If rental prices continue to fall, that would be an early warning of compute oversupply, what podcaster David Sacks warned of as “dark GPUs,” like the unused “dark fiber” of the dot-com era.
Caprez’s promotion is essentially Jensen Huang placing the business most in need of trust into the most trusted person at a key node in Nvidia’s transition from a chip company to an AI infrastructure bank. This is both a prelude to family succession and the privatization of strategic execution.
But putting these two things together shows they are not advancing in parallel. They support each other. Nvidia’s AI infrastructure financing model requires a high degree of internal trust and fast decisions. The memorandums with six Wall Street giants, credit backstops for emerging cloud vendors, and the GPU-collateralized lending platform all share core features: enormous scale, novel structure, and a lack of historical precedent. In this environment, Jensen needs someone who understands finance and can carry out his will, not a professional manager who needs layer-by-layer reporting and must balance various interests. Caprez fits both conditions.
Family governance here is an institutional choice for strategy execution, not a byproduct of nepotism. Jensen needs an insider to run his most radical strategic bet.
The cost of this choice is transparency and checks and balances. Nvidia has no formal succession plan, and family members have no formal executive titles. But as more key positions concentrate in the “Jensen circle,” institutional investors’ concerns about governance quality will only increase. When Jensen eventually steps down, if there is no institutionalized power transition mechanism, the tension between family and professionalization may lead to a leadership vacuum or internal power struggle.
The model faces a test. It must withstand a turn in the AI investment cycle. If end-user AI application revenue growth fails to keep pace with capital expenditure, if power bottlenecks prevent built data centers from operating at full load, if H100 rental prices start to fall, any one of these triggers could turn the hidden worry of “financial demand replacing real demand” into reality.
Jensen Huang’s son Spencer once said at an internal event that joining Nvidia “was the best decision I ever made.” For Caprez, joining Nvidia was also a life-changing decision. But marrying Jensen’s daughter is a private matter; running Nvidia’s most core financial infrastructure business is a public matter. When private and public matters converge in the same company, the same family, and the same era-level bet, the job title is the easy part. The harder question is what family governance becomes when everything stops going well.
Lucent’s collapse showed that supplier financing can work too well. Its logic was sound enough to create an irrefutable growth narrative and make all participants believe “this time is different.” When the cycle breaks, the first to collapse is precisely the one who most believed “this time is different.”
After the Hawaii wedding ended, Caprez returned to the office. On his desk were a memorandum with six institutions, a GPU-collateralized loan structure table, and a CoreWeave client contact list. Jensen Huang’s words, “If there’s anything, find Nico,” were trust before the wedding and power after it.
About the Creator
Jin
Writer of reamstories
https://reamstories.com/jin
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed. You could also become a paid subscriber, letting them know you appreciate their work.
Comments
There are no comments for this story
Be the first to respond and start the conversation.