
How Shaan Arora bootstrapped Alia and sold it for up to $60 million without venture capital
The 24 year old founder built a Shopify popup platform from his parents' home, scaled it past $13 million in revenue, and sold it to Dotdigital without ever raising a venture round.

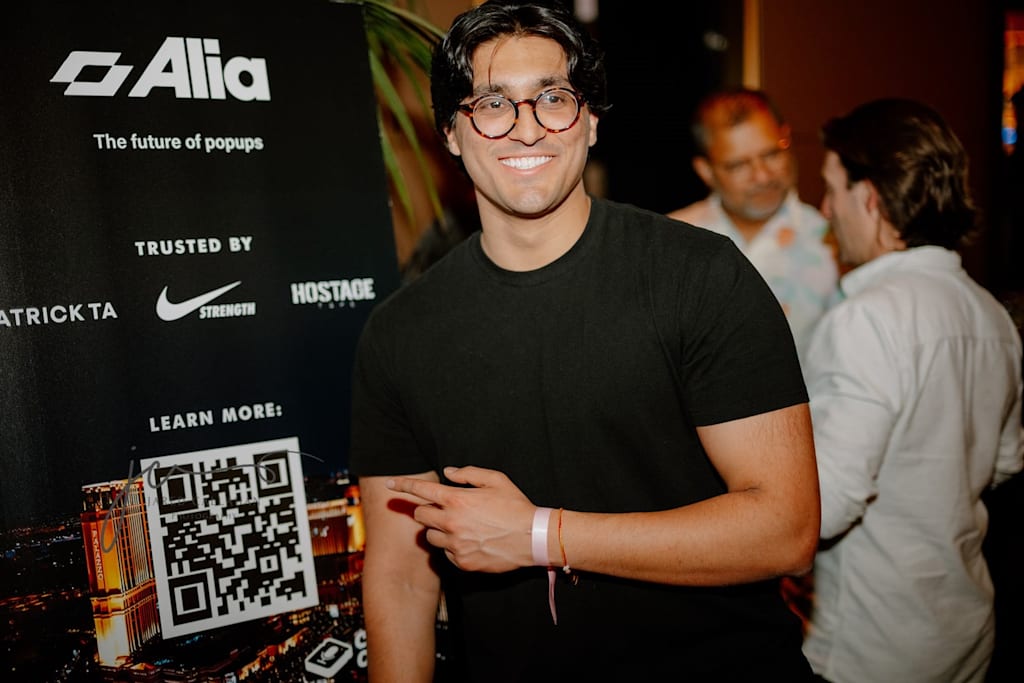
Shaan Arora was 24 when he sold his software company for up to $60 million, and he did it without ever taking a dollar of venture capital. That last part is the detail most founders cannot get past. The usual path in technology runs through pitch decks, seed rounds, and a cap table full of investors long before a product finds real customers. Arora skipped all of it. He and his co-founders started Alia (Alia Software, Inc.) from his parents' home, charged their first merchants about $20 a month, and won those early accounts one cold message at a time. Three years later, the London listed Dotdigital Group plc bought the company.
The numbers behind that exit are not modest. By the time Dotdigital announced the acquisition in March 2026, Alia served more than 5,000 Shopify merchants, produced more than half a billion popup views a month, and carried over $13 million in annual recurring revenue. Arora built all of it on customer money rather than investor money.
A company that started as a class project
Alia did not begin as a grand plan. It grew out of a campus project at Northeastern University that rewarded students for learning about financial technology, and an early version of the idea won the Hult Prize competition hosted by the Northeastern Entrepreneurs Club. Arora was still a student then, working toward a dual degree in computer science at the Khoury College of Computer Sciences and business administration at the D'Amore-McKim School of Business. He graduated in 2023, the same year he and cofounders Cory Gill and Bill Wohlers turned the project into a real company. That year BostInno also named Arora and Gill to its 25 Under 25 list.
He was not new to hard problems. Before Alia, Arora interned in quantitative finance, including time at Credit Suisse and the hedge fund Crestline Investors. Sitting close to markets taught him to respect data and to distrust any story the numbers did not support. That instinct shows up in how Alia was built, where decisions ran on what merchants actually did rather than on what a pitch deck promised they might.
The product that tunes itself
Alia is a popup and onsite engagement platform built for Shopify merchants. In plain terms, it helps ecommerce brands turn anonymous website visitors into email and SMS subscribers, the owned audience a brand can reach without paying a platform for access every time. It started as a loyalty and education tool that rewarded shoppers for learning about a brand, then became something more useful: a data driven popup system that tunes itself after setup instead of asking a marketer to babysit it.
The approach runs against the grain of how most popups work. Shoppers have been trained to close the aggressive, generic ones on sight, so Alia leans on a value exchange, giving the visitor a reason to hand over an email or a phone number rather than demanding it. The company's name fits that idea. Alia comes from a Latin word meaning different. Its growth followed the same quiet logic. Rather than buying attention through paid sales, Alia spread through word of mouth and agency partnerships, one merchant recommending it to the next. The client list makes the case better than any tagline could. AG1, Nike Strength, Peloton, ILIA Beauty, Victoria Beckham Beauty, and Veronica Beard have all used it.
Why he turned down the venture playbook
Plenty of founders would have raised money to move faster. Arora saw the tradeoff differently. Staying bootstrapped forced Alia to earn every customer and to learn what merchants actually paid for, which is much harder to fake when there is no investor runway to absorb the mistakes. The way he describes it, building without outside capital let him learn the market first and keep control of the company, and he has said he expects to remain a founder for the long haul.
That discipline is what made the exit possible on his terms. When Dotdigital acquired Alia Software in a deal announced on March 4, 2026, it set initial consideration at $30 million and total consideration at up to $60 million tied to performance. Arora did not cash out and vanish. He stayed to lead go to market strategy for Alia inside Dotdigital, where the team has grown past 50 people as the platform scales within the larger group. For a founder who spent three years keeping the company lean on purpose, staying on to run growth inside a public group was simply the next stage of the same project.
What comes next
Arora is doing something rare for a founder right after an exit: staying to build. At Dotdigital he is expanding the same popup platform he started in a family home, now with a public company behind it and a team many times the size of the one that shipped the first version. He is also still early. Most founders who sell a company before 25 spend the next decade proving the first win was not luck. Arora looks set up for exactly that. He treats Alia as a first step rather than a finish line, the opening chapter of a longer career spent building software that brands quietly depend on. The founder who once charged $20 a month has real capital now. What he seems to want is more time to build.
About the Creator
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.