
Compound Semiconductors Are Redefining Power Economics And Most Companies Are Still Playing Catch-Up
The market is projected to expand from a base value of USD 42.5 billion in 2026 to USD 81.2 billion by 2033, reflecting a robust CAGR of 9.5% during the forecast period.
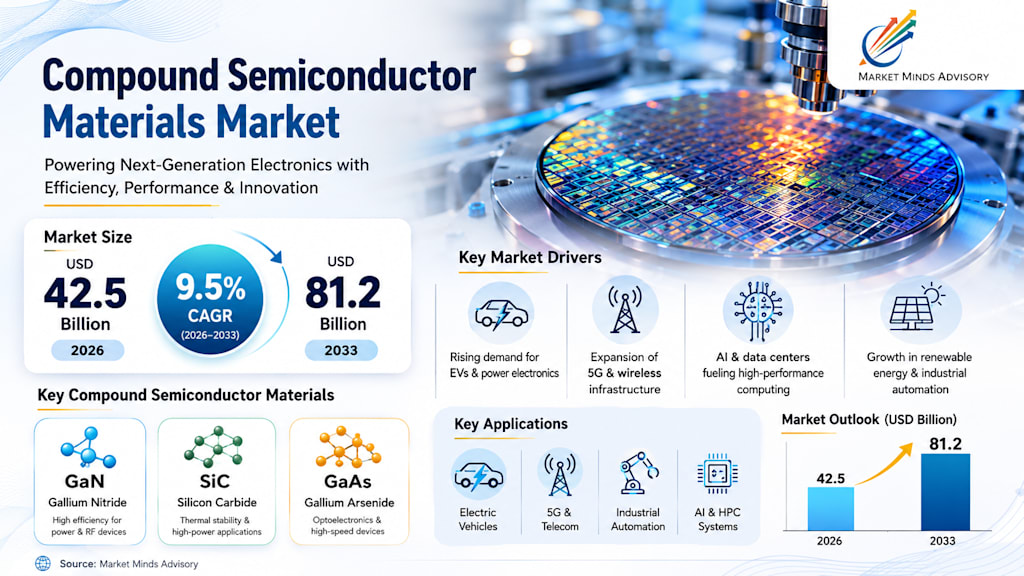
The energy equation underpinning modern infrastructure is fundamentally broken, and silicon-based solutions can no longer bridge the gap. As electrification accelerates and power density requirements surge across automotive, industrial, and grid applications, compound semiconductor materials have shifted from niche specialty to strategic imperative.
Why This Market Shift Matters Now
The transition isn’t gradual—it’s structural. Traditional silicon semiconductors are hitting physical performance limits precisely when industries need exponential improvements in efficiency, thermal management, and switching speeds. Compound semiconductors, particularly gallium nitride (GaN) and silicon carbide (SiC), deliver 10x better thermal conductivity and operate at voltages silicon cannot sustain. This isn’t incremental innovation; it’s a materials-level disruption that redefines cost structures in power conversion, electric drivetrains, and renewable energy systems.
Companies delaying adoption face compounding disadvantages. Early movers are locking in supply agreements, building proprietary manufacturing capabilities, and establishing performance benchmarks that will become industry standards. The window for strategic positioning is narrowing as automotive OEMs, renewable developers, and industrial equipment manufacturers accelerate qualification cycles.
Structural Shifts Driving the Market
Electric Vehicle Architectures Demand New Material Physics
The automotive industry’s shift to 800V electrical architectures has made compound semiconductors non-negotiable. Silicon-based inverters cannot efficiently manage the thermal loads and switching frequencies required for fast-charging systems and extended range targets. SiC power modules reduce energy losses by 50-70% compared to silicon IGBTs, directly translating to battery cost savings and vehicle performance differentiation. Major OEMs are now designing platforms around SiC availability rather than treating it as a component substitution, fundamentally altering supply chain dynamics and creating winner-take-all scenarios in material sourcing.
Grid Modernization Creates Unprecedented Demand for High-Voltage Switching
Renewable energy integration and grid decentralization require power electronics that can handle bidirectional flows, rapid load changes, and higher voltage levels. Compound semiconductors enable smaller, more efficient inverters and converters critical for solar installations, energy storage systems, and EV charging infrastructure. The efficiency gains compound across the energy value chain—a 2% improvement in inverter efficiency translates to millions in operational savings for utility-scale projects. Grid operators and renewable developers who lock in advanced material supply now gain structural cost advantages that persist for decades.
5G and Data Infrastructure Push Thermal and Frequency Boundaries
The explosion in data processing and wireless communication demands semiconductors that operate at higher frequencies with superior thermal dissipation. GaN-based RF components outperform silicon in base stations, satellite communications, and radar systems. As edge computing proliferates and 6G development accelerates, the performance gap widens. Companies relying on legacy materials face obsolescence in next-generation infrastructure bids, while those investing in compound semiconductor capabilities position for long-term platform wins.
Where the Real Opportunity Lies
The highest-value opportunities concentrate in applications where performance justifies premium pricing and where switching costs create defensible positions. Automotive power modules represent the largest near-term volume opportunity, but industrial motor drives and renewable energy inverters offer superior margin profiles with less competitive intensity. Strategic players are targeting applications where compound semiconductors enable entirely new product categories rather than simple component swaps—wireless charging systems, ultra-compact power supplies, and high-efficiency HVAC systems that weren’t economically viable with silicon.
Substrate and epitaxial wafer production present particularly attractive positions. These upstream materials represent bottlenecks in the supply chain, and companies controlling high-quality substrate capacity wield disproportionate influence over downstream device manufacturers. The technical barriers to entry remain high, and capacity expansion timelines stretch 18-24 months, creating persistent supply-demand imbalances that favor established producers.
Competitive Dynamics Are Consolidating Faster Than Expected
The market is bifurcating rapidly. Integrated device manufacturers with captive substrate production are pulling ahead, while pure-play material suppliers face margin pressure as customers backward-integrate. Joint ventures between automotive OEMs and semiconductor manufacturers signal a strategic shift—companies are treating compound semiconductor access as too critical to leave to open markets.
Geographic concentration adds complexity. Over 60% of SiC substrate capacity resides in a single region, creating geopolitical risk that automotive and defense customers increasingly view as unacceptable. Governments are responding with subsidies and domestic production mandates, fragmenting what was emerging as a global market. Companies without diversified supply strategies or domestic manufacturing roadmaps will find themselves excluded from major procurement cycles within 24 months.
Commoditization looms in lower-performance segments. As manufacturing yields improve and second-tier suppliers enter the market, pricing pressure will intensify for standard products. Differentiation will increasingly depend on material purity, defect density, and the ability to co-develop custom solutions with end customers—capabilities that require sustained R&D investment and deep application expertise.
The Cost of Delayed Action
Hesitation carries specific, measurable consequences:
Supply chain exclusion: Leading automotive and industrial customers are signing multi-year offtake agreements that absorb available capacity. Late entrants face allocation constraints and unfavorable pricing.
Technology lock-out: Next-generation product platforms are being designed around compound semiconductor performance envelopes. Companies using silicon will need complete redesigns to compete, adding 18-36 months to development cycles.
Margin erosion: Competitors achieving 5-8% efficiency advantages in power conversion will systematically underbid on lifecycle cost, even at higher upfront prices. The performance gap translates directly to lost market share in price-sensitive segments.
Talent and IP gaps: The specialized knowledge required for compound semiconductor integration is scarce. Companies delaying investment lose access to experienced engineers and fall behind in patent positioning.
What This Means for Decision-Makers
For Automotive OEMs and Tier-1 Suppliers
The strategic question isn’t whether to adopt compound semiconductors but how to secure supply and capture value. Vertical integration decisions made now determine competitive positioning through 2030. Consider direct investments in substrate capacity or long-term supply partnerships that guarantee allocation. Evaluate which power electronics capabilities to develop in-house versus outsource, recognizing that proprietary inverter designs create differentiation that component purchasing cannot replicate.
About the Creator
Sanjay Vane
At Market Minds Advisory, we’re more than just consultants—we’re partners in your journey to growth and success.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.