
Collaborative Robots Are Redefining Factory Economics Faster Than Most Manufacturers Realize
The market is projected to grow at 21.4% over the forecast period, reaching USD 10.9 billion by 2033.
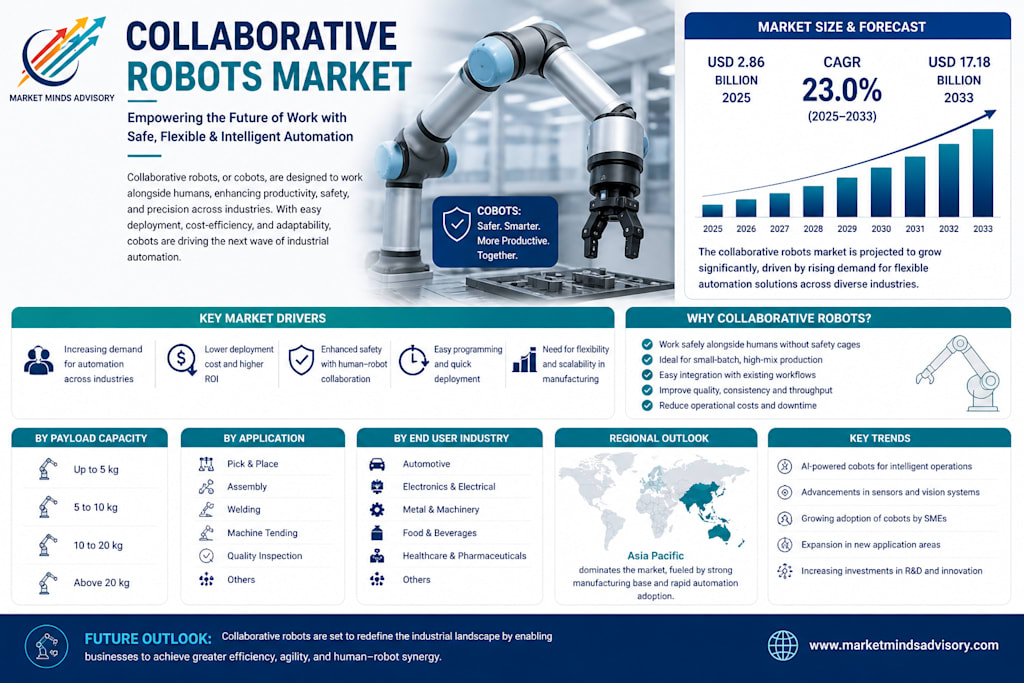
The window to capture first-mover advantage in flexible automation is narrowing as cobots shift from experimental to mission-critical infrastructure.
Manufacturing’s Automation Paradox Is Breaking
For decades, industrial automation meant a binary choice: invest millions in fixed robotic cells or rely on manual labor. That calculus is collapsing. Collaborative robots have crossed a critical threshold where deployment costs, programming complexity, and safety barriers have dropped so dramatically that mid-sized manufacturers can now automate processes previously considered uneconomical. The result is a fundamental restructuring of production economics that’s catching traditional automation buyers and industrial robot vendors off guard.
What makes this shift urgent is timing. Early adopters are already achieving 18-24 month payback periods on cobot deployments while building institutional knowledge that creates compounding advantages. Meanwhile, companies still evaluating “whether” to adopt cobots are asking the wrong question. The real question is how quickly they can scale deployment before competitors lock in cost structures they cannot match.
Why Collaborative Robots Represent a Strategic Inflection Point
This is not incremental automation improvement. Collaborative robots are enabling a different production philosophy entirely. Traditional industrial robots excel at high-volume, repetitive tasks in isolated cells. Cobots operate alongside human workers, handle variable tasks, and redeploy across production lines in hours rather than weeks. This flexibility is unlocking automation in small-batch production, mass customization, and mixed-model manufacturing environments that were previously automation-resistant.
The business impact extends beyond labor arbitrage. Manufacturers deploying cobots report 30-40% reductions in changeover times, 25% improvements in floor space utilization, and the ability to accept smaller order quantities profitably. These operational advantages are reshaping competitive positioning in industries from automotive components to consumer electronics, where responsiveness and flexibility increasingly trump pure scale.
Three Structural Forces Accelerating Cobot Adoption
The Labor Reality No One Wants to Discuss
Skilled manufacturing labor shortages are not cyclical anymore. They are structural. Demographics, wage expectations, and career preferences have created permanent gaps in welding, machine tending, assembly, and quality inspection roles. Cobots are not replacing workers companies have. They are filling positions companies cannot fill. In Germany, 60% of cobot deployments now target roles that remained vacant for over six months. In the United States, manufacturers in secondary markets report using cobots specifically because they cannot attract workers at any reasonable wage.
This changes the ROI conversation entirely. When the alternative to cobot deployment is not hiring a worker but rather declining orders or moving production, payback calculations become almost irrelevant. The strategic question becomes capacity enablement, not cost reduction.
Technology Maturation Is Eliminating Adoption Barriers
Early cobots required specialized programming knowledge and careful application engineering. Current generation systems feature:
Vision systems that enable pick-and-place operations with minimal programming
Force-torque sensing that allows adaptive assembly without custom fixtures
Intuitive interfaces that floor supervisors can program in under two hours
Plug-and-play integration with existing PLCs and manufacturing execution systems
The result is a 70% reduction in deployment time and an 80% reduction in integration costs compared to traditional industrial robots. More importantly, manufacturers can now justify cobot deployment for production runs as small as 500 units, opening automation to product categories that never met traditional ROI thresholds.
End-User Industries Are Pulling, Not Being Pushed
Automotive suppliers face relentless pressure to handle more variants with shorter lead times. Electronics manufacturers must manage product lifecycles measured in months. Medical device companies navigate stringent quality requirements with small batch sizes. These operational realities are creating organic demand for flexible automation that traditional robotics cannot address.
The adoption pattern is telling. Cobot deployments are not concentrated in large OEMs with dedicated automation engineering teams. They are spreading fastest among Tier 2 and Tier 3 suppliers, contract manufacturers, and mid-market companies that previously could not justify automation investments. This democratization of automation is redistributing competitive advantage in ways that will take years to fully manifest.
Where Smart Money Is Focusing
The highest-value cobot applications are not the most technically sophisticated. They are the ones that unlock constrained capacity or enable new business models. Machine tending operations that allow lights-out production on second and third shifts. Quality inspection applications that catch defects before they propagate through assembly. Packaging and palletizing tasks that eliminate the bottleneck between production and shipping.
Particularly compelling are applications in welding and material removal, where cobots address acute skill shortages while delivering consistency that even experienced workers struggle to match. Companies deploying cobots in these areas report not just labor savings but quality improvements that reduce rework costs by 40-60%.
The geographic opportunity is also shifting. While early cobot adoption concentrated in Northern Europe and Japan, the fastest growth is now occurring in North America and emerging Asian markets where labor cost advantages are eroding and manufacturers face pressure to localize production. Companies that establish cobot deployment capabilities in these markets early are building advantages that will compound as adoption accelerates.
How Competitive Dynamics Are Shifting
The cobot market is fragmenting in ways that create both opportunity and risk. Traditional industrial robot manufacturers are adding collaborative features to existing product lines, but often with compromises in true collaborative capability. Pure-play cobot vendors are expanding rapidly but face questions about long-term viability as larger players enter the market. Meanwhile, end-users are increasingly demanding integrated solutions that combine cobots with vision systems, grippers, and software rather than standalone hardware.
This fragmentation creates a dangerous dynamic for buyers. Choosing the wrong platform can lock manufacturers into proprietary ecosystems that limit future flexibility. Conversely, waiting for standards to emerge means ceding first-mover advantages to competitors who are already optimizing production around cobot capabilities.
The commoditization risk is real but unevenly distributed. Basic pick-and-place and machine tending applications are becoming standardized, with differentiation shifting to software, integration services, and application expertise. Companies that treat cobots as generic capital equipment will find themselves competing purely on price. Those that build institutional knowledge around cobot deployment and optimization will create defensible advantages.
What Happens When Companies Wait Too Long
Delayed cobot adoption carries specific, measurable consequences that worsen over time:
Competitive cost disadvantage compounds: Every quarter competitors operate with cobot-enabled cost structures, they can reinvest savings into further automation, creating a gap that becomes increasingly difficult to close
Talent acquisition becomes harder: As cobots become standard in manufacturing environments, skilled workers increasingly expect to work with modern automation, making it harder to attract talent to manual operations
Customer expectations shift: Buyers increasingly expect the responsiveness and consistency that cobot-enabled manufacturing delivers, making it difficult to retain business with traditional production approaches
Capital allocation becomes constrained: Companies that delay automation investments often find themselves forced to make larger, riskier investments later when competitive pressure intensifies and financial flexibility is reduced
The most insidious risk is organizational learning. Companies deploying cobots now are developing institutional knowledge about where automation creates value, how to optimize human-robot collaboration, and which applications justify investment. This knowledge accumulates slowly and cannot be purchased or replicated quickly when competitive pressure finally forces action.
About the Creator
Sanjay Vane
At Market Minds Advisory, we’re more than just consultants—we’re partners in your journey to growth and success.
Enjoyed the story? Support the Creator.
Subscribe for free to receive all their stories in your feed.
Comments
There are no comments for this story
Be the first to respond and start the conversation.